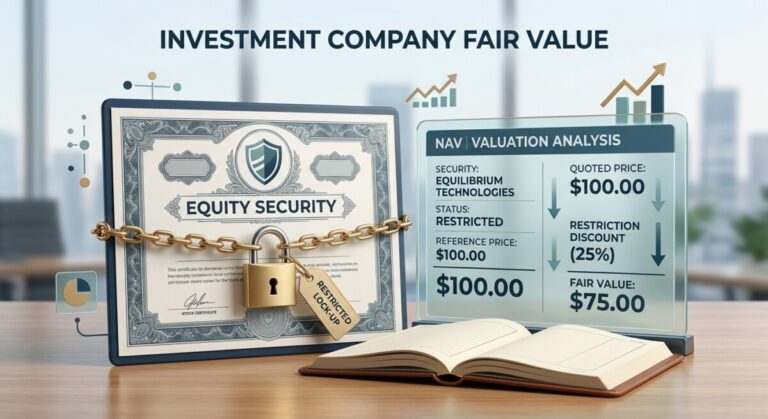
Investment company fair value: a locked equity security discounted on a fund's NAV ledger
|

ASU 2026-03: investment company fair value guide

How does ASU 2026-03 change investment company fair value? It requires an investment company to apply a discount when a contractual sale restriction prevents it from selling an equity security on the measurement date. The amendment is scoped to investment companies and to equity securities only, is effective for annual periods beginning after December 15,…
FASB ASU 2026-03: contractual sale restrictions and fund NAV
|

Does ASU 2026-03 change fair value sale restrictions?

Does ASU 2026-03 change fair value sale restrictions for investment funds? Yes — but only for investment companies within the scope of Topic 946. From adoption, those funds must incorporate a discount for contractual sale restrictions when measuring the fair value of an equity security, and disclose the size of that discount. Effective for annual…

FASB effective dates 2026: the ASUs first effective for calendar-year entities
|

FASB effective dates 2026: which ASUs kick in this year?

Which FASB standards take effect in 2026? The largest calendar-year first-effective ASUs are 2023-09 (income tax disclosures, private companies), 2024-04 (induced conversions of convertible debt, all entities), 2025-05 (AR credit losses practical expedient, PCC), and 2024-01 (profits interest awards, private companies). This post is a plain-English guide to the FASB effective dates 2026 that will…

SEC Regulation Crypto Assets proposal and FASB cash-equivalents proposal for digital assets released the same day in August 2026
|

What is SEC Regulation Crypto Assets & How It Works

What is SEC Regulation Crypto Assets, and does it change how I raise capital or report digital assets? The SEC proposed a new exempt-offering framework for crypto asset investment contracts on August 12, 2026, and FASB the same day proposed clarifying when certain digital assets — including some stablecoins — count as cash equivalents. Both…

Fasb hedge accounting updates 2026 featured

FASB Hedge Accounting Updates 2026: What Every CPA Must Know

What are the new FASB hedge accounting changes for 2026? The FASB approved targeted improvements in February 2026 that allow hedging of interest rate risk for held-to-maturity (HTM) debt securities, remove the OIS parameter from the SOFR benchmark rate, and expand net investment hedging for float-to-float cross-currency swaps. These changes apply to all entities and…

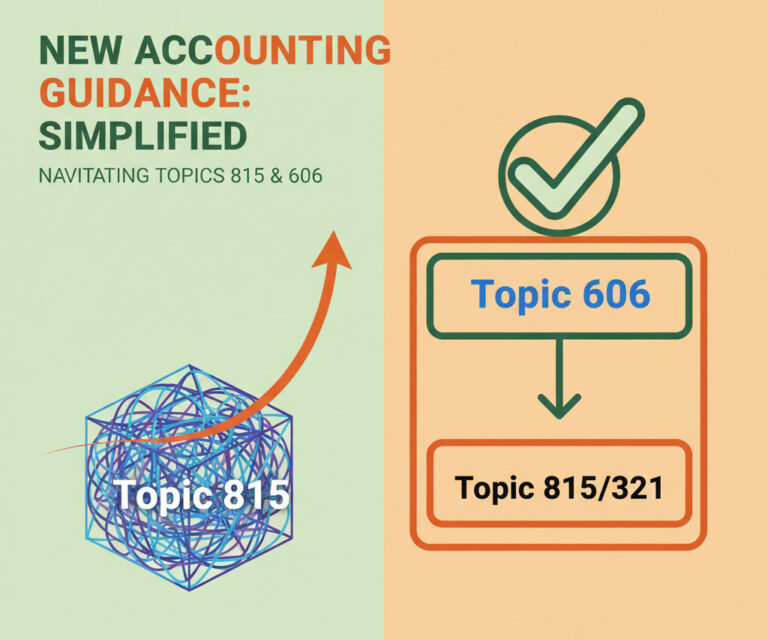
A professional, modern illustration for a finance and accounting blog. The image features a split-screen. On the left, a simplified graph shows a line 'escaping' a complex, tangled box labeled 'Topic 815', representing the new scope exception. On the right, a flow chart shows 'Topic 606' with a large green checkmark leading into a smaller box labeled 'Topic 815/321', representing the new clarification. The overall tone is clean, bright, and informative, using a green and orange color palette.

ASU 2025-07 Deep Dive: Understanding the New FASB Rules for Derivatives

  FASB’s New ASU 2025-07 Explained! This new update tackles two tricky accounting issues: a new scope exception for derivatives (Topic 815) and clarifying rules for share-based payments from customers (Topic 606). Let’s break down what you need to know.   Let’s be real, seeing a new FASB Accounting Standards Update (ASU) drop can make…

A professional and modern graphic for a finance blog post, featuring the text 'FASB ASU 2025-07 Update'. The design should incorporate abstract elements representing financial charts and contracts, using a vibrant green and orange color palette to convey clarity and positive change.

US GAAP : Big Changes to Derivative & Revenue Accounting – FASB ASU 2025-07

  Decoding FASB’s ASU 2025-07: Are you navigating the complexities of derivative accounting or uncertain how to handle share-based payments from customers? This comprehensive guide breaks down the latest FASB update, offering clarity and practical examples to simplify your accounting practices. Have you ever found yourself staring at a contract—maybe an ESG-linked bond or a…