A corporate boardroom table with two folders representing a Korean parent and a US subsidiary connected by an intercompany services invoice line.
|

Can my Korean parent use the services cost method?

Can my Korean parent charge my US subsidiary at cost for shared back-office work? Yes — if the service fits the services cost method (SCM) safe harbor in Treasury Regulation §1.482-9(b). SCM lets a Korean parent bill routine support services (bookkeeping, HR administration, payroll, IT help desk, legal admin) to a US sub at pure…
Charitable deduction under OBBBA: a donation envelope beside a tax form and a rising threshold shape
|

How does OBBBA change the charitable deduction in 2026?

Does OBBBA change the charitable deduction in 2026? Yes. Starting with the 2026 tax year, a new 0.5%-of-AGI floor and a 2/37ths cap on itemized deductions reduce the charitable deduction for most itemizers, but a new $2,000 above-the-line deduction and qualified charitable distributions give donors ways around them. Every November, a client calls our Los…

IRS partnership audits: TIGTA data show a sharp drop in exam starts since fiscal year 2023
|

Are IRS partnership audits really down in 2026?

Are IRS partnership audits really going away? Treasury performance data show partnership examination starts fell about 76% from fiscal year 2023 to fiscal year 2025, but IRS partnership audits are still live for the biggest partnerships, and the Bipartisan Budget Act regime still bills the partnership itself when one lands. A client calls after reading…

Adoption tax credit refunds: IRS automatic refunds for 2020–2024 carryforwards arriving in 2026
|

Who gets the IRS adoption credit refund in 2026?

Will the IRS send an automatic adoption credit refund? Yes, in many cases. In October 2026 the IRS began issuing an adoption credit refund to taxpayers who carried unused adoption credit forward from 2020–2024. No amended return is required for most eligible families. For many adoptive families, the adoption tax credit is the single largest…

Premium tax credit under OBBBA: a 1095-A form, a calculator, and marketplace enrollment reconciled on a desk
|

What are the new premium tax credit rules under OBBBA?

What are the new premium tax credit rules under OBBBA? The IRS and Treasury have issued proposed regulations (REG-101576-26) implementing H.R. 1 changes to Section 36B — the premium tax credit. The dollar cap on repayment of excess advance credits is gone starting with 2026 returns, new marketplace verification rules kick in after 2027, and…

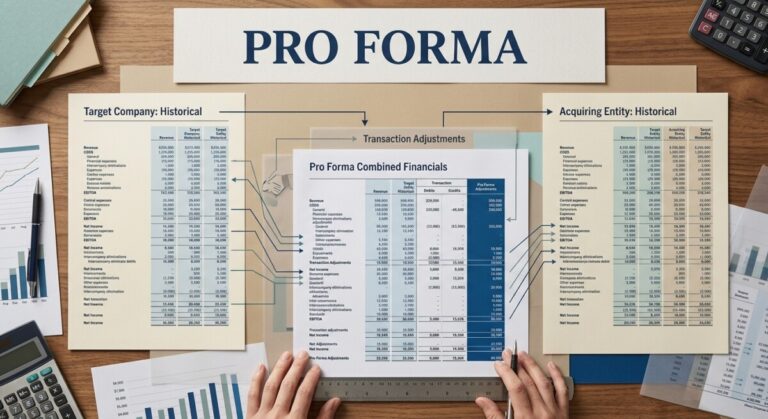
SEC pro forma financial information under Regulation S-X Article 11
|

What is pro forma financial information? SEC Article 11

When does the SEC require pro forma financial information? Regulation S-X Article 11 requires it for significant business acquisitions, dispositions, spinoffs, and other transactions where the illustration would be material to investors. The 2020 amendments reorganized pro forma financial information around three adjustment categories, and the columnar totals now stop at transaction accounting and autonomous…

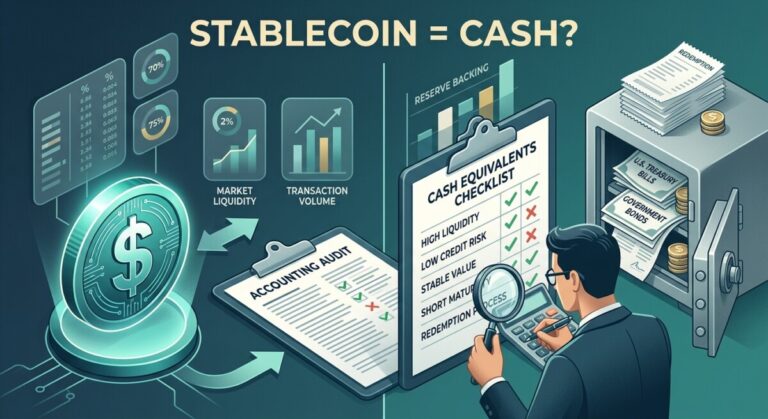
Stablecoin cash equivalents: FASB's three-attribute test under Topic 230
|

Can stablecoin cash equivalents pass FASB’s test?

Can a stablecoin be a cash equivalent under US GAAP? FASB’s August 2026 proposed Accounting Standards Update under Topic 230 says yes — but only when three attributes line up. The Master Glossary definition does not change. Stablecoin cash equivalents and a new disclosure of the significant components of cash equivalents are now on the…

|

How should a Korean company choose a US CPA firm? (And what to bring to the first consultation)

What should a Korean company check before choosing a US CPA firm? Check five things: which state licenses the CPA and whether the license is active, whether the firm also handles the Korea-side work (overseas direct investment reporting and the parent’s reporting package), whether the same team carries the work from setup into monthly books…

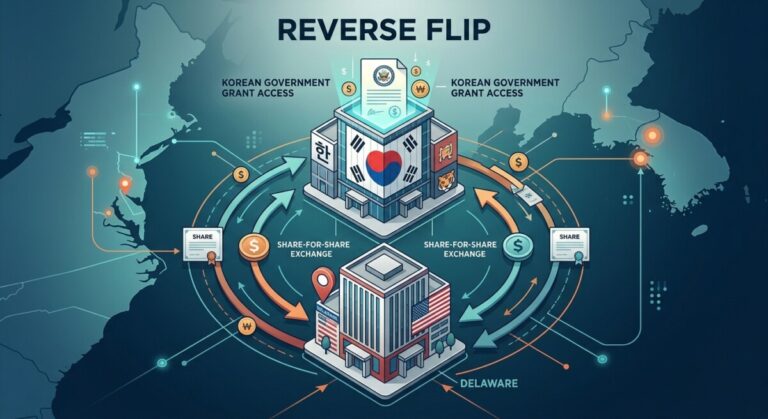
Diagram concept of a reverse flip Korea reorganization: a US Delaware C-Corp becoming a subsidiary of a new Korean holding company.
|

Can a US startup get Korean TIPS through a reverse flip?

Our US-incorporated startup wants Korean TIPS funding — can we just drop a Korean subsidiary under our Delaware C-Corp, or do we actually need to reverse flip to a Korean top? Dropping a Korean subsidiary does not qualify the group for Korean TIPS: the Korea Technology Finance Corporation and the operator programs run the grant…

SB 253 November 10 California climate-disclosure deadline for scope 1 and scope 2

SB 253 November 10: who files in California (2026)?

Does SB 253 November 10 apply to my company? California’s Climate Corporate Data Accountability Act requires US entities with annual revenue over $1 billion that do business in California to report scope 1 and scope 2 greenhouse gas emissions to the California Air Resources Board. CARB has proposed to move the first report from August…

Student loan forgiveness taxed again in 2026: a graduation cap next to an IRS tax notice
|

Is student loan forgiveness taxable in 2026?

Is student loan forgiveness taxable again in 2026? For most federal borrowers, yes. The temporary student loan forgiveness exclusion added by the American Rescue Plan Act sunset on December 31, 2025. Discharges in 2026 are generally includible in income under Internal Revenue Code §108, unless Public Service Loan Forgiveness, insolvency, or another specific exclusion applies….

California AI workplace laws: AB 1883, SB 951, SB 947 effective January 1, 2027

California AI workplace laws: AB 1883, SB 951, SB 947 explained

What do California’s new AI workplace laws require? Three bills — AB 1883, SB 951, and SB 947 — take effect January 1, 2027. The California AI workplace laws ban AI-powered emotion and neural monitoring, add technology-displacement disclosures to WARN Act notices, and require a human to review any AI-driven discipline or termination before it…

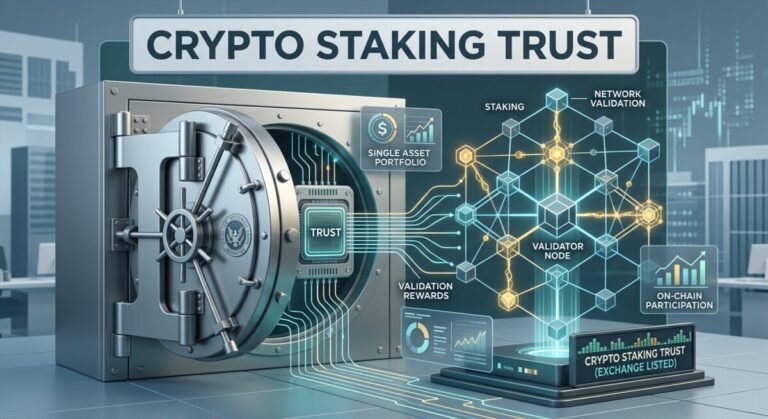
Crypto staking trust safe harbor: an SEC-registered investment trust staking digital assets on a proof-of-stake network
|

Can a crypto staking trust stay a grantor trust in 2026?

Can a crypto staking trust still qualify as a grantor trust in 2026? Yes — if it meets the fourteen conditions in IRS Rev. Proc. 2026-20. The new revenue procedure gives a crypto staking trust a safe harbor to stake its digital assets without losing investment-trust status under 26 CFR 301.7701-4(c). Every quarter we hear…

Business owner reviewing international tax developments on a tablet world map

International tax developments October 11, 2026

International tax moved in four places business owners should flag this week: the OECD put out a refreshed Model Tax Convention with a new remote-work permanent establishment framework, France filed its 2027 budget bill, South Africa opened consultation on a digital VAT architecture, and Singapore extended its innovation incentive to artificial intelligence adoption. What changed…

Business owner reviewing state and local tax developments at a desk

State and local tax developments October 11, 2026

State and local tax moves this week give business owners concrete tasks for the fourth quarter: a Washington DC conformity bill that forces federal-to-state add-backs, a Rhode Island amnesty window, a California cash-rounding law and a California conformity bill that changes who counts as a covered employee for the executive-pay deduction limit. What changed this…

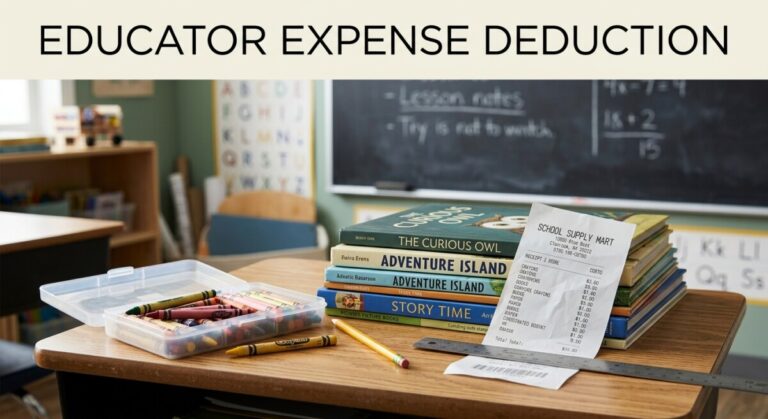
Educator expense deduction: a teacher's unreimbursed classroom supplies and the $300 above-the-line deduction they qualify for
|

Does the educator expense deduction cover pre-K teachers?

Who claims the educator expense deduction, and did pre-K get added? The educator expense deduction is a $300 above-the-line adjustment under IRC §62(a)(2)(D) for teachers, aides, counselors, principals, and instructors. Congress has moved to extend it to pre-K and early childhood educators through H.R. 5334, the SEED Act. Every spring, teachers walk into our Los…

AI software costs: capitalizing versus expensing under US GAAP (ASC 350-40)
|

Can you capitalize AI software costs under US GAAP?

Can you capitalize AI software costs under US GAAP? Sometimes. US GAAP has no AI-specific rule — the existing internal-use software guidance in ASC 350-40 still controls. If AI software costs are project-specific, measurable, and incurred after the application development stage begins, they may be capitalized. General-purpose AI subscriptions are expensed. Every quarter our Los…

Investment company fair value: a locked equity security discounted on a fund's NAV ledger
|

ASU 2026-03: investment company fair value guide

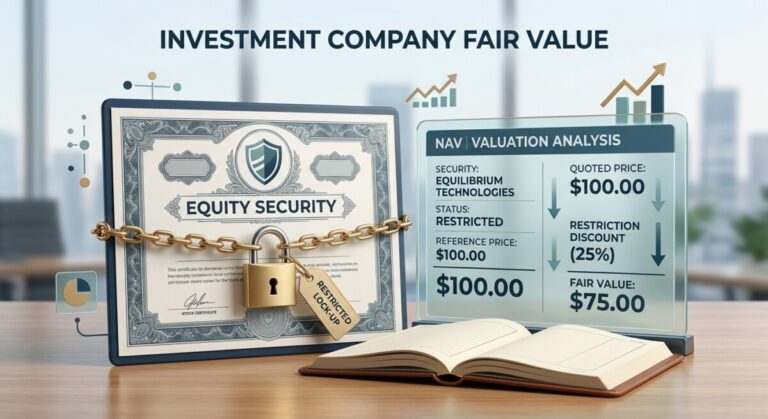
How does ASU 2026-03 change investment company fair value? It requires an investment company to apply a discount when a contractual sale restriction prevents it from selling an equity security on the measurement date. The amendment is scoped to investment companies and to equity securities only, is effective for annual periods beginning after December 15,…

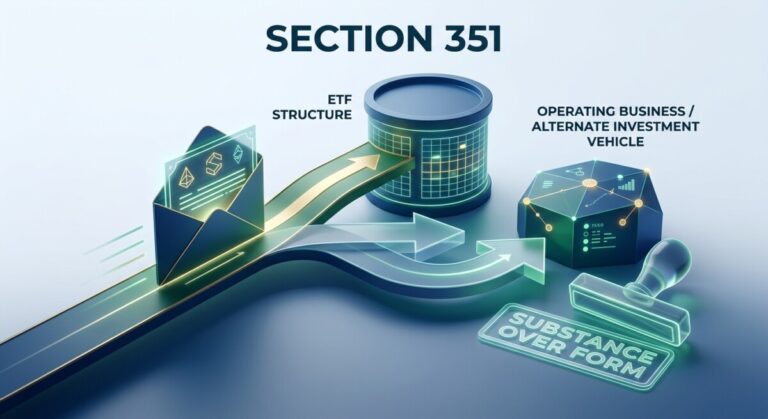
Section 351 ETF conversion recharacterized: substance over form under IRS Rev. Rul. 2026-20
|

Section 351 ETF conversion: Rev. Rul. 2026-20

Does the Section 351 ETF conversion still work after Rev. Rul. 2026-20? Not the way it has been sold. The IRS now treats a planned transfer of securities to a new ETF followed by an authorized-participant redemption of those same securities as a single taxable exchange, not a tax-free diversification. The Section 351 ETF conversion…

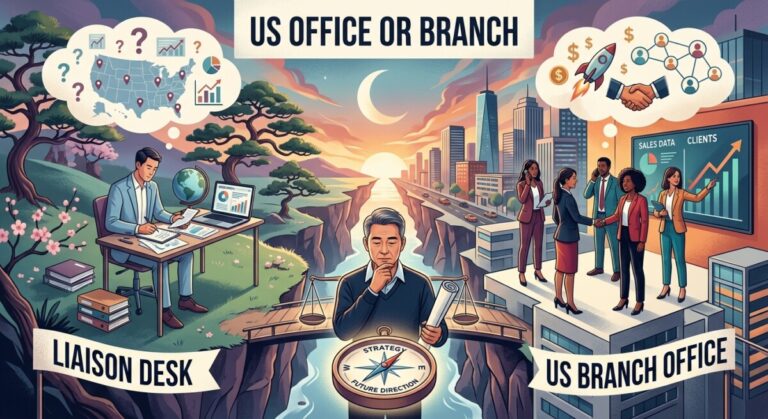
Side-by-side depiction of a US representative office and a US branch, contrasting the two US presence options a Korean parent company must choose between.
|

US representative office vs branch: what should a Korean parent set up?

If my Korean parent only wants to watch the US market, is a representative office enough — or do I already need a branch? A US representative office that limits itself to market research, information gathering, and liaison work typically falls outside the US “trade or business” definition under IRC §864(b), so it files no…