Influencer tax: a creator's ring light and phone beside receipts and a mileage log
|

Are influencer tax rules different from other tax rules?

Are influencer tax rules any different from regular tax rules? No. The Tax Court’s first ruling involving a social-media creator, Sami v. Commissioner, applied the same ordinary-and-necessary business expense standard used for every other business. What actually decides an influencer tax audit is substantiation, business purpose, and whether the activity is a real trade or…
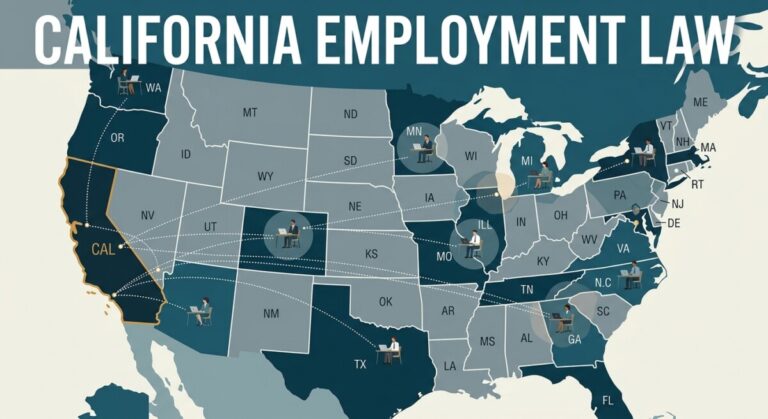
California employment law and the reach of state statutes over remote workers based out of state

Does California employment law reach remote workers?

Does California employment law reach remote workers based outside the state? Not automatically. In Saberin v. Alation, the California Court of Appeal held that California employment law did not apply where the employee lived in Utah, worked in Utah, and the termination was decided by executives physically located in Illinois — even though the employer…

Car loan interest deduction: OBBBA's new above-the-line write-off for personal auto loans

Car loan interest deduction: what do IRS final regs say?

Can you deduct car loan interest in 2025? Yes, up to $10,000 per return per year, for tax years 2025 through 2028. The car loan interest deduction under OBBBA §70203 covers loans incurred after December 31, 2024 that are secured by a first lien on a U.S.-assembled passenger vehicle you bought for personal use. Final…

Year-end tax planning: a Q4 calendar and retirement statement on a high earner's desk
|

Year-end tax planning: what should high earners do in Q4?

Which year-end tax planning moves actually shift a high earner’s 2026 tax bill? The ones the Internal Revenue Code closes at midnight on December 31 — retirement contributions coded to a payroll cycle, wash-sale-safe loss harvests, exercised stock options, direct-to-charity IRA distributions, and completed annual-exclusion gifts. Year-end tax planning for high earners is less about…

ICE Endex Section 1256: Netherlands futures exchange now qualified for U.S. mark-to-market
|

Are ICE Endex futures Section 1256 contracts? (2026)

Are ICE Endex futures Section 1256 contracts now? Yes — for contracts entered into on or after September 1, 2026. In Rev. Rul. 2026-16, the IRS determined that ICE Endex, a Netherlands regulated exchange, is a qualified board or exchange under § 1256(g)(7)(C), so its futures and futures options get mark-to-market and 60/40 capital-gain treatment…

OBBBA method change: IRS Rev. Proc. 2026-32 covers § 174 R&E and § 460(e) residential construction
|

OBBBA method change under IRS Rev. Proc. 2026-32?

Does the IRS finally have an automatic-consent path for OBBBA R&E and residential construction changes? Yes. IRS Rev. Proc. 2026-32 opens the automatic OBBBA method change for § 174, § 174A, and § 460(e), waives the usual eligibility bars through 2027, and gives one transition window that closes November 15, 2026. On September 4, 2026,…

Private school tax exempt status under IRS proposed regulations — a private school campus and regulatory review

Private school tax exempt status: what changes in 2026?

Will private schools lose their tax-exempt status for racial-preference policies? Under Treasury and IRS proposed regulations issued September 3, 2026, a private school that discriminates on the basis of race, color, or national or ethnic origin would not qualify for §501(c)(3) recognition. This post explains what changes to private school tax exempt status, when, and…

QSBS: founder's C-corporation stock reshaped in a tax-free recap without breaking Section 1202
|

How to keep QSBS treatment through a recap (2026)

How do founders keep QSBS treatment through a recapitalization? A Section 368(a)(1)(E) tax-free recap can preserve QSBS under Section 1202(h)(4)(A), but only if the reorganization requirements are met, the aggregate gross assets threshold is respected, and Section 305 does not turn the recap into a taxable deemed distribution. Many of our founder clients organize as…

SBA size standards overhaul: 338 categories, employment-based default, comments due September 21, 2026
|

How do new SBA size standards change small business status?

Are the SBA size standards really changing before September 21, 2026? Yes — SBA has proposed the biggest rewrite of sba size standards since it adopted NAICS in 2000. The proposal collapses roughly 1,000 standards to 338, defaults to employment-based measures, and adjusts receipts standards for productivity growth. Comments close September 21, 2026, and the…

California tourist tax refund: shopping bags, a receipt, and a passport on a Los Angeles counter
|

California tourist tax refund: does it exist? (2026)

Is there a California tourist tax refund for visitors shopping during BTS Week? No. California does not refund sales tax to foreign visitors, and there is no federal program either. A California tourist tax refund does not exist because U.S. sales tax is a single-stage state and local tax, not a value-added tax. The 9.75…

Small business owner using the IRS Business Tax Account on a laptop to view notices, download CP575, and manage payments
|

Who can use the IRS Business Tax Account (2026)?

Who can now use the IRS Business Tax Account? As of 2026, the IRS Business Tax Account covers partnerships, tax-exempt organizations, Indian tribal governments, and federal, state, and local governments, alongside the sole proprietors and corporations who had access before. Inside the account, entities can view digital notices, download CP575 EIN verification, and pay against…

Pop-up shop sales tax: a temporary merch booth near SoFi Stadium with a tablet point-of-sale
|

Pop-up shop sales tax in California: what do vendors owe?

What are the pop-up shop sales tax rules for a temporary vendor in California? Get a free CDTFA temporary seller’s permit before the first sale, charge the rate of the city where the customer takes the goods (Inglewood is 10.25 percent, Los Angeles 9.75 percent), pay use tax on giveaways, and file by the date…

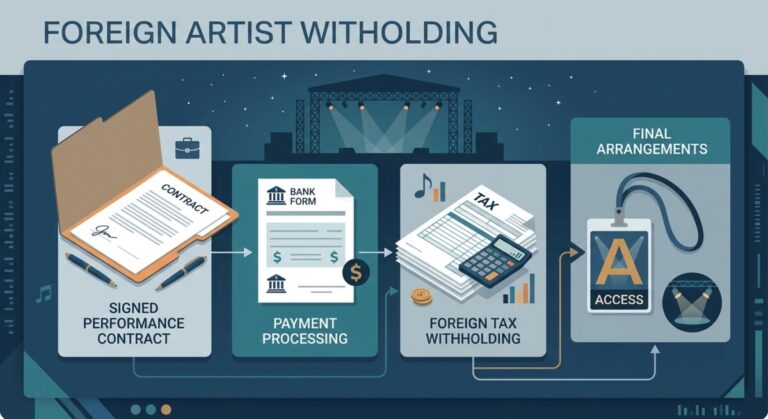
Foreign artist withholding: a California promoter's contract and wire form before paying an international act
|

Foreign artist withholding in California: who is liable?

Who handles foreign artist withholding when a California venue books an international act? You do. The payer is the withholding agent for 30 percent federal tax on the gross fee and 7 percent California tax on payments over $1,500. Foreign artist withholding drops only when the artist hands you an IRS Central Withholding Agreement letter,…

FTB overcollection versus overpayment under California FTB Legal Ruling 2026-02
|

FTB overcollection vs. overpayment: SOL changes

Can FTB return money it collected years ago? Sometimes, yes. FTB Legal Ruling 2026-02 (issued August 21, 2026) draws a sharp line between an overpayment (subject to the four-year refund statute) and an FTB overcollection (excess taken by mechanical or clerical error during involuntary collection). Overcollections can be returned even after the SOL — but…

FASB effective dates 2026: the ASUs first effective for calendar-year entities
|

FASB effective dates 2026: which ASUs kick in this year?

Which FASB standards take effect in 2026? The largest calendar-year first-effective ASUs are 2023-09 (income tax disclosures, private companies), 2024-04 (induced conversions of convertible debt, all entities), 2025-05 (AR credit losses practical expedient, PCC), and 2024-01 (profits interest awards, private companies). This post is a plain-English guide to the FASB effective dates 2026 that will…

FIRPTA 2026 changes: DC REIT lookthrough rule repealed and Sec. 892 rules finalized
|

What changed for FIRPTA 2026 and foreign investors?

What changed for FIRPTA in 2026 for foreign investors in U.S. real estate? Two Treasury releases moved the ground under cross-border deals — the 2025 proposed regulations on domestically controlled REITs repeal the lookthrough rule for U.S. corporate shareholders, and the 2025 final FIRPTA-adjacent Sec. 892 regulations give foreign governments a workable path to hold…

BTS Week sales spike: a Los Angeles restaurant line near SoFi Stadium and the bookkeeping that follows
|

BTS Week sales spike: what changes in your books this month?

What does a BTS Week sales spike change in your books? Four things: your CDTFA sales tax filing frequency can change, tip records must stay clean for the new tip deduction, temporary staff earn daily overtime under California law, and your September 15 estimated tax should stay on the safe harbor. A BTS Week sales…

IRA fraud: a retirement account drained by a phone scam and the tax bill that follows
|

Is IRA fraud still taxable? What does the IRS waive in 2026?

Is IRA fraud still taxable if the money was stolen? Usually, yes. A withdrawal you were tricked into making is still a distribution to you, so the amount is taxable and a Form 1099-R follows. The IRS has waived the 60-day rollover deadline for IRA fraud victims in several private letter rulings, but the waiver…

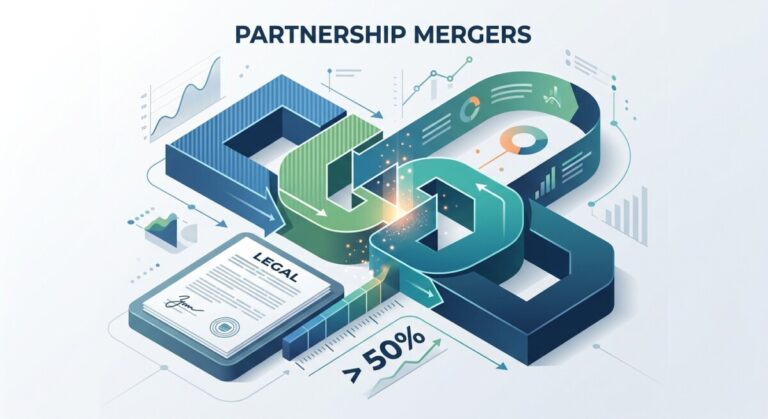
Partnership merger tax rules under Sec. 708 showing two partnerships combining under the more-than-50% continuation test
|

How Partnership Merger Tax Rules Work Under Sec. 708

How do partnership merger tax rules work under Sec. 708(b)(2)(A)? A resulting partnership is a continuation of any merging partnership whose partners own more than 50% of the capital and profits of the resulting partnership; other merging partnerships terminate. Consideration mixing cash and interests triggers disguised-sale analysis, and the merger cash-out rule at Regs. Sec….

Trust charitable deduction reporting narrowed under IRS proposed regs — Form 1041-A being set aside while a K-1 flows into a trust ledger

Trust charitable deduction — still Form 1041-A?

Does my trust’s charitable deduction still require a Form 1041-A? Two carve-outs would say no. The IRS’s August 2026 proposed regulations (REG-109082-25) would remove Form 1041-A for a trust charitable deduction that is only a distributive share from a pass-through entity, and confirm that a split-interest trust filing Form 5227 does not also file Form…

SEC Regulation Crypto Assets proposal and FASB cash-equivalents proposal for digital assets released the same day in August 2026
|

What is SEC Regulation Crypto Assets & How It Works

What is SEC Regulation Crypto Assets, and does it change how I raise capital or report digital assets? The SEC proposed a new exempt-offering framework for crypto asset investment contracts on August 12, 2026, and FASB the same day proposed clarifying when certain digital assets — including some stablecoins — count as cash equivalents. Both…

New IRS refundable credit rules applying PRWORA to EITC, Child Tax Credit, American Opportunity Credit, and Adoption Credit
|

Who Qualifies Under the New IRS Refundable Credit Rules?

Who qualifies under the new IRS refundable credit rules? Treasury and the IRS proposed on August 19, 2026 to treat the refunded portion of the EITC, Child Tax Credit, American Opportunity Credit, and Adoption Credit as a federal public benefit under PRWORA — available only to U.S. citizens, U.S. nationals, and qualified aliens. For families,…

Concept image of a carbon capture facility and underground storage layers with an IRS notice overlay — 45Q safe harbor
|

45Q Safe Harbor: What Notice 2026-50 Changes for CCUS

Can I still claim the §45Q credit if EPA drops subpart RR reporting? Yes — the IRS just answered that question. Under the new 45Q safe harbor in Notice 2026-50, taxpayers who cannot rely on subpart RR of the Greenhouse Gas Reporting Program can still document secure geological storage for the §45Q credit, and the…

Global tax changes in 2026 linking cross-border filing deadlines and registration portals to a single company
|

Which Global Tax Changes in 2026 Affect My U.S. Business?

Which global tax changes in 2026 affect my U.S. business? If you have a foreign parent, a foreign subsidiary or cross-border intragroup payments, four do: proposed U.S. foreign tax credit rules with a September 17 comment deadline, Pillar Two registration deadlines arriving jurisdiction by jurisdiction, spreading e-invoicing mandates, and sharply increased transfer pricing scrutiny. International…