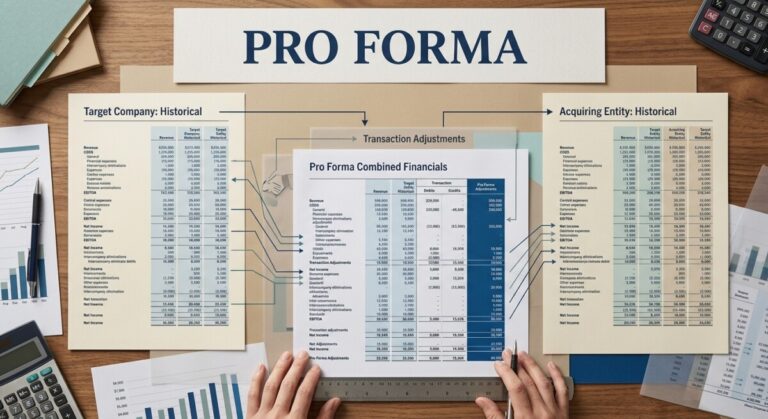
SEC pro forma financial information under Regulation S-X Article 11
|

What is pro forma financial information? SEC Article 11

When does the SEC require pro forma financial information? Regulation S-X Article 11 requires it for significant business acquisitions, dispositions, spinoffs, and other transactions where the illustration would be material to investors. The 2020 amendments reorganized pro forma financial information around three adjustment categories, and the columnar totals now stop at transaction accounting and autonomous…
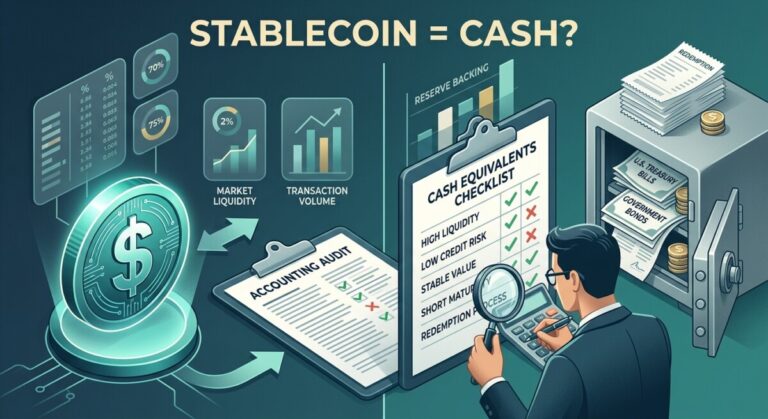
Stablecoin cash equivalents: FASB's three-attribute test under Topic 230
|

Can stablecoin cash equivalents pass FASB’s test?

Can a stablecoin be a cash equivalent under US GAAP? FASB’s August 2026 proposed Accounting Standards Update under Topic 230 says yes — but only when three attributes line up. The Master Glossary definition does not change. Stablecoin cash equivalents and a new disclosure of the significant components of cash equivalents are now on the…

|

How should a Korean company choose a US CPA firm? (And what to bring to the first consultation)

What should a Korean company check before choosing a US CPA firm? Check five things: which state licenses the CPA and whether the license is active, whether the firm also handles the Korea-side work (overseas direct investment reporting and the parent’s reporting package), whether the same team carries the work from setup into monthly books…

AI software costs: capitalizing versus expensing under US GAAP (ASC 350-40)
|

Can you capitalize AI software costs under US GAAP?

Can you capitalize AI software costs under US GAAP? Sometimes. US GAAP has no AI-specific rule — the existing internal-use software guidance in ASC 350-40 still controls. If AI software costs are project-specific, measurable, and incurred after the application development stage begins, they may be capitalized. General-purpose AI subscriptions are expensed. Every quarter our Los…

Investment company fair value: a locked equity security discounted on a fund's NAV ledger
|

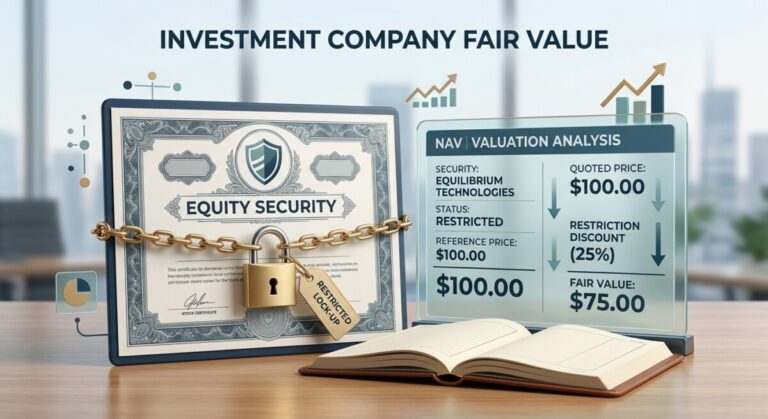
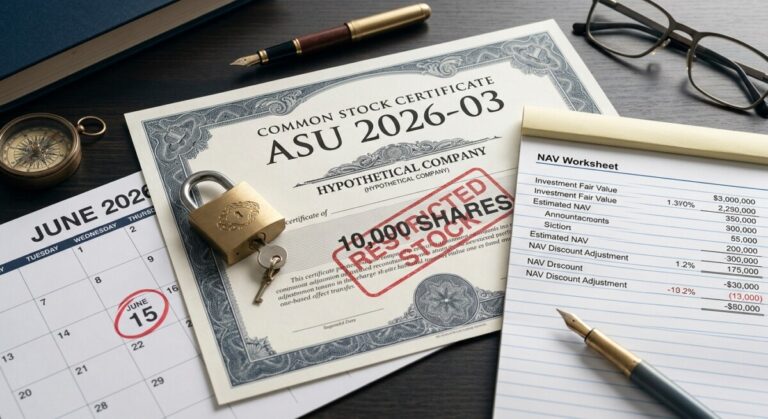
ASU 2026-03: investment company fair value guide

How does ASU 2026-03 change investment company fair value? It requires an investment company to apply a discount when a contractual sale restriction prevents it from selling an equity security on the measurement date. The amendment is scoped to investment companies and to equity securities only, is effective for annual periods beginning after December 15,…

US subsidiary finance staff building a monthly Korean IFRS reporting package for its parent company.
|

How does a US subsidiary prepare a Korean IFRS reporting package for its parent?

What is a Korean IFRS reporting package, and why does your parent need one every month? A Korean IFRS reporting package — often written K-IFRS reporting package — is the standardized monthly submission a US subsidiary sends its Korean parent so the parent can consolidate the subsidiary’s results under Korean IFRS (K-IFRS). It contains a…

IFRS 15 vs ASC 606 — where revenue recognition still diverges between IFRS and US GAAP
|

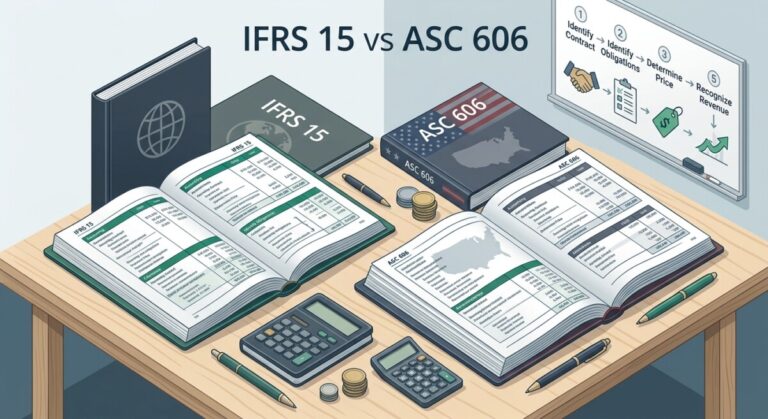
IFRS 15 vs ASC 606: Where does revenue still diverge?

Are IFRS 15 and ASC 606 still converged? Substantially, yes — but the details still shift the timing and amount of revenue. This IFRS 15 vs ASC 606 guide walks through ten differences that change what dual reporters book and disclose, grounded in the standards themselves rather than firm commentary. The joint issuance of IFRS…

California cybersecurity audit: CCPA Article 9 rule for covered businesses
|

California cybersecurity audit: does the CCPA rule apply?

Does the California cybersecurity audit rule apply to my business? A California business is in scope if it either earned at least 50% of its revenue from selling or sharing personal information, or exceeded roughly $26.625 million in annual gross revenue and processed the personal information of at least 250,000 California consumers or households (or…

FASB ASU 2026-03: contractual sale restrictions and fund NAV
|

Does ASU 2026-03 change fair value sale restrictions?

Does ASU 2026-03 change fair value sale restrictions for investment funds? Yes — but only for investment companies within the scope of Topic 946. From adoption, those funds must incorporate a discount for contractual sale restrictions when measuring the fair value of an equity security, and disclose the size of that discount. Effective for annual…

FASB effective dates 2026: the ASUs first effective for calendar-year entities
|

FASB effective dates 2026: which ASUs kick in this year?

Which FASB standards take effect in 2026? The largest calendar-year first-effective ASUs are 2023-09 (income tax disclosures, private companies), 2024-04 (induced conversions of convertible debt, all entities), 2025-05 (AR credit losses practical expedient, PCC), and 2024-01 (profits interest awards, private companies). This post is a plain-English guide to the FASB effective dates 2026 that will…

SEC Regulation Crypto Assets proposal and FASB cash-equivalents proposal for digital assets released the same day in August 2026
|

What is SEC Regulation Crypto Assets & How It Works

What is SEC Regulation Crypto Assets, and does it change how I raise capital or report digital assets? The SEC proposed a new exempt-offering framework for crypto asset investment contracts on August 12, 2026, and FASB the same day proposed clarifying when certain digital assets — including some stablecoins — count as cash equivalents. Both…

Illustration of OBBBA nonprofit tax rules — Capitol, donation box, university facade with IRC section tokens
|

OBBBA nonprofit tax: What changed for your 501(c)(3)?

What did the OBBBA actually change for my nonprofit? Quite a lot. The OBBBA nonprofit tax rules created a new charitable deduction for non-itemizers, added floors that shrink deductions for high-income and corporate donors, expanded the §4960 excise on high pay, and set a tiered endowment tax for large private colleges. The One Big Beautiful…

Illustration of new IFRS standards 2026 — a reporting binder with IAS 21, IFRS 9, IFRS 18 tabs beside a 30 June 2026 calendar
|

New IFRS Standards 2026: Effective at 30 June 2026

Which new IFRS standards must I apply for a 30 June 2026 reporting date? Several amendments are mandatory now — including the IAS 21 lack-of-exchangeability rules, the IFRS 9 & IFRS 7 classification and measurement amendments, and Annual Improvements Volume 11 — while IFRS 18, IFRS 19, and IFRS 20 remain optional until 2027. Applying…

California minimum wage 2026 — healthcare, hospitality, and payroll compliance snapshot for California employers
|

California Minimum Wage 2026: What Changed on July 1

What changed for California employers on July 1, 2026? A stack of rules landed on the same day. California minimum wage 2026 updates cover healthcare workers, San Diego hospitality staff, and more than a dozen city and county rates — plus new California Privacy Protection Agency (CPPA) rules that will bite by 2027. If you…

Illustration of IAS 28 update — an open IFRS standard on a desk with a magnifying glass and a rising fair value chart
|

IAS 28 Fair Value Option: IASB’s 2026 Amendments Explained

Who can still elect the IAS 28 fair value option after the IASB’s 2026 amendments? The updated IAS 28 fair value option extends the FVTPL election beyond classic investment funds to any entity whose main business is investing in associates, joint ventures, unconsolidated subsidiaries, cash and cash equivalents, or other independently-returning assets — aligned to…

IAS 28 fair value option — balance scale weighing equity method against fair value under IFRS
|

IAS 28 Fair Value Option: 2026 IASB Amendment Guide

Who can measure associates and joint ventures at fair value under IFRS? The IAS 28 fair value option is an exemption from the equity method — and on 26 June 2026 the IASB issued narrow amendments that finally pin down which entities qualify, using the ‘specified main business activities’ concept from IFRS 18. If your…

Illustration of FASB's proposed hedge accounting update to Topic 815 — interest rate and currency risk balancing on a scale with a line chart
|

FASB Proposed Hedge Accounting Update (Topic 815) 2026

What is the FASB changing about hedge accounting in 2026? On June 17, 2026, the FASB issued a proposed hedge accounting update to Topic 815 with three targeted changes: hedging interest rate risk on held-to-maturity securities, using any tenor of SOFR, and expanding eligible net investment hedging instruments. Comments are due August 17, 2026. If…

Illustration of FASB ASU 2023-09 new income tax disclosures under Topic 740 — a financial statement footnote with a tax table and a globe showing income taxes paid by jurisdiction
|

ASU 2023-09: New Income Tax Disclosures (Topic 740)

Do private companies have to change their income tax disclosures? Yes — in part. FASB ASU 2023-09, Income Taxes (Topic 740): Improvements to Income Tax Disclosures, requires all entities to disclose income taxes paid (net of refunds) by federal, state, and foreign jurisdiction — and by any individual jurisdiction equal to or greater than 5%…

Illustration of the SEC's 2026 proposed filer status overhaul — two categories (large accelerated and nonaccelerated filers), a $2 billion public float threshold, and an ICFR auditor-attestation exemption
|

SEC Filer Status Overhaul 2026: LAF, NAF & $2B Threshold

What is the SEC’s proposed filer status overhaul? On May 19, 2026, the SEC proposed collapsing public-company reporting into two categories — large accelerated filers (LAFs) and nonaccelerated filers (NAFs) — raising the LAF public float threshold to $2 billion and exempting NAFs from ICFR auditor attestation. If you advise public companies, the SEC filer…

Illustration of FASB ASU 2025-06 modernizing internal-use software capitalization under Subtopic 350-40 — replacing project stages with a probable-to-complete threshold for agile development
|

FASB ASU 2025-06: Internal-Use Software Cost Rules Modernized

How does FASB ASU 2025-06 change accounting for internal-use software? The FASB issued ASU 2025-06, Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40): Targeted Improvements, to modernize software cost guidance written in 1998 for today’s agile development. The biggest change: it ELIMINATES the old project-stage (waterfall) model for deciding when to start capitalizing costs. Instead, capitalization begins…

Illustration of a June 2026 international tax roundup — OECD Pillar Two global minimum tax, EU Court of Justice rulings, and country-level corporate rate changes
|

International Tax Roundup June 2026: Pillar Two, EU, Rates

What were the key international tax developments in early-to-mid June 2026? The OECD pushed forward on the global minimum tax (Pillar Two) — releasing practical fixes to the GloBE Information Return (GIR) XML schema for first filings, an updated 2026 consolidated commentary, and new transfer-pricing guidance on intragroup services. In the EU, the Court of…

Illustration of a June 2026 multistate tax roundup — California apportionment at the Supreme Court, New York's enacted budget, and the BATSA federal nexus bill
|

Multistate Tax Roundup June 2026: CA, NY, Nexus & BATSA

What changed in state and local tax in early-to-mid June 2026? A busy stretch: the U.S. Supreme Court declined to hear Florida’s challenge to California’s single-sales-factor apportionment; New York enacted a budget that extends its top corporate rate, decouples from some OBBBA provisions, and adds a “pied-à-terre” surcharge; Texas adopted cost-of-goods-sold rule changes for franchise…

Illustration of IFRS 20 Regulatory Assets and Regulatory Liabilities for rate-regulated utilities — differences in timing, effective 2029, compared with U.S. GAAP ASC 980
|

IFRS 20: Regulatory Assets & Liabilities for Utilities

What is IFRS 20, and who does it affect? The International Accounting Standards Board (IASB) issued IFRS 20, Regulatory Assets and Regulatory Liabilities — a new IFRS Accounting Standard for companies subject to a specific type of rate regulation (utilities that supply electricity, water, and gas, where a regulator controls how much they can charge…

Illustration of FASB ASU 2026-02 and new ASC 818 — accounting for environmental credits like carbon offsets, RECs, and allowances and environmental credit obligations
|

FASB ASU 2026-02: Environmental Credits Accounting (ASC 818)

How do you account for carbon credits and emission allowances under U.S. GAAP now? On May 19, 2026, the FASB issued Accounting Standards Update (ASU) 2026-02, creating a brand-new Codification Topic — ASC 818, Environmental Credits and Environmental Credit Obligations. Until now, U.S. GAAP had no specific guidance for carbon offsets, renewable energy certificates (RECs),…

Illustration of SEC reporting for business acquisitions under Regulation S-X Rule 3-05 — significance tests, required acquiree financial statement periods, pro forma, and the Form 8-K deadline
|

SEC Business Acquisition Reporting: Rule 3-05 Explained

When does an SEC registrant have to file financial statements for a business it acquired? Under SEC Regulation S-X Rule 3-05, a registrant (including a company doing an IPO) must file separate pre-acquisition financial statements of a “significant” acquired or to-be-acquired business — with a parallel rule (3-14) for significant real estate operations. Significance is…

Illustration of summer activities that affect your tax return — day camp, marriage, gig work, business travel, and selling digital assets
|

5 Summer Activities That Affect Your Next Tax Return

How can summer activities affect your next tax return? Several common summer events have tax consequences worth handling now, per the IRS: (1) summer DAY CAMP costs may count toward the Child and Dependent Care Credit; (2) getting MARRIED means reporting any name change to the Social Security Administration and any address change to USPS,…