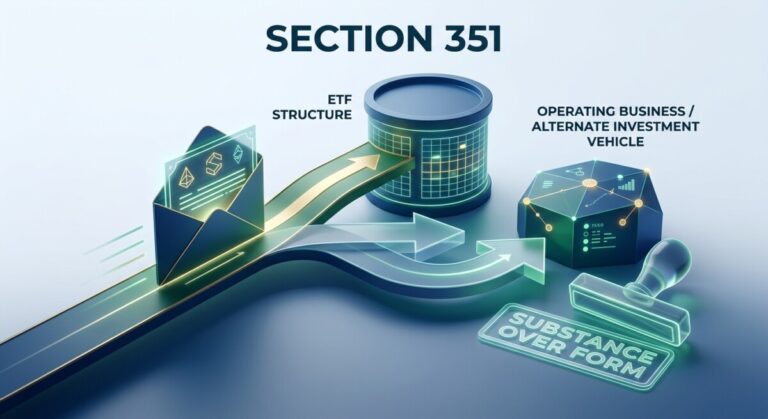
Section 351 ETF conversion recharacterized: substance over form under IRS Rev. Rul. 2026-20
|

Section 351 ETF conversion: Rev. Rul. 2026-20

Does the Section 351 ETF conversion still work after Rev. Rul. 2026-20? Not the way it has been sold. The IRS now treats a planned transfer of securities to a new ETF followed by an authorized-participant redemption of those same securities as a single taxable exchange, not a tax-free diversification. The Section 351 ETF conversion…

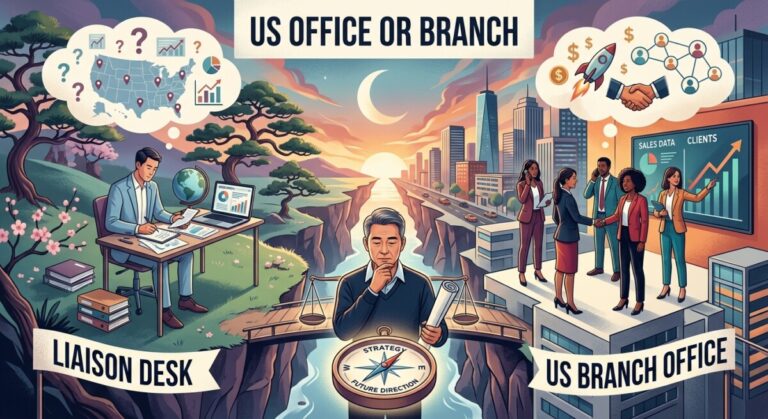
Side-by-side depiction of a US representative office and a US branch, contrasting the two US presence options a Korean parent company must choose between.
|

US representative office vs branch: what should a Korean parent set up?

If my Korean parent only wants to watch the US market, is a representative office enough — or do I already need a branch? A US representative office that limits itself to market research, information gathering, and liaison work typically falls outside the US “trade or business” definition under IRC §864(b), so it files no…

HR 9500 would restore a federal tax deduction for individual fraud and scam victims
|

What is the fraud victims tax deduction? HR 9500

Will individual fraud victims be able to deduct their losses again? On September 16, 2026, the House passed HR 9500 by a 408–17 vote. If the Senate agrees and the President signs, the fraud victims tax deduction is restored outside federally declared disasters, the retirement-account early-withdrawal penalty is waived in scam cases, and victims gain…

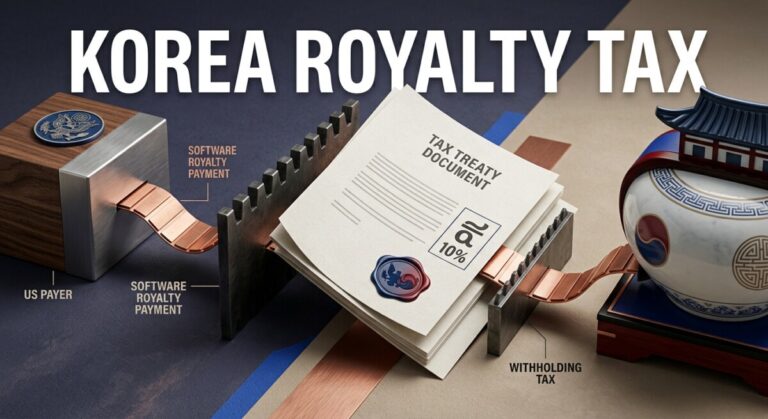
US-Korea tax treaty royalty withholding — illustration of cross-border software royalty payment and reduced treaty rate.
|

What is the US-Korea tax treaty royalty rate, and how do I claim it?

Does the US-Korea tax treaty actually reduce the 30% default withholding on a software royalty paid to a Korean licensor? Yes — a US payer must generally withhold 30% on a US-source royalty, but the Korea tax treaty royalty article can cut the rate to 10% or 15% depending on the royalty type, provided the…

Clean fuel credit under section 45Z: IRS Notice 2026-53 and the OBBBA amendments
|

Does the clean fuel credit still cover my fuel in 2026?

How does the clean fuel credit work after the OBBBA? The clean fuel credit under § 45Z still rewards low-emissions transportation fuel produced in the United States, but IRS Notice 2026-53 reshapes it for 2026. ILUC emissions are out. Non-North American feedstocks are out. Animal manure gets its own emissions rate. Here is what to…

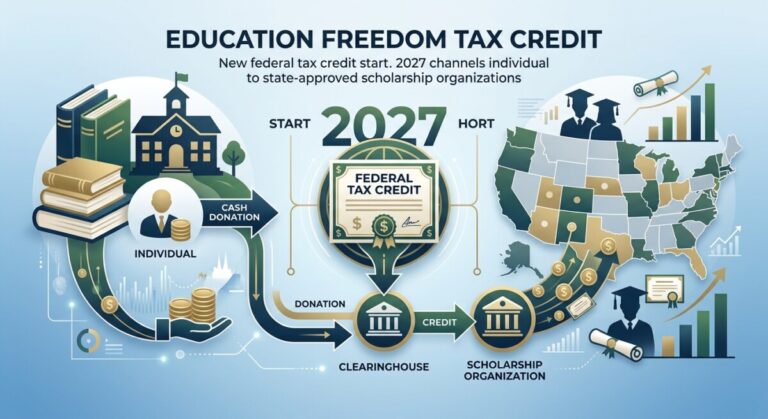
Education Freedom Tax Credit: a new federal $1,700 credit for cash gifts to state-listed Scholarship Granting Organizations starting January 1, 2027
|

How does the Education Freedom Tax Credit work in 2027?

What is the Education Freedom Tax Credit, and how does it work? The Education Freedom Tax Credit is a new federal nonrefundable credit under Internal Revenue Code Section 25F, worth up to $1,700 for individual cash contributions to state-listed Scholarship Granting Organizations. It begins January 1, 2027 and only applies in states that have elected…

Kwong tax refund: a federal appellate courtroom weighing a COVID-era postponement claim
|

Kwong tax refund: does the COVID postponement apply?

What is the Kwong tax refund case, and does it extend the two-year deadline for COVID-era refund claims? The U.S. Court of Federal Claims held that 26 U.S.C. § 7508A(d) automatically postponed the § 6532(a)(1) refund-suit deadline for the entire COVID-19 disaster period. The government has appealed to the Federal Circuit and argues the postponement…

Business traveler and the 2026–2027 IRS per diem rates ($329 high-cost / $230 other CONUS)
|

What are the new IRS per diem rates for 2026–2027?

What are the new IRS per diem rates for 2026–2027? Notice 2026-60 sets the high-low per diem rates at $329 for high-cost localities and $230 elsewhere in CONUS, effective October 1, 2026. Transportation-industry M&IE is $80 CONUS and $86 OCONUS, and the incidental-only rate stays at $5 per day. Every October, a wave of expense-policy…

Editorial illustration of a globe with pins for an international tax update

International tax update — Sept 27, 2026

This international tax update covers three moves that reach owners of US businesses with any cross-border footprint. Australia has released an exposure draft that would reshape its Research and Development Tax Incentive from mid-2028; Hong Kong has unveiled tax-related measures in the 2026 Policy Address; and the OECD has published its 2026 report on tax…

Editorial illustration of a US Capitol dome silhouette next to a stylized federal tax document

Federal tax update: TAS Act, OZ, and OBBBA

This federal tax update covers three developments that reach small and mid-sized business owners directly. Congress moved a bipartisan taxpayer service package out of committee, Treasury opened a comment window on the renewed opportunity zone rules under the OBBBA, and the Joint Committee on Taxation corrected four points in its own OBBBA technical explanation —…

Livestock drought relief: dry pasture and a small herd, illustrating IRS section 1033 replacement-period extension for drought-sold livestock
|

Livestock drought relief: did IRS extend the 1033 period?

Do I get more time to replace drought-sold livestock under the 2026 IRS notice? If the county where you sold, or any contiguous county, is on the Notice 2026-54 Appendix, yes. The IRS treats the 12-month period ending August 31, 2026 as not a drought-free year, so the section 1033(e) four-year replacement period is extended…

Illustration of a California business owner reviewing Franchise Tax Board tax updates and deadlines at an office desk.

California FTB Update: LLC Fees & Tax Credits

California’s Franchise Tax Board wrapped up summer with two Tax News issues carrying real, dollars-and-cents implications for business owners. New budget trailer bills rewrote several business credit and minimum-tax rules, a fresh application window opened for the $350 million California Competes Tax Credit, and FTB locked in new interest rates that take effect January 1,…

World map with tax and currency icons representing this week's international tax update for cross-border businesses

International Tax Update: 5 Cross-Border Changes

This week’s international tax update tracks five developments that reach across borders and land right back on US balance sheets: a finalized Australian ruling on cross-border software royalty withholding, tighter global rules for digital-platform sellers and intragroup service pricing, new US Treasury rules for foreign-subsidiary income inclusions, and an extended Thai VAT rate. None of…

Map of the United States highlighting states with state tax law changes for business owners

State Tax Update: CA SaaS Tax & More (Sept 2026)

State and local tax rules keep shifting for businesses that sell across state lines, and this week brings several changes worth watching. California is preparing to tax software and digital products for the first time, Philadelphia is changing how it sources local sales tax, and a landmark court ruling in Maryland could open the door…

Illustration representing federal tax updates for business owners, including tax documents, a calculator, and trade and digital currency icons

Federal Tax Update: What US Business Owners Need to Know

Congress and federal agencies moved on several fronts this week that land directly on a business owner’s desk, not just a tax preparer’s. The IRS updated how businesses account for research costs, Treasury finalized a new rule on beneficial ownership reporting, and the administration escalated tariffs on Canadian goods ranging from auto parts to dairy…

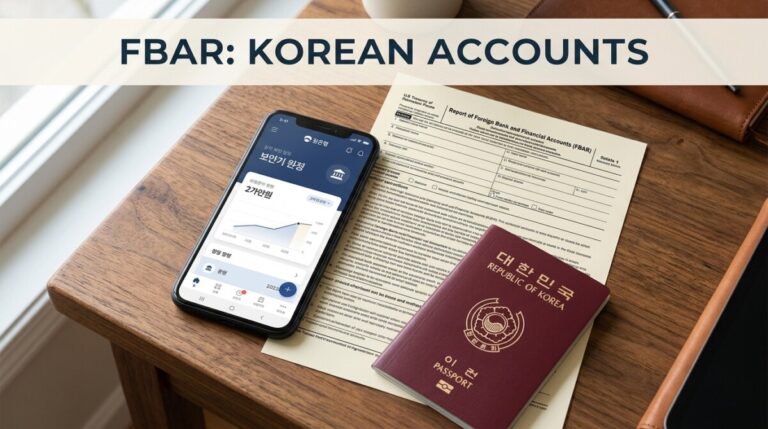
A Korean phone banking screen beside a US Treasury form on a wooden desk, showing FBAR reporting for Korean-American families.

Do I need to report my Korean bank accounts on FBAR? (Toss & KakaoBank)

Do my Korean bank accounts really need to be reported on FBAR? Yes — any U.S. person whose foreign financial accounts (including Toss, KakaoBank, KEB Hana, Kookmin, or a Korean brokerage) together exceed $10,000 at any point during the calendar year must file FinCEN Form 114. The $10,000 test is measured across all accounts combined,…

California digital products sales tax: SaaS and prewritten software become taxable January 1, 2027
|

Does California’s digital products sales tax apply to SaaS?

Does California’s digital products sales tax apply to my software business? Starting January 1, 2027, prewritten software — including Software-as-a-Service and remote-access licenses — is a taxable digital product under California’s new digital products sales tax rule enacted by Senate Bill 122. Custom software and several digital-media categories stay outside the rule. A short email…

IRS CAP program 2027: real-time corporate tax issue resolution with an Oct. 30 deadline
|

What is the IRS CAP program, and who qualifies for 2027?

Should our corporation apply to the IRS CAP program for 2027? The IRS opened the 2027 application window in September 2026 with an Oct. 30, 2026 deadline. The IRS CAP program resolves material tax issues in real time before the return is filed — but only for corporations that clear a strict eligibility bar. If…

Influencer tax: a creator's ring light and phone beside receipts and a mileage log
|

Are influencer tax rules different from other tax rules?

Are influencer tax rules any different from regular tax rules? No. The Tax Court’s first ruling involving a social-media creator, Sami v. Commissioner, applied the same ordinary-and-necessary business expense standard used for every other business. What actually decides an influencer tax audit is substantiation, business purpose, and whether the activity is a real trade or…

Car loan interest deduction: OBBBA's new above-the-line write-off for personal auto loans

Car loan interest deduction: what do IRS final regs say?

Can you deduct car loan interest in 2025? Yes, up to $10,000 per return per year, for tax years 2025 through 2028. The car loan interest deduction under OBBBA §70203 covers loans incurred after December 31, 2024 that are secured by a first lien on a U.S.-assembled passenger vehicle you bought for personal use. Final…

Year-end tax planning: a Q4 calendar and retirement statement on a high earner's desk
|

Year-end tax planning: what should high earners do in Q4?

Which year-end tax planning moves actually shift a high earner’s 2026 tax bill? The ones the Internal Revenue Code closes at midnight on December 31 — retirement contributions coded to a payroll cycle, wash-sale-safe loss harvests, exercised stock options, direct-to-charity IRA distributions, and completed annual-exclusion gifts. Year-end tax planning for high earners is less about…

ICE Endex Section 1256: Netherlands futures exchange now qualified for U.S. mark-to-market
|

Are ICE Endex futures Section 1256 contracts? (2026)

Are ICE Endex futures Section 1256 contracts now? Yes — for contracts entered into on or after September 1, 2026. In Rev. Rul. 2026-16, the IRS determined that ICE Endex, a Netherlands regulated exchange, is a qualified board or exchange under § 1256(g)(7)(C), so its futures and futures options get mark-to-market and 60/40 capital-gain treatment…

OBBBA method change: IRS Rev. Proc. 2026-32 covers § 174 R&E and § 460(e) residential construction
|

OBBBA method change under IRS Rev. Proc. 2026-32?

Does the IRS finally have an automatic-consent path for OBBBA R&E and residential construction changes? Yes. IRS Rev. Proc. 2026-32 opens the automatic OBBBA method change for § 174, § 174A, and § 460(e), waives the usual eligibility bars through 2027, and gives one transition window that closes November 15, 2026. On September 4, 2026,…

Private school tax exempt status under IRS proposed regulations — a private school campus and regulatory review

Private school tax exempt status: what changes in 2026?

Will private schools lose their tax-exempt status for racial-preference policies? Under Treasury and IRS proposed regulations issued September 3, 2026, a private school that discriminates on the basis of race, color, or national or ethnic origin would not qualify for §501(c)(3) recognition. This post explains what changes to private school tax exempt status, when, and…