QSBS: founder's C-corporation stock reshaped in a tax-free recap without breaking Section 1202
|

How to keep QSBS treatment through a recap (2026)

How do founders keep QSBS treatment through a recapitalization? A Section 368(a)(1)(E) tax-free recap can preserve QSBS under Section 1202(h)(4)(A), but only if the reorganization requirements are met, the aggregate gross assets threshold is respected, and Section 305 does not turn the recap into a taxable deemed distribution. Many of our founder clients organize as…
California tourist tax refund: shopping bags, a receipt, and a passport on a Los Angeles counter
|

California tourist tax refund: does it exist? (2026)

Is there a California tourist tax refund for visitors shopping during BTS Week? No. California does not refund sales tax to foreign visitors, and there is no federal program either. A California tourist tax refund does not exist because U.S. sales tax is a single-stage state and local tax, not a value-added tax. The 9.75…

Small business owner using the IRS Business Tax Account on a laptop to view notices, download CP575, and manage payments
|

Who can use the IRS Business Tax Account (2026)?

Who can now use the IRS Business Tax Account? As of 2026, the IRS Business Tax Account covers partnerships, tax-exempt organizations, Indian tribal governments, and federal, state, and local governments, alongside the sole proprietors and corporations who had access before. Inside the account, entities can view digital notices, download CP575 EIN verification, and pay against…

Pop-up shop sales tax: a temporary merch booth near SoFi Stadium with a tablet point-of-sale
|

Pop-up shop sales tax in California: what do vendors owe?

What are the pop-up shop sales tax rules for a temporary vendor in California? Get a free CDTFA temporary seller’s permit before the first sale, charge the rate of the city where the customer takes the goods (Inglewood is 10.25 percent, Los Angeles 9.75 percent), pay use tax on giveaways, and file by the date…

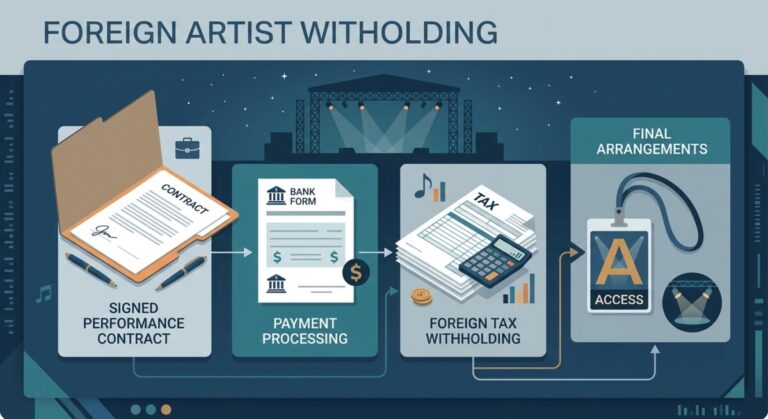
Foreign artist withholding: a California promoter's contract and wire form before paying an international act
|

Foreign artist withholding in California: who is liable?

Who handles foreign artist withholding when a California venue books an international act? You do. The payer is the withholding agent for 30 percent federal tax on the gross fee and 7 percent California tax on payments over $1,500. Foreign artist withholding drops only when the artist hands you an IRS Central Withholding Agreement letter,…

FTB overcollection versus overpayment under California FTB Legal Ruling 2026-02
|

FTB overcollection vs. overpayment: SOL changes

Can FTB return money it collected years ago? Sometimes, yes. FTB Legal Ruling 2026-02 (issued August 21, 2026) draws a sharp line between an overpayment (subject to the four-year refund statute) and an FTB overcollection (excess taken by mechanical or clerical error during involuntary collection). Overcollections can be returned even after the SOL — but…

FIRPTA 2026 changes: DC REIT lookthrough rule repealed and Sec. 892 rules finalized
|

What changed for FIRPTA 2026 and foreign investors?

What changed for FIRPTA in 2026 for foreign investors in U.S. real estate? Two Treasury releases moved the ground under cross-border deals — the 2025 proposed regulations on domestically controlled REITs repeal the lookthrough rule for U.S. corporate shareholders, and the 2025 final FIRPTA-adjacent Sec. 892 regulations give foreign governments a workable path to hold…

BTS Week sales spike: a Los Angeles restaurant line near SoFi Stadium and the bookkeeping that follows
|

BTS Week sales spike: what changes in your books this month?

What does a BTS Week sales spike change in your books? Four things: your CDTFA sales tax filing frequency can change, tip records must stay clean for the new tip deduction, temporary staff earn daily overtime under California law, and your September 15 estimated tax should stay on the safe harbor. A BTS Week sales…

IRA fraud: a retirement account drained by a phone scam and the tax bill that follows
|

Is IRA fraud still taxable? What does the IRS waive in 2026?

Is IRA fraud still taxable if the money was stolen? Usually, yes. A withdrawal you were tricked into making is still a distribution to you, so the amount is taxable and a Form 1099-R follows. The IRS has waived the 60-day rollover deadline for IRA fraud victims in several private letter rulings, but the waiver…

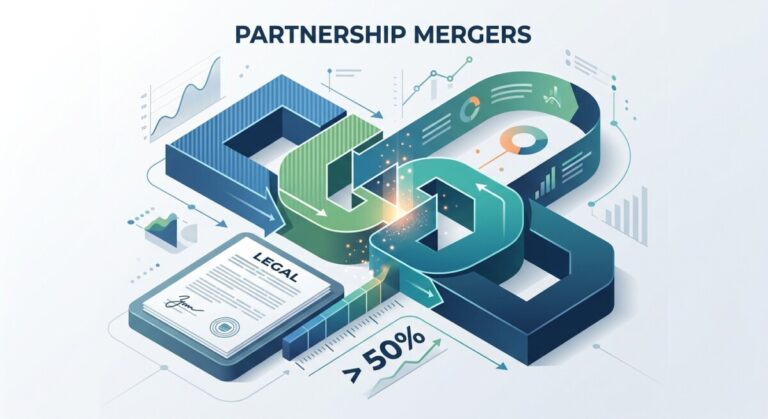
Partnership merger tax rules under Sec. 708 showing two partnerships combining under the more-than-50% continuation test
|

How Partnership Merger Tax Rules Work Under Sec. 708

How do partnership merger tax rules work under Sec. 708(b)(2)(A)? A resulting partnership is a continuation of any merging partnership whose partners own more than 50% of the capital and profits of the resulting partnership; other merging partnerships terminate. Consideration mixing cash and interests triggers disguised-sale analysis, and the merger cash-out rule at Regs. Sec….

Trust charitable deduction reporting narrowed under IRS proposed regs — Form 1041-A being set aside while a K-1 flows into a trust ledger

Trust charitable deduction — still Form 1041-A?

Does my trust’s charitable deduction still require a Form 1041-A? Two carve-outs would say no. The IRS’s August 2026 proposed regulations (REG-109082-25) would remove Form 1041-A for a trust charitable deduction that is only a distributive share from a pass-through entity, and confirm that a split-interest trust filing Form 5227 does not also file Form…

New IRS refundable credit rules applying PRWORA to EITC, Child Tax Credit, American Opportunity Credit, and Adoption Credit
|

Who Qualifies Under the New IRS Refundable Credit Rules?

Who qualifies under the new IRS refundable credit rules? Treasury and the IRS proposed on August 19, 2026 to treat the refunded portion of the EITC, Child Tax Credit, American Opportunity Credit, and Adoption Credit as a federal public benefit under PRWORA — available only to U.S. citizens, U.S. nationals, and qualified aliens. For families,…

Concept image of a carbon capture facility and underground storage layers with an IRS notice overlay — 45Q safe harbor
|

45Q Safe Harbor: What Notice 2026-50 Changes for CCUS

Can I still claim the §45Q credit if EPA drops subpart RR reporting? Yes — the IRS just answered that question. Under the new 45Q safe harbor in Notice 2026-50, taxpayers who cannot rely on subpart RR of the Greenhouse Gas Reporting Program can still document secure geological storage for the §45Q credit, and the…

Global tax changes in 2026 linking cross-border filing deadlines and registration portals to a single company
|

Which Global Tax Changes in 2026 Affect My U.S. Business?

Which global tax changes in 2026 affect my U.S. business? If you have a foreign parent, a foreign subsidiary or cross-border intragroup payments, four do: proposed U.S. foreign tax credit rules with a September 17 comment deadline, Pillar Two registration deadlines arriving jurisdiction by jurisdiction, spreading e-invoicing mandates, and sharply increased transfer pricing scrutiny. International…

California state tax changes showing sales tax extending to electronically delivered software from January 2027
|

What California State Tax Changes Should I Prepare For?

What California state tax changes should I prepare for? The largest is a sales tax on electronically delivered prewritten software starting January 1, 2027. Alongside it: an extended business tax credit limitation, a wave of states decoupling from federal research expensing, and an amnesty window that closes October 31, 2026. State tax moves faster than…

Federal tax changes for 2026 connecting Washington rulemaking to a small business counter with a card reader and calendar
|

Which 2026 Federal Tax Changes Affect Small Businesses?

Which 2026 federal tax changes affect my small business? The ones with a date attached: an August guidance package implementing the 2025 reconciliation law, backup withholding on payment-app settlements, the employer paid leave credit, and a September 30 federal funding deadline that decides how fast the IRS answers you this fall. Most tax headlines never…

Headline card 'FinCEN BOI Final Rule' over a stack of U.S. corporate formation documents
|

Do I still need to file a FinCEN BOI report? (2026)

Do I still need to file a FinCEN BOI report in 2026? Almost certainly not — if your company was formed in a U.S. state. The FinCEN BOI final rule (effective August 14, 2026) exempts every domestic reporting company and every U.S. person beneficial owner from BOI reporting. Only foreign entities registered to do business…

Illustration of an IRS rollover under Notice 2026-49 — retirement funds moving securely from a 401(k) plan to an IRA via an encrypted pipeline instead of a paper check
|

IRS Rollover Guidance: What Notice 2026-49 Changes

Is the IRS about to change how retirement rollovers work? Yes. The new IRS rollover guidance in Notice 2026-49 proposes four sample rollover forms, a rollover identification number to protect participant PII, and future rules that could end paper rollover checks sent to participants. If you have ever tried to move a 401(k) to an…

Net unrealized appreciation illustration: employer stock leaving a 401(k) for a taxable brokerage account
|

What is Net Unrealized Appreciation (NUA)? 401(k) Guide

What is Net Unrealized Appreciation (NUA), and could it lower my 401(k) tax bill? Net unrealized appreciation is a federal tax election under IRC §402(e)(4)(B) that lets you move employer stock out of a qualified retirement plan and pay ordinary income tax only on the stock’s original cost basis. The built-in gain is then taxed…

Illustration of OBBBA nonprofit tax rules — Capitol, donation box, university facade with IRC section tokens
|

OBBBA nonprofit tax: What changed for your 501(c)(3)?

What did the OBBBA actually change for my nonprofit? Quite a lot. The OBBBA nonprofit tax rules created a new charitable deduction for non-itemizers, added floors that shrink deductions for high-income and corporate donors, expanded the §4960 excise on high pay, and set a tiered endowment tax for large private colleges. The One Big Beautiful…

Illustration of the IRS Saver's Match — coins flowing from a government building into a piggy bank
|

What Is the IRS Savers Match? 50% Federal Match in 2027

What is the new IRS Saver’s Match, and how do I get it? The savers match is a federal 50% match on up to $2,000 of your qualified retirement contributions — worth up to $1,000 per year — deposited directly into your retirement account. It starts with 2027 contributions and the first payments arrive in…