Illustration of a Section 1031 like-kind exchange — two investment buildings with a swap arrow and a deadline calendar showing the 45-day and 180-day rules
|

Section 1031 Exchange: Defer Tax on Investment Real Estate

Can you defer tax when you sell investment property? Often, yes. A Section 1031 exchange lets you defer capital gains tax when you swap real property held for business or investment for like-kind real property. The trade-off: strict deadlines — 45 days to identify a replacement and 180 days to close — and, since 2018,…
Illustration of Qualified Opportunity Zones under IRS Notice 2026-40 — a city skyline on a map pin with a 2026 calendar marking the deferred-gain inclusion deadline
|

QOZ Update: IRS Notice 2026-40 and the Dec 31, 2026 Deadline

Are the Opportunity Zone rules changing? Yes. In IRS Notice 2026-40, the Treasury Department and the IRS announced that they intend to issue proposed regulations on Qualified Opportunity Zones under Internal Revenue Code §§ 1400Z-1 and 1400Z-2, as amended by the One, Big, Beautiful Bill Act (OBBBA). The notice provides transitional guidance for investments made…

Illustration of the 2026 SALT deduction cap — courts upholding the cap while the One Big Beautiful Bill raises the limit from $10,000 to $40,000, with a phase-out above $500,000 of income
|

SALT Deduction Cap 2026: Now $40,000 (Courts Uphold It)

Is the SALT deduction cap going away in 2026? No. Federal courts continue to uphold the SALT deduction cap, with a New Jersey federal court dismissing another constitutional challenge in May 2026. But there is relief: the One Big Beautiful Bill raised the cap from $10,000 to $40,000 beginning in 2025, with a 1% annual…

Illustration of a June 2026 international tax roundup — OECD Pillar Two global minimum tax, EU Court of Justice rulings, and country-level corporate rate changes
|

International Tax Roundup June 2026: Pillar Two, EU, Rates

What were the key international tax developments in early-to-mid June 2026? The OECD pushed forward on the global minimum tax (Pillar Two) — releasing practical fixes to the GloBE Information Return (GIR) XML schema for first filings, an updated 2026 consolidated commentary, and new transfer-pricing guidance on intragroup services. In the EU, the Court of…

Illustration of a June 2026 multistate tax roundup — California apportionment at the Supreme Court, New York's enacted budget, and the BATSA federal nexus bill
|

Multistate Tax Roundup June 2026: CA, NY, Nexus & BATSA

What changed in state and local tax in early-to-mid June 2026? A busy stretch: the U.S. Supreme Court declined to hear Florida’s challenge to California’s single-sales-factor apportionment; New York enacted a budget that extends its top corporate rate, decouples from some OBBBA provisions, and adds a “pied-à-terre” surcharge; Texas adopted cost-of-goods-sold rule changes for franchise…

Illustration of summer activities that affect your tax return — day camp, marriage, gig work, business travel, and selling digital assets
|

5 Summer Activities That Affect Your Next Tax Return

How can summer activities affect your next tax return? Several common summer events have tax consequences worth handling now, per the IRS: (1) summer DAY CAMP costs may count toward the Child and Dependent Care Credit; (2) getting MARRIED means reporting any name change to the Social Security Administration and any address change to USPS,…

Illustration of the Social Security Direct Express prepaid debit card transition from Comerica Bank to Fifth Third Bank affecting 3.6 million beneficiaries
|

Social Security Direct Express Card Change: What to Do

Is the Social Security Direct Express card changing — and do you need to do anything? Yes, for one group. The Social Security Administration (SSA) is switching the financial agent that runs its Direct Express prepaid debit card program from Comerica Bank to Fifth Third Bank, following a merger of the two institutions. This affects…

Illustration of 2026 FIFA World Cup income sourcing — IRS, Canada Revenue Agency, and Mexico SAT consensus allocating team compensation by games played across three host countries
|

2026 World Cup Taxes: IRS/CRA/SAT Income Sourcing Consensus

How is income from the 2026 FIFA World Cup taxed across the U.S., Canada, and Mexico? The 2026 FIFA World Cup is co-hosted by three countries, which raises a thorny question: when a national team earns prize money and other compensation, how is that income sourced among the United States, Canada, and Mexico? To avoid…

Illustration of an early June 2026 federal tax roundup — proposed Section 892 sovereign investor relief, a $76 estate tax closing letter fee, excepted fertility benefits, and budget reconciliation
|

Federal Tax Roundup Early June 2026: §892, Estate Fee, Regs

What federal tax developments landed in early June 2026? Three Treasury/IRS regulatory proposals and a busy week on Capitol Hill. On the regulatory side: (1) proposed regulations under §892 (CC-00349656-26, IR-2026-69) giving sovereign investors transition relief and new applicability dates tied to the December 2025 proposed rules; (2) proposed regulations (REG-103193-26) raising the estate tax…

Illustration of the California PTE elective tax — 9.3% entity-level SALT cap workaround, the June 15 payment, and the new 2026 12.5% credit reduction rule
|

California PTE Elective Tax: 9.3% SALT Workaround, 2026 Rules

What is California’s PTE elective tax, and what changed for 2026? The pass-through entity (PTE) elective tax lets a qualifying partnership or S corporation elect to pay a 9.3% entity-level California tax on its owners’ shares of income — and the owners then claim a personal income tax credit for the tax paid on their…

Illustration of qualified long-term care distributions under SECURE 2.0 section 334 and IRS Notice 2026-33 — penalty-free 401(k) money for LTC insurance premiums up to $2,600
|

Penalty-Free 401(k) for LTC Insurance: Notice 2026-33 Guide

Can you use 401(k) money to pay long-term care insurance premiums without the 10% penalty? Yes — within limits. Under SECURE 2.0 Act §334 (effective for distributions after December 29, 2025), a defined contribution plan may permit “qualified long-term care distributions” under new IRC §401(a)(39). The annual cap is the LEAST of: (1) the amount…

Illustration of the California LLC fee under R&TC section 17942 — income tiers from $900 to $11,790, the June 15 Form 3536 estimate, and the prior-year safe harbor
|

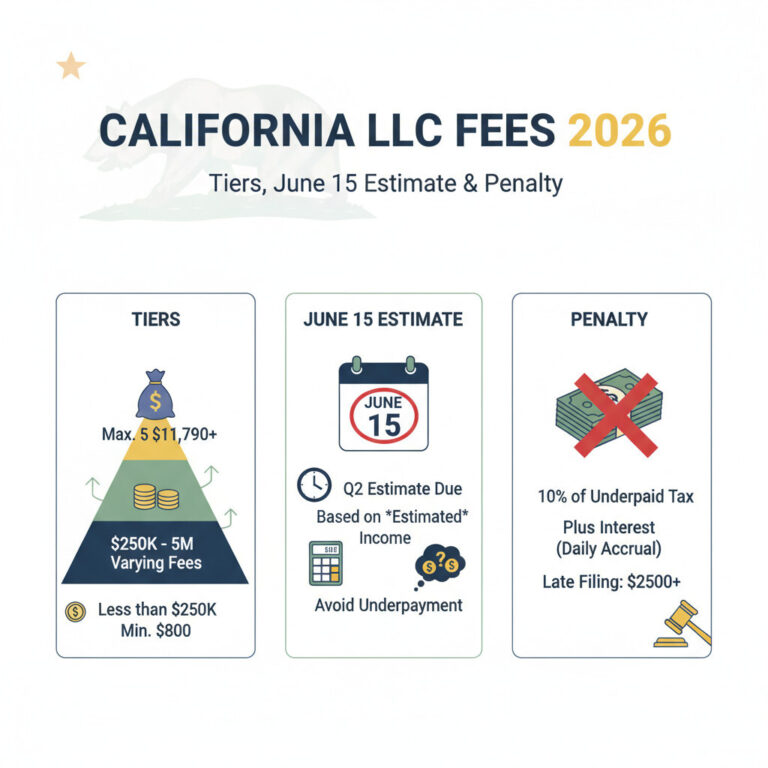
California LLC Fee 2026: Tiers, June 15 Estimate & Penalty

What is the California LLC fee, and how do you avoid the 10% penalty? Separate from the $800 annual minimum franchise tax, California imposes a second, income-based “LLC fee” (Revenue & Taxation Code §17942) on every LLC organized, doing business, or registered in California with total California-source income of at least $250,000. The fee is…

Illustration of the expanded IRC section 4960 21% excise tax on nonprofit executive compensation over $1 million under OBBBA and IRS Notice 2026-36
|

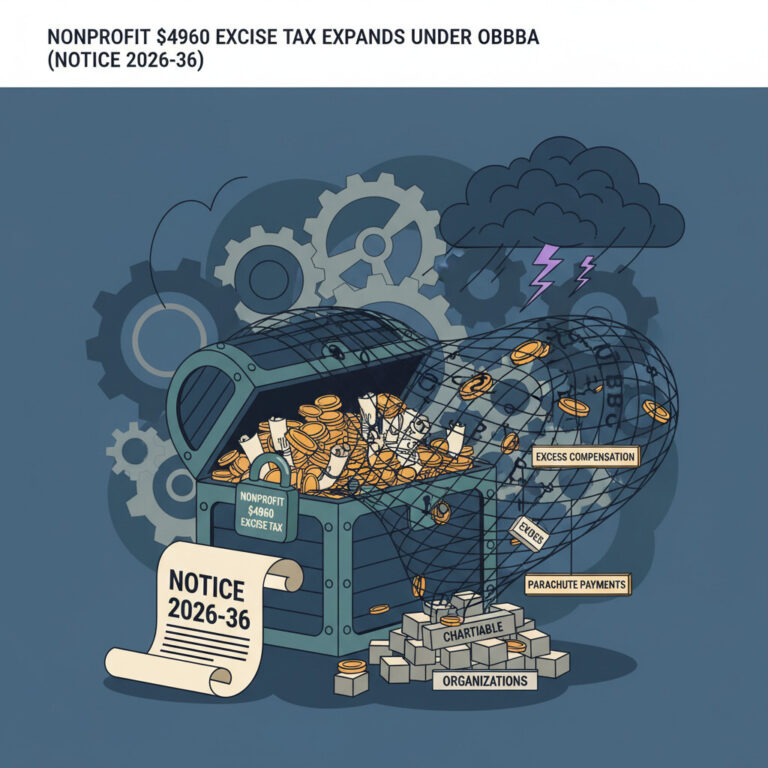
Nonprofit §4960 Excise Tax Expands Under OBBBA (Notice 2026-36)

How did OBBBA expand the §4960 excise tax on nonprofit executive compensation? Internal Revenue Code §4960 imposes a 21% excise tax on a tax-exempt organization’s “excess remuneration” — compensation over $1 million paid to a covered employee — plus certain excess parachute (separation) payments. Under the One, Big, Beautiful Bill Act, beginning with tax years…

Illustration of late May 2026 federal tax roundup — JCT OBBBA report, Treasury IRS guidance T.D. 10048 and Notice 2026-33, House tax bills, and Tax Court section 6038(b) rulings
|

Federal Tax Roundup Late May 2026: OBBBA, IRS Guidance, Courts

What are the most important federal tax developments from late May 2026? Four stand out. (1) The Joint Committee on Taxation released a 341-page provision-by-provision report on the One, Big, Beautiful Bill Act (OBBBA, P.L. 119-21) and flagged 10 provisions that may need technical correction. (2) Treasury and the IRS issued new guidance — final…

Illustration of OBBBA federal student loan limits and the Department of Education professional degree rule — $200K professional vs $100K other graduate caps, accounting excluded
|

OBBBA Student Loan Limits: New Caps & Professional Degree Rule

How did OBBBA change federal student loans for graduate and professional students? The One, Big, Beautiful Bill Act (OBBBA, Pub. L. No. 119-21) placed new caps on federal student loans and directed the U.S. Department of Education (DOE) to define which “professional degree” programs qualify for higher borrowing limits. Under the DOE’s final rule, only…

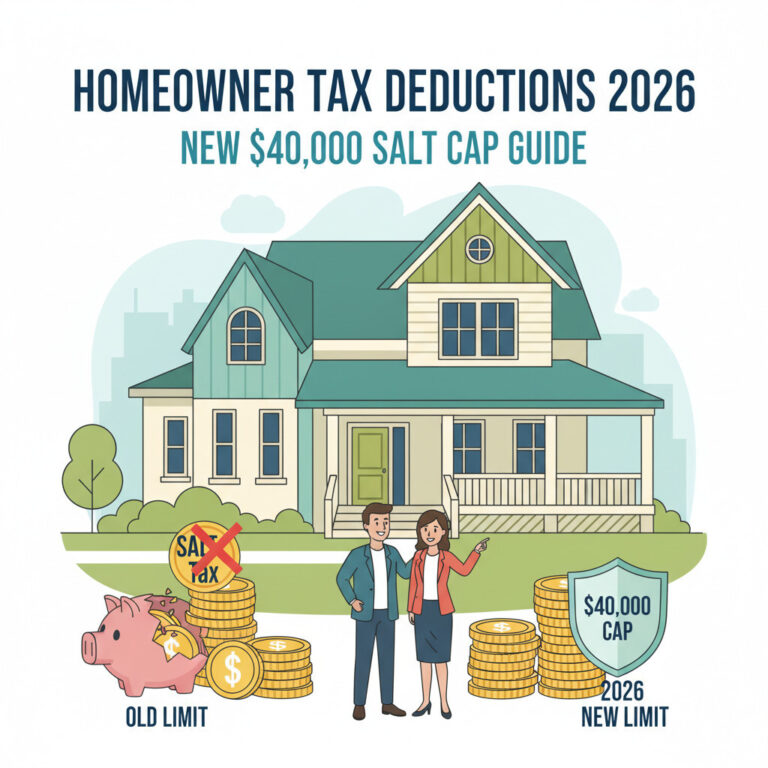
Illustration of 2026 homeowner tax deductions — the new $40,000 SALT cap on real estate taxes, mortgage interest limits, and non-deductible home costs on IRS Schedule A
|

Homeowner Tax Deductions 2026: New $40,000 SALT Cap Guide

What home expenses can you actually deduct in 2026 — and what’s the new SALT cap? To deduct homeownership expenses you must ITEMIZE. The two main deductible items are (1) state and local real estate taxes — now subject to a $40,000 limit ($20,000 if married filing separately) under the increased SALT deduction cap —…

Illustration of Form 990 filing requirements and the IRC section 6033(j) three-year automatic revocation trap for tax-exempt nonprofit organizations
|

Form 990 Filing & the 3-Year Automatic Revocation Trap

Which Form 990 must your nonprofit file, and what happens if you miss it? Most tax-exempt organizations must file an annual return in the Form 990 series, due by the 15th day of the 5th month after the organization’s accounting period ends (May 15 for calendar-year filers). Which form you file — 990-N, 990-EZ, 990,…

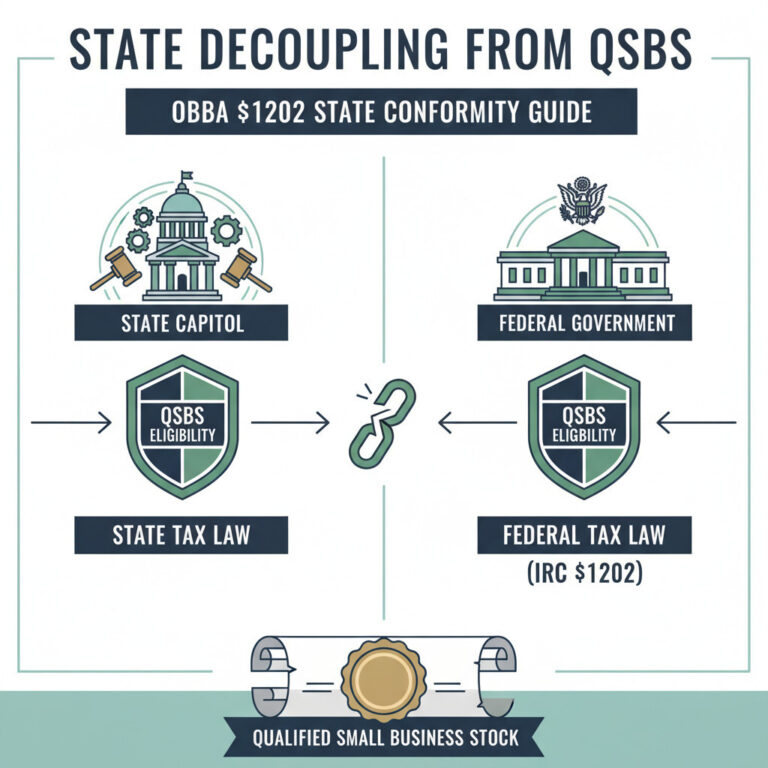
Illustration of state decoupling from federal QSBS section 1202 exclusion under OBBBA — Maine and Oregon decoupled, California taxes QSBS gains, state conformity risk for founders
|

State Decoupling from QSBS: OBBBA §1202 State Conformity Guide

Do states follow the federal QSBS exclusion under OBBBA — and why does state conformity matter? Not automatically. The One Big Beautiful Bill Act (OBBBA, Pub. L. No. 119-21) expanded the federal Qualified Small Business Stock (QSBS) exclusion under IRC §1202 — but states set their own conformity. Maine and Oregon have enacted legislation DECOUPLING…

Illustration of FASB transferable tax credits accounting project — IRA, CHIPS, and OBBBA credit accounting gap, ASC 740 vs ASC 832 analogies, recognition triggers
|

FASB Transferable Tax Credits Project: Accounting Gap Guide

How should companies account for transferable tax credits under U.S. GAAP? The Financial Accounting Standards Board (FASB) voted in May 2026 to advance a project on the accounting treatment of nonrefundable transferable tax credits — including the Inflation Reduction Act (IRA) clean energy credits under IRC §6418, CHIPS and Science Act semiconductor credits, and One…

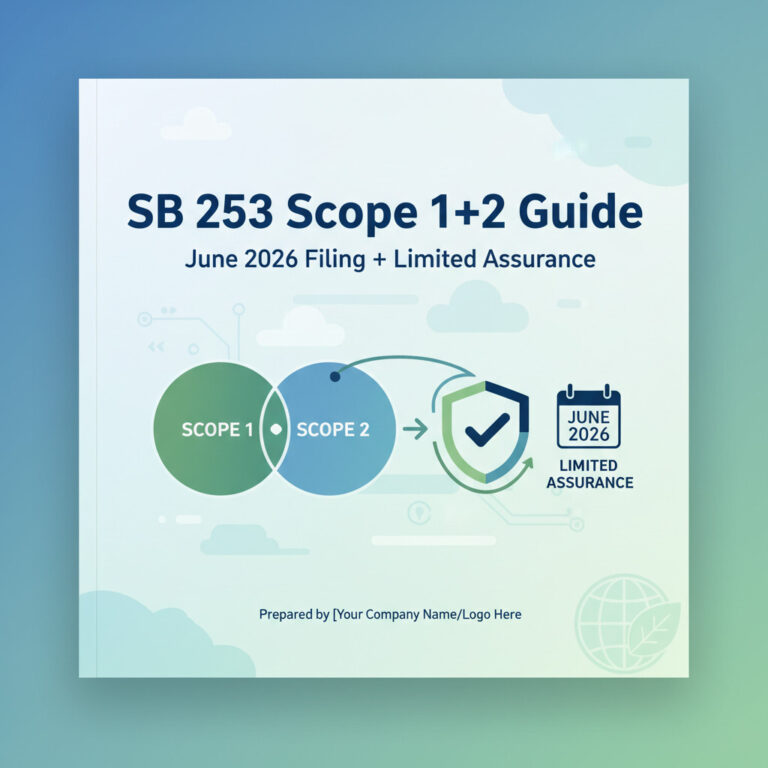
Illustration of California SB 253 Scope 1 and Scope 2 emissions measurement — GHG Protocol methodology, location-based vs market-based dual reporting, June 30 2026 filing
|

SB 253 Scope 1+2 Guide: June 2026 Filing + Limited Assurance

How do California SB 253 reporting entities measure Scope 1 and Scope 2 emissions for the June 30, 2026 first filing? SB 253 (Health & Safety Code §38532) requires U.S. companies with revenues over $1 billion doing business in California to publicly disclose Scope 1 (direct) and Scope 2 (purchased energy) greenhouse gas emissions starting…

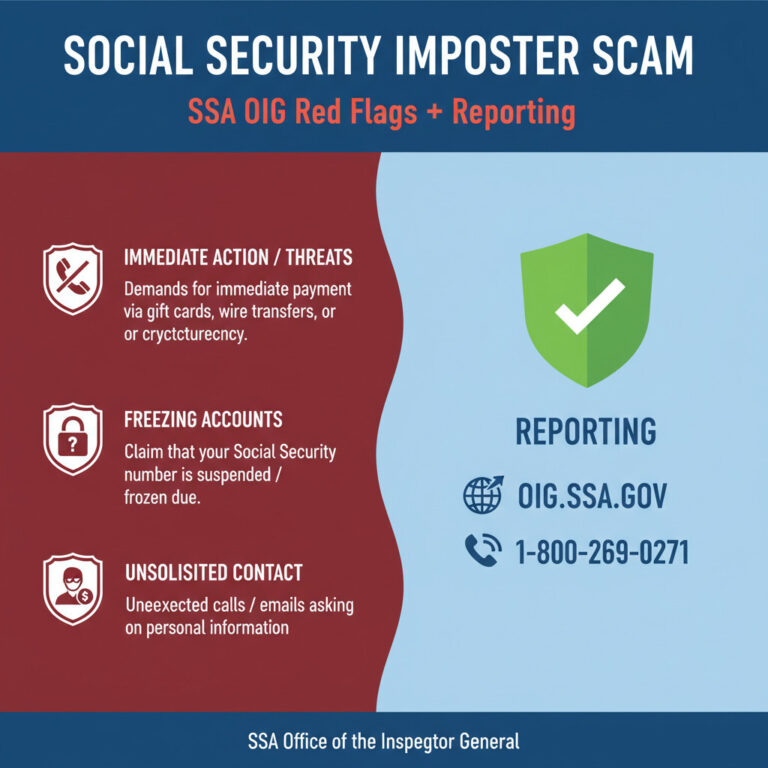
Illustration of Social Security imposter scam red flags — SSA OIG warning about doctored badge photos, gift card demands, and federal fraud reporting channels
|

Social Security Imposter Scam: SSA OIG Red Flags + Reporting

How can you tell a Social Security imposter scam from a real government contact? The Social Security Administration Office of the Inspector General (SSA OIG) issued a fresh warning in 2026 about a rising imposter scam: criminals impersonate real federal employees by harvesting names from social media and sending doctored badge photos to “verify” their…

Illustration of IRS Offer in Compromise process — Form 656-B application, Reasonable Collection Potential calculation, and 2026 Dirty Dozen OIC mills warning
|

IRS Offer in Compromise: Form 656-B + 2026 OIC Mills Warning

How does the IRS Offer in Compromise work, and how do you avoid OIC mills? An IRS Offer in Compromise (OIC) is a legally-binding agreement between a taxpayer and the IRS to settle outstanding tax debt for less than the full amount owed. You apply with Form 656-B (Offer in Compromise Booklet) plus a $205…

Illustration of California SB 261 climate-related financial risk reporting — TCFD four-pillar framework and January 1, 2026 first-cycle deadline
|

SB 261 Climate Financial Risk Reporting: TCFD Guide Jan 2026

What does California SB 261 require for climate-related financial risk reporting? California’s SB 261 (Public Resources Code §38533, the Climate-Related Financial Risk Act, as amended by SB 219) requires U.S. companies with annual revenues over $500 million doing business in California to publish a biennial climate-related financial risk report. The first report is due January…