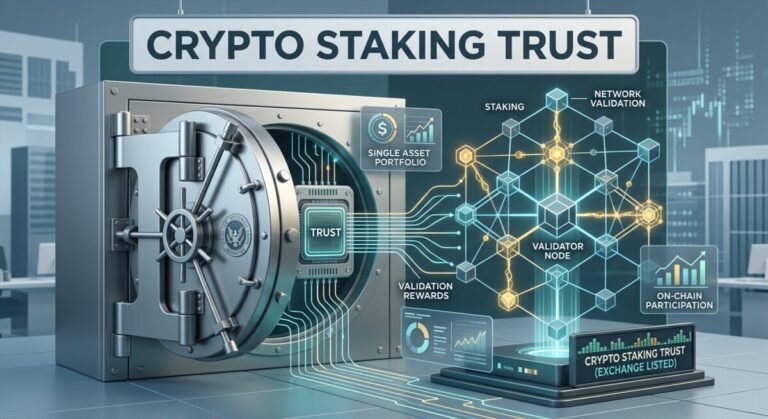
Crypto staking trust safe harbor: an SEC-registered investment trust staking digital assets on a proof-of-stake network
|

Can a crypto staking trust stay a grantor trust in 2026?

Can a crypto staking trust still qualify as a grantor trust in 2026? Yes — if it meets the fourteen conditions in IRS Rev. Proc. 2026-20. The new revenue procedure gives a crypto staking trust a safe harbor to stake its digital assets without losing investment-trust status under 26 CFR 301.7701-4(c). Every quarter we hear…

Section 351 ETF conversion recharacterized: substance over form under IRS Rev. Rul. 2026-20
|

Section 351 ETF conversion: Rev. Rul. 2026-20

Does the Section 351 ETF conversion still work after Rev. Rul. 2026-20? Not the way it has been sold. The IRS now treats a planned transfer of securities to a new ETF followed by an authorized-participant redemption of those same securities as a single taxable exchange, not a tax-free diversification. The Section 351 ETF conversion…

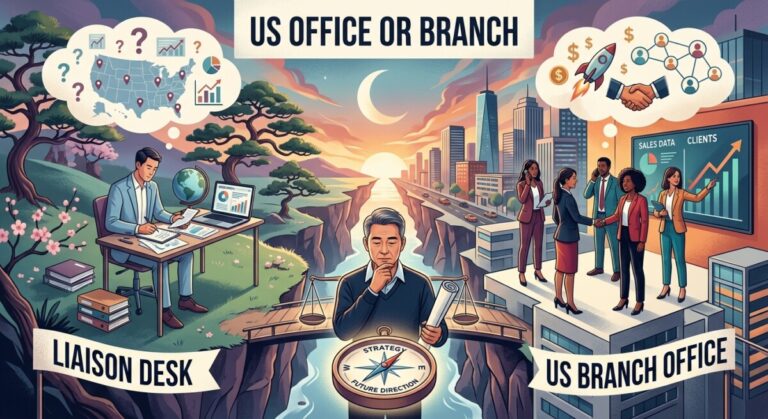
Side-by-side depiction of a US representative office and a US branch, contrasting the two US presence options a Korean parent company must choose between.
|

US representative office vs branch: what should a Korean parent set up?

If my Korean parent only wants to watch the US market, is a representative office enough — or do I already need a branch? A US representative office that limits itself to market research, information gathering, and liaison work typically falls outside the US “trade or business” definition under IRC §864(b), so it files no…

Crypto international tax: structuring a global digital asset group under IRS and §482 rules
|

How do I plan crypto international tax for a global group?

How does crypto international tax structuring work for a global group? A US-founded crypto business has to align entity classification, controlled-foreign-corporation rules, transfer pricing, IP ownership, and digital-asset reporting with how it actually operates. Crypto international tax is not a jurisdiction search; it is a documentation discipline. A protocol launches with founders in Los Angeles,…

Employee tax benefits: a US small business reviewing its 2026 benefits package
|

Employee tax benefits 2026: What can my business offer?

What employee tax benefits can my business offer in 2026? The federal tax code pays for a surprising share of a competitive benefits package. The right employee tax benefits can lower a small employer’s net cost of paid leave, education, child care, retirement savings, and even a new Trump Account, through credits and exclusions that…

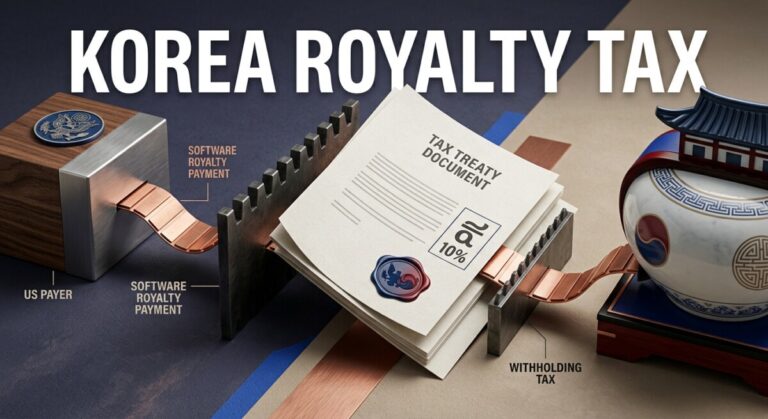
US-Korea tax treaty royalty withholding — illustration of cross-border software royalty payment and reduced treaty rate.
|

What is the US-Korea tax treaty royalty rate, and how do I claim it?

Does the US-Korea tax treaty actually reduce the 30% default withholding on a software royalty paid to a Korean licensor? Yes — a US payer must generally withhold 30% on a US-source royalty, but the Korea tax treaty royalty article can cut the rate to 10% or 15% depending on the royalty type, provided the…

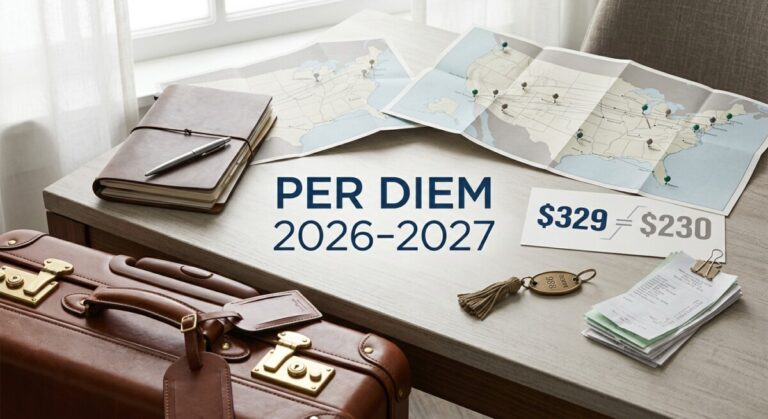
Business traveler and the 2026–2027 IRS per diem rates ($329 high-cost / $230 other CONUS)
|

What are the new IRS per diem rates for 2026–2027?

What are the new IRS per diem rates for 2026–2027? Notice 2026-60 sets the high-low per diem rates at $329 for high-cost localities and $230 elsewhere in CONUS, effective October 1, 2026. Transportation-industry M&IE is $80 CONUS and $86 OCONUS, and the incidental-only rate stays at $5 per day. Every October, a wave of expense-policy…

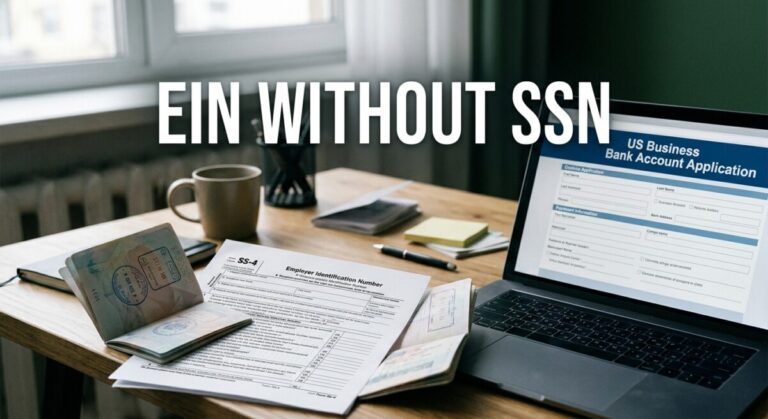
IRS Form SS-4 on a foreign founder's desk beside a passport and a laptop showing a US business bank account application.

How do I get an EIN without an SSN? (Foreign founder guide, 2026)

How do I get an EIN without an SSN as a foreign founder? You file IRS Form SS-4 by fax or by calling the International EIN line at +1-267-941-1099. An SSN or ITIN is not required for the responsible party if none exists — write “Foreign” on line 7b instead. Plan on roughly 4–8 weeks…

Livestock drought relief: dry pasture and a small herd, illustrating IRS section 1033 replacement-period extension for drought-sold livestock
|

Livestock drought relief: did IRS extend the 1033 period?

Do I get more time to replace drought-sold livestock under the 2026 IRS notice? If the county where you sold, or any contiguous county, is on the Notice 2026-54 Appendix, yes. The IRS treats the 12-month period ending August 31, 2026 as not a drought-free year, so the section 1033(e) four-year replacement period is extended…

California cybersecurity audit: CCPA Article 9 rule for covered businesses
|

California cybersecurity audit: does the CCPA rule apply?

Does the California cybersecurity audit rule apply to my business? A California business is in scope if it either earned at least 50% of its revenue from selling or sharing personal information, or exceeded roughly $26.625 million in annual gross revenue and processed the personal information of at least 250,000 California consumers or households (or…

California digital products sales tax: SaaS and prewritten software become taxable January 1, 2027
|

Does California’s digital products sales tax apply to SaaS?

Does California’s digital products sales tax apply to my software business? Starting January 1, 2027, prewritten software — including Software-as-a-Service and remote-access licenses — is a taxable digital product under California’s new digital products sales tax rule enacted by Senate Bill 122. Custom software and several digital-media categories stay outside the rule. A short email…

IRS CAP program 2027: real-time corporate tax issue resolution with an Oct. 30 deadline
|

What is the IRS CAP program, and who qualifies for 2027?

Should our corporation apply to the IRS CAP program for 2027? The IRS opened the 2027 application window in September 2026 with an Oct. 30, 2026 deadline. The IRS CAP program resolves material tax issues in real time before the return is filed — but only for corporations that clear a strict eligibility bar. If…

ICE Endex Section 1256: Netherlands futures exchange now qualified for U.S. mark-to-market
|

Are ICE Endex futures Section 1256 contracts? (2026)

Are ICE Endex futures Section 1256 contracts now? Yes — for contracts entered into on or after September 1, 2026. In Rev. Rul. 2026-16, the IRS determined that ICE Endex, a Netherlands regulated exchange, is a qualified board or exchange under § 1256(g)(7)(C), so its futures and futures options get mark-to-market and 60/40 capital-gain treatment…

OBBBA method change: IRS Rev. Proc. 2026-32 covers § 174 R&E and § 460(e) residential construction
|

OBBBA method change under IRS Rev. Proc. 2026-32?

Does the IRS finally have an automatic-consent path for OBBBA R&E and residential construction changes? Yes. IRS Rev. Proc. 2026-32 opens the automatic OBBBA method change for § 174, § 174A, and § 460(e), waives the usual eligibility bars through 2027, and gives one transition window that closes November 15, 2026. On September 4, 2026,…

QSBS: founder's C-corporation stock reshaped in a tax-free recap without breaking Section 1202
|

How to keep QSBS treatment through a recap (2026)

How do founders keep QSBS treatment through a recapitalization? A Section 368(a)(1)(E) tax-free recap can preserve QSBS under Section 1202(h)(4)(A), but only if the reorganization requirements are met, the aggregate gross assets threshold is respected, and Section 305 does not turn the recap into a taxable deemed distribution. Many of our founder clients organize as…

SBA size standards overhaul: 338 categories, employment-based default, comments due September 21, 2026
|

How do new SBA size standards change small business status?

Are the SBA size standards really changing before September 21, 2026? Yes — SBA has proposed the biggest rewrite of sba size standards since it adopted NAICS in 2000. The proposal collapses roughly 1,000 standards to 338, defaults to employment-based measures, and adjusts receipts standards for productivity growth. Comments close September 21, 2026, and the…

Small business owner using the IRS Business Tax Account on a laptop to view notices, download CP575, and manage payments
|

Who can use the IRS Business Tax Account (2026)?

Who can now use the IRS Business Tax Account? As of 2026, the IRS Business Tax Account covers partnerships, tax-exempt organizations, Indian tribal governments, and federal, state, and local governments, alongside the sole proprietors and corporations who had access before. Inside the account, entities can view digital notices, download CP575 EIN verification, and pay against…

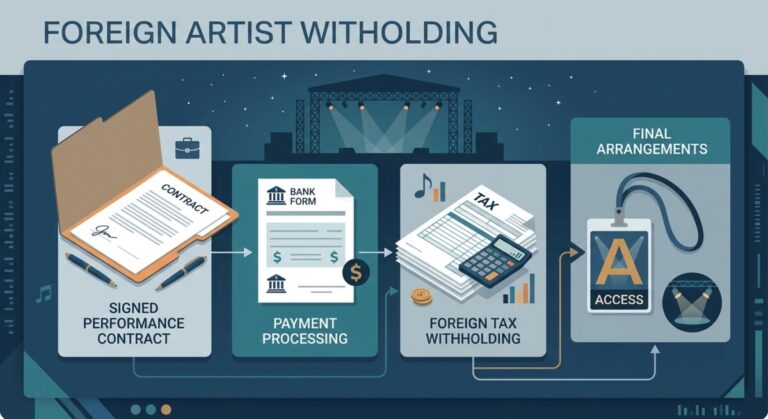
Foreign artist withholding: a California promoter's contract and wire form before paying an international act
|

Foreign artist withholding in California: who is liable?

Who handles foreign artist withholding when a California venue books an international act? You do. The payer is the withholding agent for 30 percent federal tax on the gross fee and 7 percent California tax on payments over $1,500. Foreign artist withholding drops only when the artist hands you an IRS Central Withholding Agreement letter,…

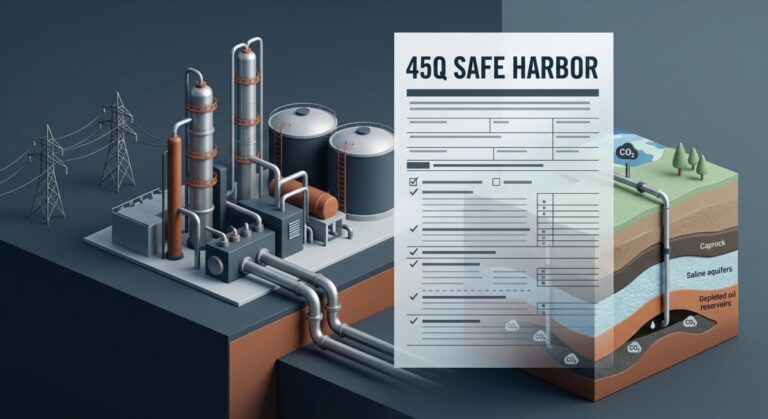
Concept image of a carbon capture facility and underground storage layers with an IRS notice overlay — 45Q safe harbor
|

45Q Safe Harbor: What Notice 2026-50 Changes for CCUS

Can I still claim the §45Q credit if EPA drops subpart RR reporting? Yes — the IRS just answered that question. Under the new 45Q safe harbor in Notice 2026-50, taxpayers who cannot rely on subpart RR of the Greenhouse Gas Reporting Program can still document secure geological storage for the §45Q credit, and the…

California state tax changes showing sales tax extending to electronically delivered software from January 2027
|

What California State Tax Changes Should I Prepare For?

What California state tax changes should I prepare for? The largest is a sales tax on electronically delivered prewritten software starting January 1, 2027. Alongside it: an extended business tax credit limitation, a wave of states decoupling from federal research expensing, and an amnesty window that closes October 31, 2026. State tax moves faster than…

Federal tax changes for 2026 connecting Washington rulemaking to a small business counter with a card reader and calendar
|

Which 2026 Federal Tax Changes Affect Small Businesses?

Which 2026 federal tax changes affect my small business? The ones with a date attached: an August guidance package implementing the 2025 reconciliation law, backup withholding on payment-app settlements, the employer paid leave credit, and a September 30 federal funding deadline that decides how fast the IRS answers you this fall. Most tax headlines never…