How Partnership Merger Tax Rules Work Under Sec. 708
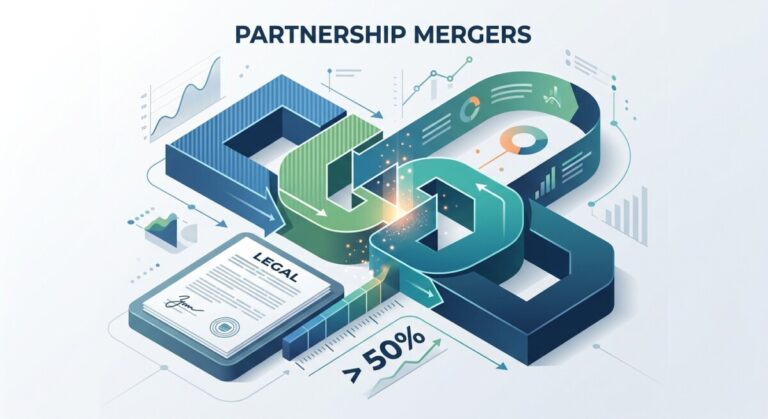
How do partnership merger tax rules work under Sec. 708(b)(2)(A)? A resulting partnership is a continuation of any merging partnership whose partners own more than 50% of the capital and profits of the resulting partnership; other merging partnerships terminate. Consideration mixing cash and interests triggers disguised-sale analysis, and the merger cash-out rule at Regs. Sec….