FIRPTA 2026 changes: DC REIT lookthrough rule repealed and Sec. 892 rules finalized
|

What changed for FIRPTA 2026 and foreign investors?

What changed for FIRPTA in 2026 for foreign investors in U.S. real estate? Two Treasury releases moved the ground under cross-border deals — the 2025 proposed regulations on domestically controlled REITs repeal the lookthrough rule for U.S. corporate shareholders, and the 2025 final FIRPTA-adjacent Sec. 892 regulations give foreign governments a workable path to hold…
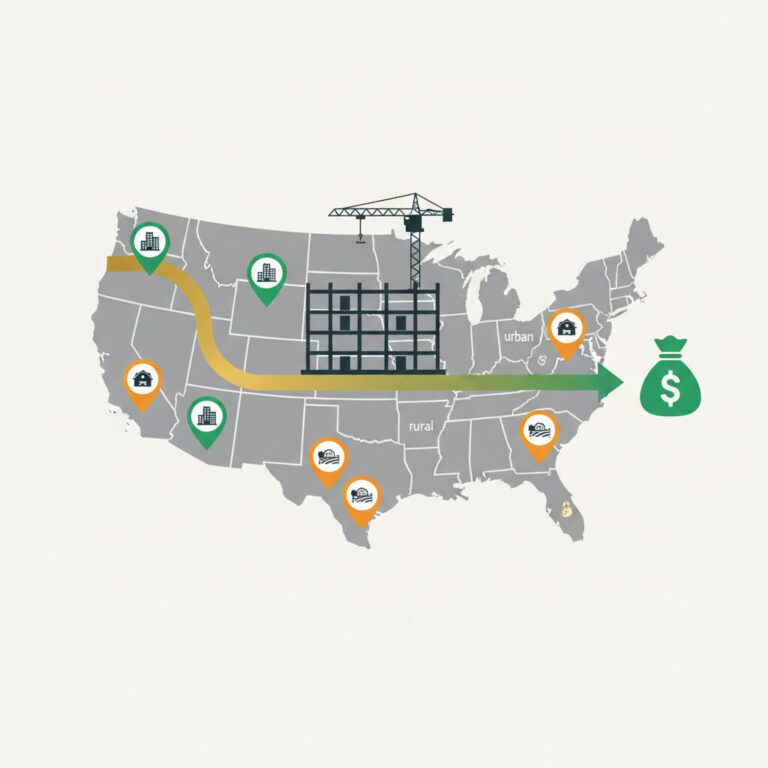
Illustration of the IRS Opportunity Zone transition — an urban skyline with a December 31 clock over a development blueprint
|

IRS Opportunity Zone Transition Rules 2026: Notice 2026-40

Does the new Opportunity Zone regime just extend the old rules? No. The IRS Opportunity Zone transition rules in Notice 2026-40 keep the December 31, 2026 deferred-gain date, but reinvested QOF gains restart the 10-year clock and ongoing projects now need a written working-capital plan in place by year-end. The IRS has finally drawn a…

Qualified opportunity zone designation 2027 obbba featured
|

Qualified Opportunity Zone Designation 2027: OBBBA Changes Explained

What is the qualified opportunity zone designation process for 2027? Rev. Proc. 2026-14 sets the procedure for State CEOs to nominate census tracts as QOZs effective January 1, 2027 — implementing the OBBBA’s overhaul of Sections 1400Z-1 and 1400Z-2, which now includes a new Qualified Rural Opportunity Fund (QROF) category and a flexible “applicable start…