State Tax Update: CA SaaS Tax & More (Sept 2026)
What changed this week
| Development | Who it affects |
|---|---|
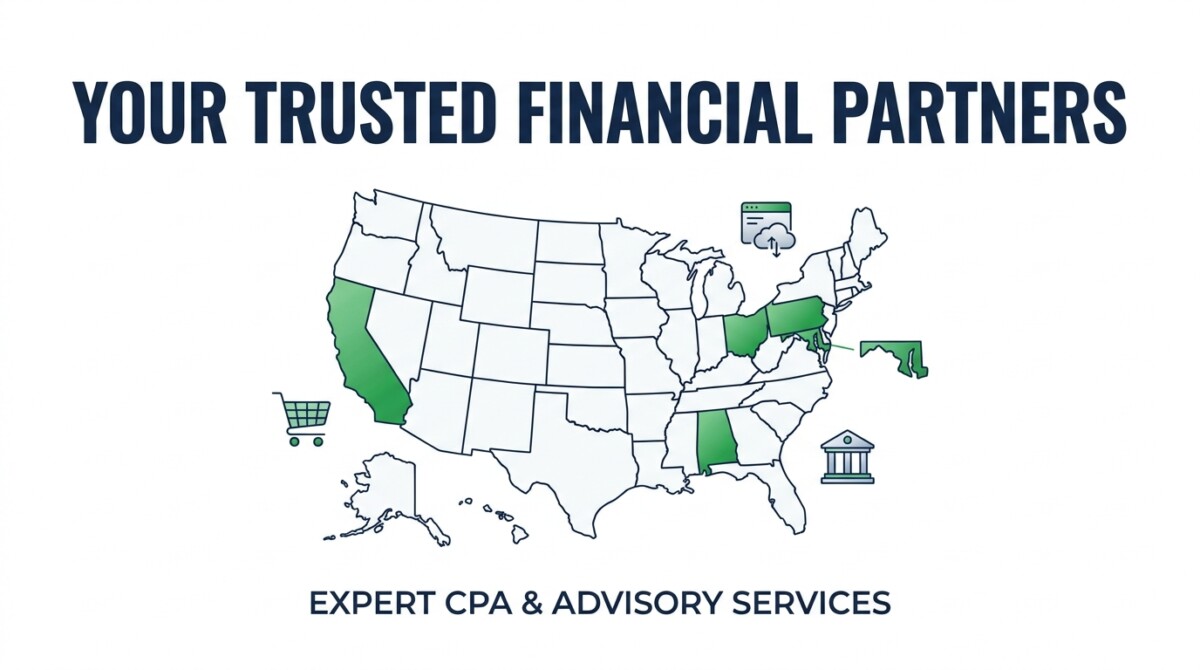
| California to Tax SaaS and Digital Products Starting 2027 | Any business that sells, licenses, or subscribes California customers to software, SaaS platforms, or other digital products delivered electronically. |
| Congress Considers Limits on Taxing Employees Who Travel or Work Remotely | Employers with employees who travel for work or work remotely from a state other than where the business is based, and employees who earn wages while physically present in more than one state during the year. |
| Philadelphia’s Local Sales Tax Switches to Destination-Based Sourcing October 1 | Any business, inside or outside Pennsylvania, that delivers taxable products or services to customers located in Philadelphia or Allegheny County. |
| Maryland’s Digital Advertising Tax Ruled Unconstitutional | Businesses that paid Maryland’s Digital Advertising Gross Revenues Tax, and any company tracking similar digital-advertising or digital-economy tax proposals in other states. |
| Alabama Excludes Credit Card Fees from Sales Tax | Alabama retailers and service providers who charge customers a separate credit or debit card processing fee. |
| Ohio Launches New Capital Gains Deductions for Business Owners | Ohio business owners planning to sell an ownership interest in their company, and investors in certified Ohio venture capital funds. |
California to Tax SaaS and Digital Products Starting 2027
California has enacted a major change to its sales and use tax law. Under amended Revenue and Taxation Code section 6009, subdivisions (b) and (c), the definition of a taxable “use” now includes opening, viewing, accessing, downloading, copying, updating, possessing, or storing a digital product that is transferred electronically or accessed remotely, including prewritten (off-the-shelf) computer software and Software-as-a-Service (SaaS) platforms. This change takes effect January 1, 2027. Until now, California was one of the few states that did not tax standard SaaS subscriptions or downloaded software. Under the new law, the definition of taxable tangible personal property expands to cover the right to open, view, access, download, copy, update, possess, store, or otherwise use these digital products. For local and district tax purposes, the sale is generally sourced to the customer’s billing address, and use is sourced to where the person accessing the product is located. Some categories remain exempt, including digital assets such as cryptocurrency, digital books, digital audio and video works (such as streamed music or movies), digital video games, and cloud infrastructure services that let customers build or run their own applications. The state’s tax agency is still writing the detailed regulations that will explain exactly how the tax applies, and it has been holding public workshops and taking written comments on the draft rules.
Who it affects: Any business that sells, licenses, or subscribes California customers to software, SaaS platforms, or other digital products delivered electronically.
What to do
Start identifying which of your digital products and SaaS subscriptions will become taxable in California, update your billing and point-of-sale systems ahead of the January 1, 2027 effective date, and review the state’s draft regulations (or submit comments) before they are finalized.
Primary source: California SB 122 (Chapter 23, 2026)
Congress Considers Limits on Taxing Employees Who Travel or Work Remotely
Two bills introduced in the U.S. House of Representatives this year would change how states can tax employees who work across state lines, though neither has passed yet. The first, introduced September 3, 2026, would generally limit a state’s ability to tax wages of an employee who is not a resident of that state unless the employee is physically present and working there for more than 30 days in a calendar year. It would also let an employer rely on an employee’s own record of time spent in each state, unless the employer already uses a formal time-and-attendance tracking system. The second bill, introduced August 24, 2026, takes a related approach: it would bar a state from treating a nonresident employee as “present” or taxable in that state for any day the employee was physically located in a different state. That provision is aimed at so-called convenience-of-the-employer rules, under which some states tax the full wages of a remote employee as if the work were performed at the employer’s office, even when the employee never sets foot there. Similar bills have been introduced in past sessions of Congress without becoming law, so business owners should treat this as a trend to watch rather than a change to plan around yet.
Who it affects: Employers with employees who travel for work or work remotely from a state other than where the business is based, and employees who earn wages while physically present in more than one state during the year.
What to do
Keep your current state-by-state payroll withholding and employee time-tracking practices in place for now, but track both bills’ progress in Congress, since either one would ease multistate withholding obligations if enacted.
Primary source: U.S. Government Publishing Office — H.R. 10271, Mobile Workforce State Income Tax Simplification Act of 2026 · U.S. Government Publishing Office — H.R. 10142, Multi-State Worker Tax Fairness Act of 2026
Philadelphia’s Local Sales Tax Switches to Destination-Based Sourcing October 1
Businesses that deliver taxable goods or services into Philadelphia need to change how they calculate local sales tax starting October 1, 2026. Under the prior rule, Philadelphia’s 2% local sales tax followed the seller’s location. Under the new rule, the tax follows the customer’s delivery address instead. For example, a business located outside Philadelphia that delivers a taxable product to a customer inside the city must now collect the 2% local tax on that sale, something it may not have had to do before. The city’s combined sales tax rate is not changing; it remains 8% overall, made up of the state’s 6% sales tax plus Philadelphia’s 2% local tax. A similar destination-based change applies to Allegheny County’s 1% local sales tax. Although the underlying law technically took effect earlier in 2026, the city’s revenue department is giving businesses a grace period and will not begin enforcing the new sourcing rule until October 1, 2026. In its own guidance, the department recommends that businesses review their sales and delivery records, update point-of-sale and online checkout systems to charge tax based on the delivery address, and confirm their tax filing processes are ready before the enforcement date arrives.
Who it affects: Any business, inside or outside Pennsylvania, that delivers taxable products or services to customers located in Philadelphia or Allegheny County.
What to do
Update your point-of-sale and e-commerce systems now so that Philadelphia’s 2% (or Allegheny County’s 1%) local sales tax is charged based on the customer’s delivery address, and confirm this is working correctly before the October 1, 2026 enforcement date.
Primary source: City of Philadelphia Department of Revenue — Philly’s Sales Tax Rules Are Changing
Maryland’s Digital Advertising Tax Ruled Unconstitutional
On August 14, 2026, the Maryland Tax Court struck down the state’s Digital Advertising Gross Revenues Tax in three related cases. Maryland had enacted this tax in 2021 as the first state in the country to specifically tax revenue that large companies earn from digital advertising shown to Maryland users, at rates from 2.5% up to 10% depending on a company’s global revenue, and only applied to companies with more than $100 million in annual worldwide revenue. The court held that the tax is preempted by the federal Internet Tax Freedom Act, which bars states from imposing discriminatory taxes on electronic commerce, and that it also violates the U.S. Constitution’s Commerce Clause and Due Process Clause; in one of the three cases, the court found an additional First Amendment violation. The court ordered the state to refund, with interest, the tax paid by the companies that challenged it for the first year the tax was in effect. The decision does not automatically cancel the tax for every company that paid it, and Maryland could still appeal, but it significantly weakens the legal basis for this type of tax and may influence similar digital-advertising or digital-economy taxes that other states have enacted or proposed.
Who it affects: Businesses that paid Maryland’s Digital Advertising Gross Revenues Tax, and any company tracking similar digital-advertising or digital-economy tax proposals in other states.
What to do
If your business paid Maryland’s digital advertising tax, talk to your tax advisor about whether you should file a protective refund claim for open tax years, and keep watching whether Maryland appeals or other states change similar tax laws in response.
Primary source: Maryland Tax Court — Apple Inc. v. Comptroller of Maryland, Final Order
Alabama Excludes Credit Card Fees from Sales Tax
Alabama businesses that pass along credit card processing costs to customers got a clear rule this year on how those fees are taxed. Effective September 1, 2026, a credit card transaction fee, sometimes called a swipe fee, surcharge, processing fee, or convenience fee, is excluded from the amount subject to Alabama sales and use tax, as long as the fee is separately stated from the price of the taxable item on the customer’s receipt or invoice. The Alabama Department of Revenue has amended its regulation, effective October 15, 2026, to reflect this change. In practice, this means a business that clearly breaks out the card fee as its own line item only owes sales tax on the price of the item itself, not on the added fee. If a business instead bundles the fee into a single undifferentiated total charge, the entire amount, including the fee, remains subject to sales tax. This is a meaningful, low-cost fix for any Alabama business that already itemizes card fees on receipts, but it requires updating point-of-sale or invoicing templates to keep the fee visibly separate.
Who it affects: Alabama retailers and service providers who charge customers a separate credit or debit card processing fee.
What to do
Confirm your point-of-sale or invoicing system lists any credit card processing fee as its own line item, separate from the taxable sale price, so the fee itself is not taxed under Alabama’s updated rule.
Primary source: Alabama Department of Revenue — Are Credit Card Transaction Fees Subject to Sales and Use Taxes?
Ohio Launches New Capital Gains Deductions for Business Owners
Ohio business owners and investors now have access to two new individual income tax deductions for capital gains, which apply for tax years beginning in or after 2026. These deductions were originally written into Ohio law years earlier but were delayed until now to take effect. The first deduction applies to gains from investments in a certified Ohio venture capital operating company: qualifying investors can deduct all of the gain tied to an eligible Ohio business, and half of the gain from other qualifying investments, but the fund itself must be certified by the state, manage at least $50 million in active assets, and have at least two-thirds of its managing partners based in Ohio. The second deduction is aimed at business owners directly: an Ohio taxpayer who sells an ownership interest, such as stock or membership units, in a company headquartered in Ohio may be able to deduct the resulting capital gain from Ohio income tax. This second deduction generally does not apply to a sale structured as an asset sale rather than a sale of the ownership interest itself, so how a deal is structured matters for whether the deduction is available.
Who it affects: Ohio business owners planning to sell an ownership interest in their company, and investors in certified Ohio venture capital funds.
What to do
If you are planning to sell an Ohio-headquartered business or you invest through an Ohio-based venture capital fund, talk to your tax advisor before closing a 2026 transaction to confirm whether it qualifies for one of these new deductions and how the deal should be structured.
Primary source: Ohio Revised Code section 5747.01(A)(35) — venture capital operating company capital gain deduction · Ohio Revised Code section 5747.79 — deduction for capital gains from sale of business
What this means for your business
- California will start taxing SaaS and other digital products on January 1, 2027 — a major shift for any business selling software into the state.
- Local sales tax sourcing rules are changing in Philadelphia (and Allegheny County) starting October 1, 2026, based on delivery address rather than seller location.
- Congress is discussing (but has not passed) bills that would limit how states tax traveling and remote employees — worth watching, not yet worth changing payroll practices over.
- A Maryland court decision striking down that state’s digital advertising tax could mean refunds for companies that paid it, and may affect similar taxes elsewhere.
- Smaller, state-specific changes — like Alabama’s credit card fee exclusion and Ohio’s new capital gains deductions — can still meaningfully affect what a particular business owes.
This week in one line
California is preparing to tax SaaS and digital products for the first time starting in 2027, Philadelphia is switching to destination-based local sales tax sourcing on October 1, 2026, and a Maryland court ruling against that state’s digital advertising tax could open the door to refunds.
Frequently asked questions
Q. When does California start taxing SaaS and digital products?
The new law takes effect January 1, 2027. California’s tax agency is still finalizing the detailed regulations that will explain exactly how the tax applies, so the rules could still be refined before then.
Q. Do I need to change how I charge Philadelphia customers sales tax right now?
The new destination-based sourcing rule is not enforced until October 1, 2026, but it is a good idea to update your point-of-sale or e-commerce system before that date so you are not scrambling at the last minute.
Q. Should I stop collecting Maryland’s digital advertising tax now that a court struck it down?
Talk to your tax advisor first. The ruling is a strong signal against the tax, but Maryland could appeal, and any decision about ongoing collection or refund claims should be made with professional advice specific to your situation.
Q. Will the pending federal bills on mobile and remote workers change my payroll withholding?
Not yet. Both bills are still pending in Congress and have not been enacted, so current state-by-state withholding rules still apply. Similar bills have failed to pass in previous years.