How do I pull cash out of a US C-corp without double tax? (dividend vs salary vs royalty, 2026)
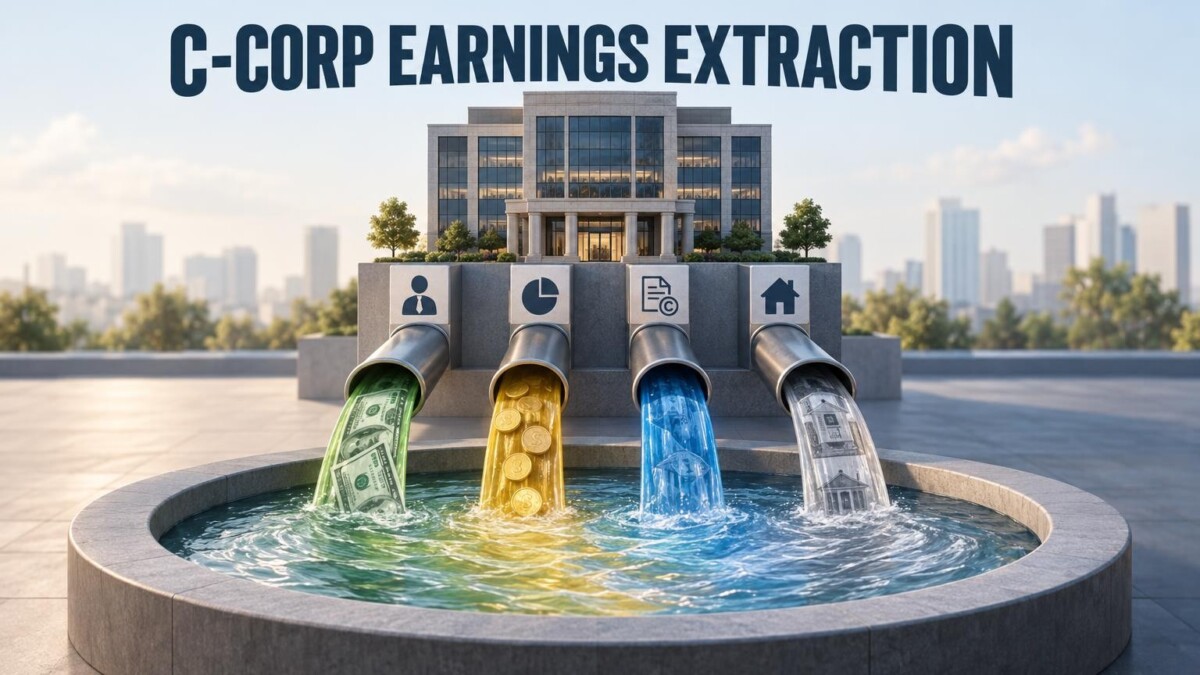
Every Korean founder who incorporates a Delaware C-corp runs into the same wall by year two: the company is finally profitable, but a $100,000 cash distribution to the owner costs $21,000 of federal corporate tax plus up to $23,800 of shareholder-level qualified dividend tax plus Net Investment Income Tax. That is where c corp earnings extraction planning begins. In our practice at SW Accounting & Consulting Corp., the four-channel framework below is how we lower the effective combined rate from roughly 39% to the low 20s — legally — while keeping the plan defensible under IRS examination.
What makes C-corp double taxation so painful? 💸
A dollar earned inside a C-corporation is taxed first at 21% (federal) plus state, then taxed again at up to 23.8% when it leaves as a dividend — a stacked effective rate that can approach 40%.
The first layer is the C-corp income tax under 26 U.S.C. §11: a flat 21% on every dollar of taxable income. The second layer bites when the corporation distributes its after-tax earnings. Under 26 U.S.C. §301 and §316, a distribution out of earnings and profits is a dividend to the shareholder — taxable at ordinary rates for a nonresident or at up to 20% qualified-dividend rates for a US individual (plus 3.8% Net Investment Income Tax under 26 U.S.C. §1411). The IRS’s own Publication 542 (Corporations) walks through the mechanics.
For a Korean-resident shareholder, the second layer is a 15% US dividend withholding under the US–Korea Income Tax Treaty, Article 12, published by the US Treasury. That is lower than the 30% statutory rate — but still a hard second tax that LLC and S-corp owners simply do not pay. That is why extracting earnings through other channels, where lawful, is the single biggest lever on a Korean founder’s take-home.
Is a reasonable salary the simplest cash-extraction method? 💼
Yes — a salary is deductible to the C-corp under 26 U.S.C. §162(a)(1), so it zeroes out the first-layer 21% tax dollar-for-dollar, provided the pay is “reasonable” for the services actually rendered.
The statutory anchor is 26 U.S.C. §162(a)(1), which lets a corporation deduct “a reasonable allowance for salaries or other compensation for personal services actually rendered.” Two rules shape the planning:
- The salary must be reasonable. Factors the IRS and Tax Court weigh include the employee’s role, qualifications, hours, the size and complexity of the business, comparable compensation at similar companies, and the return on investment left for shareholders after the salary is paid. The Tax Court articulated the modern framework in Exacto Spring Corp. v. Commissioner, 196 F.3d 833 (7th Cir. 1999) — the “independent-investor test.”
- Payroll taxes apply. FICA (Social Security 6.2% employer + 6.2% employee up to the wage base, and Medicare 1.45% employer + 1.45% employee uncapped) and FUTA apply to wages. See the IRS Publication 15 (Employer’s Tax Guide). For a Korean-resident founder, the US–Korea Totalization Agreement can exempt US FICA under a detached-worker certificate for the first five years.
Rule of thumb from our practice: a C-corp paying a founder’s entire bank line as “salary” is a red flag. A salary roughly at market for the role, benchmarked to BLS Occupational Employment Statistics, survives audit with little argument.
When should a C-corp pay dividends instead of salary? 💰
When salary is already at the ceiling the IRS will call reasonable, further cash should go out as a dividend — because an “unreasonable salary” is recharacterized by the IRS as a disguised dividend anyway, but with a 10% underpayment penalty bolted on.
Dividends are not deductible by the corporation (that is the whole point of double taxation under 26 U.S.C. §301), but they carry two advantages:
- Lower tax rate for US individual shareholders. Qualified dividends are taxed at 0%, 15%, or 20% under 26 U.S.C. §1(h)(11), versus ordinary rates up to 37% on wages. A US-resident founder who has already maxed out a reasonable salary pays less on marginal dividend dollars than on marginal salary dollars.
- No payroll tax. Dividends are not wages, so FICA and FUTA do not apply.
For a Korean-resident shareholder, the comparison is different: the 15% treaty withholding under US–Korea Treaty Article 12 applies to dividends, and Korea credits that against Korean income tax. Dividends are often still cheaper than taking a US salary subject to US income tax at graduated rates, because the Korean shareholder avoids US payroll tax and the US ordinary-income schedule.
Can a Korean parent charge a royalty to the US C-corp? 🇰🇷
Yes — provided the royalty is for the use of an actual intangible owned by the Korean parent (software code, patent, trademark, know-how) and the rate is arm’s length under 26 U.S.C. §482 and Treas. Reg. §1.482-4.
A royalty is a third extraction channel and the most powerful for groups where the Korean parent genuinely owns the intellectual property:
- Deductible to the US C-corp. The royalty payment is an ordinary and necessary expense under 26 U.S.C. §162, reducing the US tax base dollar-for-dollar before the 21% federal rate bites.
- Reduced US withholding under the treaty. Royalties paid to a Korean parent are subject to 10–15% US withholding under US–Korea Income Tax Treaty Article 14, versus the 30% statutory rate under 26 U.S.C. §1441.
- Arm’s-length pricing is the hard part. Treas. Reg. §1.482-4 sets out the four allowed methods: Comparable Uncontrolled Transaction (CUT), Comparable Profits Method, Profit Split, and unspecified methods. Contemporaneous transfer-pricing documentation under 26 U.S.C. §6662 is required to avoid the 20–40% accuracy-related penalties. See also the IRS international practice unit on transfer pricing.
⚠️ Watch out: a royalty needs a real IP owner.
We regularly see Korean parents sign a “trademark license agreement” with their US subsidiary without ever registering the trademark in the US and without the Korean parent having created any development-stage IP. On examination, the IRS recharacterizes the royalty as a disguised dividend, denies the US deduction, and asserts the §6662 transfer-pricing penalty. If the Korean parent is going to charge a royalty, the IP must exist, be documented, and the Korean parent must bear the development risk under Treas. Reg. §1.482-4.
What about shareholder loans and renting property to the C-corp? 🏢
Both can work, but both are high-audit-risk channels unless they look like real third-party transactions on paper and in cash flow.
Shareholder loan from the C-corp to the owner. A loan is not a distribution, so the second layer of tax is deferred. But the Tax Court will recharacterize a loan as a disguised dividend if the loan lacks the usual indicia of debt — a written note, a stated interest rate at or above the Applicable Federal Rate published monthly by the IRS under 26 U.S.C. §7872, a fixed maturity, a repayment history, and a reasonable debt-to-equity position for the corporation. The leading case is Tax Court Memo cases like Alterman Foods, where a long-dormant loan was recharacterized.
Rent from the C-corp to the owner (or an owner-controlled LLC). If the owner personally holds the real property and leases it to the C-corp, the rent is deductible to the C-corp under 26 U.S.C. §162 and taxable to the owner at ordinary rates — but importantly, rental income is passive income under 26 U.S.C. §469 and is not subject to self-employment tax. The rent must be arm’s length; 26 U.S.C. §482 applies even between a controlled individual and a controlled corporation.
💡 Expert insight — the stacked plan we built for a profitable Korean-owned C-corp last year.
A Korean-owned beauty-brand C-corp with $800,000 of 2025 net income before owner comp was paying nothing to the founder-shareholder and was about to distribute the full amount as a dividend — a $168,000 federal corporate tax plus a $150,000 shareholder-level tax (37% US ordinary, no treaty, because the founder had been a US tax resident for three years). We rebuilt the plan: $220,000 reasonable salary (benchmarked to BLS data for “chief executives, consumer products”), a $120,000 arm’s-length trademark royalty to the Korean parent (CUT method, contemporaneous documentation), a $90,000 office-space rent payable to the founder’s separate LLC, and a $150,000 qualified dividend. Combined federal tax dropped roughly $62,000 for the same cash in the founder’s hands — and the group still files a clean Form 5472 for the royalty to Korea.
What is the Accumulated Earnings Tax and when does it hit? 🧨
The Accumulated Earnings Tax (AET) is a 20% penalty under 26 U.S.C. §531 on earnings a C-corp retains beyond the reasonable needs of the business — a third-layer tax that punishes refusing to distribute.
The AET is the IRS’s answer to founders who try to avoid the second layer of tax by simply leaving cash in the C-corp forever. Under 26 U.S.C. §531 and §532, a corporation availed of to avoid shareholder-level tax pays an extra 20% on its accumulated taxable income. There is a $250,000 credit ($150,000 for a personal service corporation) under 26 U.S.C. §535(c), but above that the corporation must show the retained earnings are needed for specific, documented business plans — capex, inventory build-out, working-capital reserves.
Earnings-extraction planning therefore has a floor and a ceiling. Pay too little out and the AET bites; pay too much out as salary and the IRS recharacterizes it as a dividend. Both ends are worked in the planning cycle each fall before year-end close.
Key takeaways for Korean-owned C-corp earnings extraction
- Reasonable salary (§162): deductible to the C-corp, zeroes out the 21% first layer, benchmark to BLS data to survive audit.
- Qualified dividend (§301): use once salary hits reasonable ceiling — 0/15/20% to US shareholders, 15% treaty withholding to Korean parent.
- Royalty to Korean parent (§482): powerful but requires real IP, arm’s-length pricing, contemporaneous documentation and Form 5472.
- Shareholder loan (§7872): real note, AFR interest, maturity, repayment schedule — or it is recharacterized as a dividend.
- Rent (§162 + §469): passive income to the owner, deductible to the C-corp, no SE tax.
- Watch the ceiling: the Accumulated Earnings Tax (§531) imposes a 20% penalty on undistributed earnings above $250,000 without documented business need.
Frequently asked questions ❓
Can I just pay myself the entire C-corp profit as salary and zero out the corporate tax?
No. 26 U.S.C. §162(a)(1) allows a deduction only for salary that is “reasonable” for services actually rendered. The IRS and the Tax Court apply the independent-investor test from Exacto Spring; pay that leaves no reasonable return for shareholders is recharacterized as a nondeductible dividend plus a §6662 accuracy-related penalty.
What dividend withholding rate applies to a Korean-resident shareholder of a US C-corp?
The statutory rate is 30% under 26 U.S.C. §1441, reduced to 15% on portfolio dividends and 10% on direct-investment dividends (shareholder owning at least 10% of voting stock) under Article 12 of the US–Korea Income Tax Treaty published by the US Treasury. Form W-8BEN or W-8BEN-E is required to claim the treaty rate.
Does paying a royalty to my Korean parent save tax on the US side?
It can. The royalty is deductible against the 21% US corporate tax and the treaty cuts US withholding on royalties under US–Korea Treaty Article 14. But the pricing must be arm’s length under 26 U.S.C. §482 and Treas. Reg. §1.482-4, with contemporaneous documentation; otherwise the IRS will reallocate the income and impose §6662 penalties of 20–40%.
How much can my C-corp accumulate before the Accumulated Earnings Tax applies?
Up to $250,000 of accumulated earnings ($150,000 for a personal service corporation) under 26 U.S.C. §535(c). Above that, the corporation must document the reasonable needs of the business for the retained earnings or pay a 20% AET under 26 U.S.C. §531.
Is it better to run a Korean-owned US business as an LLC to avoid double taxation entirely?
For small, closely-held businesses with a single Korean owner and no plan to raise US venture capital, often yes — a Delaware LLC taxed as a disregarded entity or partnership avoids the entity-level 21% tax. But VC-backed startups, QSBS-eligible companies, and groups expecting to issue employee stock options generally need a C-corp. The right answer depends on the exit strategy, not just the current tax bill.
Do I need to file Form 5472 if my C-corp pays a royalty to the Korean parent?
Yes. A 25%-or-more foreign-owned US corporation must file Form 5472 for every reportable transaction with a related foreign party, including royalties. The penalty for failure to file is $25,000 per form per year.