Can a crypto staking trust stay a grantor trust in 2026?
Every quarter we hear the same question from clients and fund counsel in Los Angeles: can a listed spot-crypto product stake its holdings without destroying its tax classification? Until recently the answer was unsettled. The investment-trust rules in 26 CFR 301.7701-4(c) classify a trust that has a power to vary the investment of certificate holders as a business entity, often taxable as a corporation. Staking looked uncomfortably close to that line. On October 6, 2026, the IRS and the Treasury Department resolved the uncertainty for a crypto staking trust by issuing Rev. Proc. 2026-20, which clarifies, modifies, and supersedes Rev. Proc. 2025-31. This post walks through what the safe harbor actually requires, where it stops, and what trustees and sponsors should do before the six-month implementation window closes.
What exactly does Rev. Proc. 2026-20 permit? 🔗
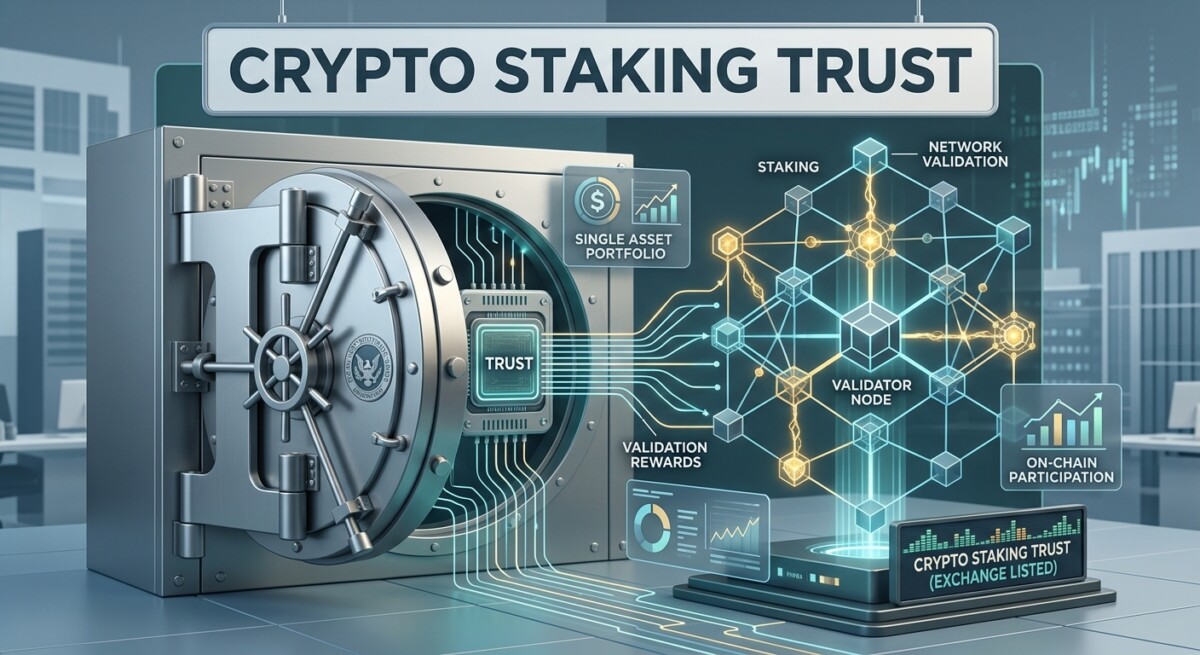
It lets a single-asset proof-of-stake trust stake its digital assets, through qualified custodians and arm’s-length staking providers, without the IRS treating that activity as a power to vary the investment that would knock the trust out of grantor-trust status.
The safe harbor is narrow by design. It covers only an arrangement that already qualifies as an investment trust under 26 CFR 301.7701-4 and as a grantor trust immediately before meeting the fourteen conditions in Section 6.02 of the revenue procedure. A trust that would already fail the grantor-trust tests under IRC section 671 and IRC section 677 does not get rehabilitated by the safe harbor. The revenue procedure is about preserving an existing classification, not creating a new one.
The practical scope is a listed, SEC-registered spot-crypto exchange-traded product that holds one proof-of-stake digital asset, such as a single-asset ETP whose underlying token participates in network validation. The asset must be a digital asset within the meaning of IRC section 6045(g)(3)(D), and transactions in that asset must settle on a permissionless proof-of-stake network. Multi-asset wrappers, private funds, and permissioned-ledger products are outside the safe harbor.
What are the fourteen safe-harbor conditions a crypto staking trust must meet? ✅
They cover listing and SEC filings, the single-asset rule, custody and private-key control, the staking relationship, liquidity reserves, slashing indemnity, and quarterly distribution of rewards.
The requirements fall into six functional groups. Each one has to be satisfied; a trust that misses even one condition is outside the safe harbor and has to analyze the power-to-vary question on its own facts.
| Group | What the safe harbor requires |
|---|---|
| Exchange and SEC | Interests are traded on a national securities exchange, staking disclosures are filed in an effective SEC registration statement, the trust’s activities match the May 29, 2025 Division of Corporation Finance Statement, and written liquidity risk policies that comply with the exchange’s generic listing standards are in place. |
| Asset scope | The trust owns only cash and units of a single type of proof-of-stake digital asset. No multi-asset baskets, no non-staking strategies, no additional income streams. |
| Custody | A custodian holds the digital assets at addresses it alone controls. For Federal income tax purposes, the trust retains ownership of the digital assets at all times, including while they are staked. |
| Staking relationship | The staking provider is unrelated to the trust, the sponsor, and the custodian. Allocations of rewards and other contract terms are arm’s length. The trust has no legal right to direct the staking provider’s activities beyond deciding what to stake and when to unstake. |
| Liquidity reserve | Unstaked holdings are permitted only as a reserve required by the exchange’s liquidity rules, or on a short-term temporary basis around creations, redemptions, systemic protective measures, custodian or staking-provider changes, or legal and regulatory changes. |
| Rewards and slashing | Rewards are distributed in kind or in cash to interest holders within 60 days after the end of the quarter in which the trust gains dominion and control over them. The trust is indemnified against slashing attributable to events within the staking provider’s control. |
From our practice: the operating documents do the work
In our practice, the safe harbor lives or dies in the trust agreement, the custody agreement, and the staking service agreement. The IRS does not audit the blockchain. It audits documents. Trustees who treat Rev. Proc. 2026-20 as a drafting exercise, with clean recitations of each condition and explicit limits on trustee discretion, come out with a defensible position. Trustees who treat it as a disclosure exercise do not.
Why does the 85 percent liquidity rule matter for a crypto staking trust? 💧
Because the exchange’s generic listing standards require that at least 85 percent of a trust’s assets be readily available to meet redemptions within one business day, and staked assets are generally not readily available.
The exchange standard turns staking into a liquidity question first and a tax question second. An asset is not readily available if it is segregated, pledged, hypothecated, encumbered, or otherwise restricted or prevented from being liquidated, sold, transferred, or assigned within one business day. A proof-of-stake lockup or cooldown period meets that definition. If staked balances exceed 15 percent of trust assets on any given day, the trust must adopt written liquidity risk policies, publish them on its website, and review them at least annually.
Rev. Proc. 2026-20 lets the trustee carve out a liquidity reserve under those policies without falling out of the safe harbor. The reserve must be based on exchange-driven liquidity factors, not market timing. The trustee is also allowed to unstake temporarily to handle creations and redemptions, protect against protocol or software vulnerabilities, change custodians or staking providers, or respond to a change in law. Any such unstaked balance must be returned to staking as soon as reasonably possible.
Market timing is not a reason to unstake
The revenue procedure is explicit that the trustee is prohibited from seeking to take advantage of variations in the market, including variations in the value of the digital assets or in the amount of staking rewards. A liquidity policy that quietly lets the trustee move in and out of staking based on expected rewards or price would read as a power to vary the investment and would blow the safe harbor.
How must a crypto staking trust handle rewards and distributions? 🎁
Rewards must be the same asset the trust already holds, counted net of trust expenses, and distributed to interest holders in kind, in cash, or in a combination, within 60 days after the end of the calendar quarter in which the trust gains dominion and control over them.
The reward rule has three edges. First, the only new assets the trust may receive from staking are additional units, in the same form, of the single digital asset it already holds. A trust that receives governance tokens, airdrops, or any other distinct asset from the staking arrangement is outside the safe harbor. Rev. Proc. 2026-20 explicitly disclaims any inference about forks and airdrops. Second, the distribution clock starts when the trust gains dominion and control, consistent with the broader property-treatment framework in Notice 2014-21. That is not necessarily when a reward is validated on-chain; it is when the trust can actually sell or move the units. Third, the sale price of any rewards converted to cash for distribution is fixed at the time of that sale, not at the time of accrual. Trustees must track accruals and sales separately.
Consistent treatment is required across all staking rewards. A trust that classified minted units as capital contributions in one period cannot flip to income treatment in another without supporting documentation. The requirement is partly a tax rule and partly a disclosure rule — the SEC filings and the trust’s financial statements have to tell the same story the trust tells its sponsors and the IRS.
How does Rev. Proc. 2026-20 interact with SEC and exchange rules? 🏛️
The safe harbor assumes active SEC oversight and exchange compliance. The IRS layered its tax safe harbor on top of existing securities-law infrastructure rather than building a parallel regime.
The trust’s staking activities must match the SEC Division of Corporation Finance Statement on Certain Protocol Staking Activities, issued on May 29, 2025, which addresses protocol staking on digital asset networks that use proof-of-stake. The trust’s disclosures must be filed in an effective SEC registration statement and remain subject to the SEC’s continued oversight. The exchange’s generic listing standards drive the liquidity framework. The IRS deliberately did not reinvent any of those requirements. A trust that satisfies the exchange and SEC pieces picks up the Federal income tax safe harbor almost as a byproduct, provided the trust-level conditions are also in place.
That layered design has a practical consequence for counsel. A failure in SEC disclosure, for example an outdated or inconsistent staking description in an updated registration statement, is a direct failure of the IRS safe harbor as well, because the fourteen conditions specifically reference the exchange and SEC frameworks. The three regimes travel together.
What should a crypto staking trust do before the six-month window closes? 📅
Review the trust agreement, custody agreement, and staking service agreement against each of the fourteen conditions; update SEC filings and exchange liquidity policies; and document the quarterly reward-distribution calendar — all within six months of October 6, 2026.
- Map every one of the fourteen conditions to a document reference. A single spreadsheet with one row per condition, citing the paragraph of the trust agreement, custody agreement, or staking service agreement that satisfies it, is the practical minimum.
- Amend the trust agreement if needed. The revenue procedure explicitly permits amendments to authorize staking during the six-month window, and those amendments do not themselves disqualify the trust from investment-trust status.
- Confirm the custody and staking contracts are arm’s length. The trust, the sponsor, and the custodian cannot be related to the staking provider. The reward-allocation formula must be independent of the staking provider’s expenses, which rules out cost-plus or reimbursement arrangements masquerading as reward splits.
- Build a slashing indemnity. The staking service agreement must indemnify the trust against slashing within the staking provider’s reasonable control. Without that provision, the safe harbor condition is simply not met.
- Document the liquidity-reserve policy. The policy must be exchange-driven, publicly disclosed on the trust’s website, and reviewed at least annually. Keep an auditable trail of the daily staked percentage and the trustee’s decisions.
- Calendar the 60-day distribution window. Rewards must be distributed in cash or in kind no later than 60 days after the end of the quarter in which the trust gains dominion and control over them. Build the operating calendar now, not at year-end.
Summary: Rev. Proc. 2026-20 for a crypto staking trust
- The IRS safe harbor lets a single-asset proof-of-stake investment trust stake its digital assets without losing grantor-trust status under 26 CFR 301.7701-4(c).
- The safe harbor applies to tax years ending on or after October 6, 2026, and allows existing trusts a six-month implementation window to amend documents and processes.
- The trust must be listed on a national securities exchange, SEC-registered, hold a single proof-of-stake asset, and comply with the exchange’s 85 percent liquidity standard.
- Rewards must be the same asset, counted net of expenses, and distributed within 60 days after the quarter in which the trust gains dominion and control.
- Rev. Proc. 2026-20 clarifies, modifies, and supersedes Rev. Proc. 2025-31; the earlier guidance no longer applies after six months.
Frequently asked questions about the crypto staking trust safe harbor ❓
Q. What is a crypto staking trust under Rev. Proc. 2026-20?
It is an entity formed as a trust under state law that holds a single type of proof-of-stake digital asset, trades on a national securities exchange, and files staking disclosures with the SEC. The IRS allows it to stake its assets without losing investment-trust status under 26 CFR 301.7701-4(c) or grantor-trust treatment, provided it meets fourteen specific requirements.
Q. When is the Rev. Proc. 2026-20 safe harbor effective?
The revenue procedure is effective for tax years ending on or after October 6, 2026. Existing trusts that already followed Rev. Proc. 2025-31 may rely on either that earlier guidance or Rev. Proc. 2026-20 for up to six months after October 6, 2026. After that six-month window, Rev. Proc. 2025-31 no longer applies.
Q. Can a crypto staking trust hold more than one digital asset?
No. The safe harbor requires the trust to own only cash and units of a single type of digital asset for which transactions settle on a permissionless proof-of-stake network. A multi-asset trust falls outside the scope of the safe harbor and must separately analyze whether its activities give it a power to vary the investment that would reclassify it as a business entity.
Q. What is the 85 percent liquidity rule and why does it matter for staking?
National securities exchange listing standards require a trust to keep at least 85 percent of its assets readily available to meet redemption requests on a one-business-day basis. Assets that are staked, pledged, or otherwise restricted do not count as readily available. If a trust stakes more than 15 percent of its assets on any day, it must adopt and disclose written liquidity risk policies covering that exposure.
Q. Does the safe harbor address the Federal income tax treatment of staking rewards?
Only in part. The revenue procedure confirms that staking rewards, whether newly minted units or transaction fees, must be distributed in kind or in cash to trust interest holders within 60 days after the end of the quarter in which the trust gains dominion and control over them. It does not change the general rule that digital assets are treated as property for Federal income tax purposes, consistent with Notice 2014-21.
Q. What happens if a staking provider is slashed and the trust loses units?
The safe harbor requires the trust to be indemnified against slashing attributable to activities or events reasonably within the staking provider’s control. Losses outside that scope, such as protocol-level consensus failures, remain the economic risk of the trust and ultimately of the interest holders. The indemnity is a contract term the trustee must negotiate; it is not supplied by the revenue procedure.
Q. Can the trust borrow digital assets to meet redemptions?
A trust may enter a contingent liquidity arrangement that lets it borrow cash or buy and sell digital assets to cover an adverse liquidity event. However, Rev. Proc. 2026-20 is explicit that an arrangement the trust treats as a borrowing of digital assets for Federal income tax purposes does not qualify as a contingent liquidity arrangement under the safe harbor.
This article is general information, not tax or legal advice for your situation. Trust classification turns on specific facts and documents. If your fund or ETP sponsor is evaluating Rev. Proc. 2026-20, contact SW Accounting & Consulting Corp for a confidential review.