A corporate boardroom table with two folders representing a Korean parent and a US subsidiary connected by an intercompany services invoice line.
|

Can my Korean parent use the services cost method?

Can my Korean parent charge my US subsidiary at cost for shared back-office work? Yes — if the service fits the services cost method (SCM) safe harbor in Treasury Regulation §1.482-9(b). SCM lets a Korean parent bill routine support services (bookkeeping, HR administration, payroll, IT help desk, legal admin) to a US sub at pure…
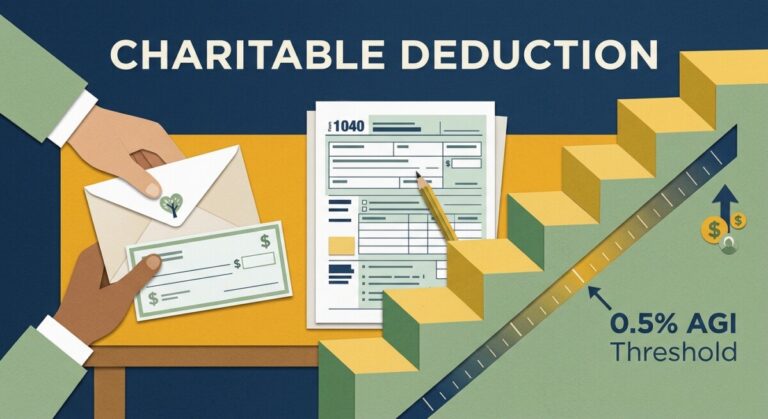
Charitable deduction under OBBBA: a donation envelope beside a tax form and a rising threshold shape
|

How does OBBBA change the charitable deduction in 2026?

Does OBBBA change the charitable deduction in 2026? Yes. Starting with the 2026 tax year, a new 0.5%-of-AGI floor and a 2/37ths cap on itemized deductions reduce the charitable deduction for most itemizers, but a new $2,000 above-the-line deduction and qualified charitable distributions give donors ways around them. Every November, a client calls our Los…

IRS partnership audits: TIGTA data show a sharp drop in exam starts since fiscal year 2023
|

Are IRS partnership audits really down in 2026?

Are IRS partnership audits really going away? Treasury performance data show partnership examination starts fell about 76% from fiscal year 2023 to fiscal year 2025, but IRS partnership audits are still live for the biggest partnerships, and the Bipartisan Budget Act regime still bills the partnership itself when one lands. A client calls after reading…

Adoption tax credit refunds: IRS automatic refunds for 2020–2024 carryforwards arriving in 2026
|

Who gets the IRS adoption credit refund in 2026?

Will the IRS send an automatic adoption credit refund? Yes, in many cases. In October 2026 the IRS began issuing an adoption credit refund to taxpayers who carried unused adoption credit forward from 2020–2024. No amended return is required for most eligible families. For many adoptive families, the adoption tax credit is the single largest…

Premium tax credit under OBBBA: a 1095-A form, a calculator, and marketplace enrollment reconciled on a desk
|

What are the new premium tax credit rules under OBBBA?

What are the new premium tax credit rules under OBBBA? The IRS and Treasury have issued proposed regulations (REG-101576-26) implementing H.R. 1 changes to Section 36B — the premium tax credit. The dollar cap on repayment of excess advance credits is gone starting with 2026 returns, new marketplace verification rules kick in after 2027, and…

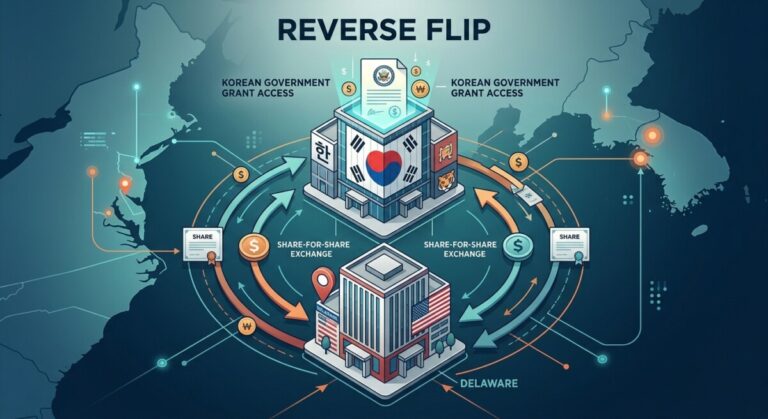
Diagram concept of a reverse flip Korea reorganization: a US Delaware C-Corp becoming a subsidiary of a new Korean holding company.
|

Can a US startup get Korean TIPS through a reverse flip?

Our US-incorporated startup wants Korean TIPS funding — can we just drop a Korean subsidiary under our Delaware C-Corp, or do we actually need to reverse flip to a Korean top? Dropping a Korean subsidiary does not qualify the group for Korean TIPS: the Korea Technology Finance Corporation and the operator programs run the grant…

Student loan forgiveness taxed again in 2026: a graduation cap next to an IRS tax notice
|

Is student loan forgiveness taxable in 2026?

Is student loan forgiveness taxable again in 2026? For most federal borrowers, yes. The temporary student loan forgiveness exclusion added by the American Rescue Plan Act sunset on December 31, 2025. Discharges in 2026 are generally includible in income under Internal Revenue Code §108, unless Public Service Loan Forgiveness, insolvency, or another specific exclusion applies….

Educator expense deduction: a teacher's unreimbursed classroom supplies and the $300 above-the-line deduction they qualify for
|

Does the educator expense deduction cover pre-K teachers?

Who claims the educator expense deduction, and did pre-K get added? The educator expense deduction is a $300 above-the-line adjustment under IRC §62(a)(2)(D) for teachers, aides, counselors, principals, and instructors. Congress has moved to extend it to pre-K and early childhood educators through H.R. 5334, the SEED Act. Every spring, teachers walk into our Los…

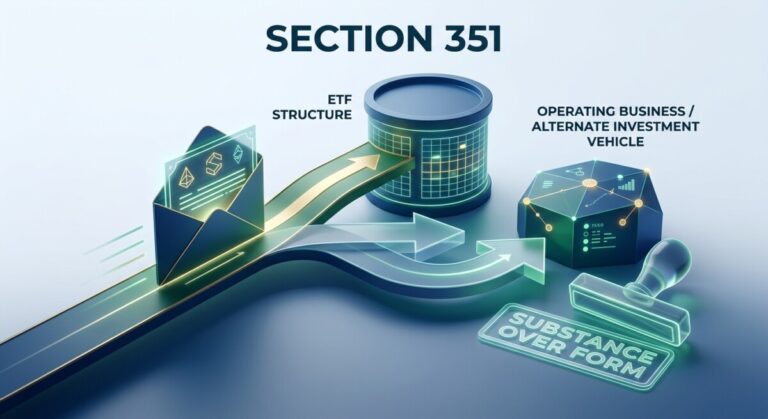
Section 351 ETF conversion recharacterized: substance over form under IRS Rev. Rul. 2026-20
|

Section 351 ETF conversion: Rev. Rul. 2026-20

Does the Section 351 ETF conversion still work after Rev. Rul. 2026-20? Not the way it has been sold. The IRS now treats a planned transfer of securities to a new ETF followed by an authorized-participant redemption of those same securities as a single taxable exchange, not a tax-free diversification. The Section 351 ETF conversion…

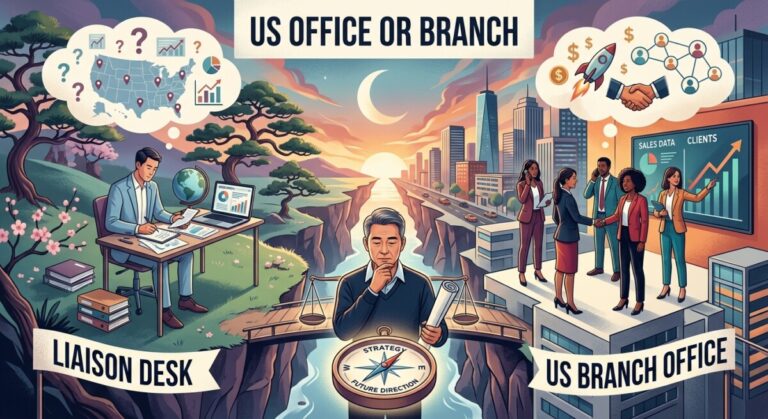
Side-by-side depiction of a US representative office and a US branch, contrasting the two US presence options a Korean parent company must choose between.
|

US representative office vs branch: what should a Korean parent set up?

If my Korean parent only wants to watch the US market, is a representative office enough — or do I already need a branch? A US representative office that limits itself to market research, information gathering, and liaison work typically falls outside the US “trade or business” definition under IRC §864(b), so it files no…

Employee tax benefits: a US small business reviewing its 2026 benefits package
|

Employee tax benefits 2026: What can my business offer?

What employee tax benefits can my business offer in 2026? The federal tax code pays for a surprising share of a competitive benefits package. The right employee tax benefits can lower a small employer’s net cost of paid leave, education, child care, retirement savings, and even a new Trump Account, through credits and exclusions that…

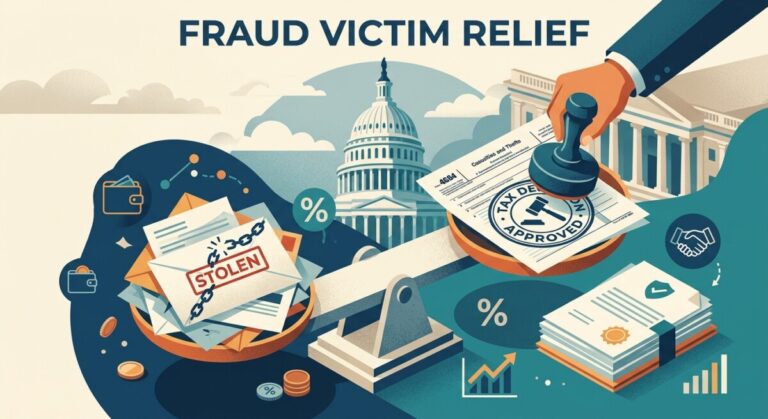
HR 9500 would restore a federal tax deduction for individual fraud and scam victims
|

What is the fraud victims tax deduction? HR 9500

Will individual fraud victims be able to deduct their losses again? On September 16, 2026, the House passed HR 9500 by a 408–17 vote. If the Senate agrees and the President signs, the fraud victims tax deduction is restored outside federally declared disasters, the retirement-account early-withdrawal penalty is waived in scam cases, and victims gain…

Clean fuel credit under section 45Z: IRS Notice 2026-53 and the OBBBA amendments
|

Does the clean fuel credit still cover my fuel in 2026?

How does the clean fuel credit work after the OBBBA? The clean fuel credit under § 45Z still rewards low-emissions transportation fuel produced in the United States, but IRS Notice 2026-53 reshapes it for 2026. ILUC emissions are out. Non-North American feedstocks are out. Animal manure gets its own emissions rate. Here is what to…

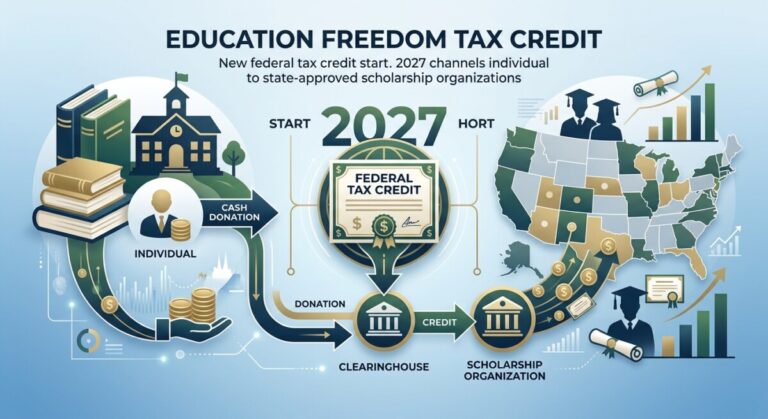
Education Freedom Tax Credit: a new federal $1,700 credit for cash gifts to state-listed Scholarship Granting Organizations starting January 1, 2027
|

How does the Education Freedom Tax Credit work in 2027?

What is the Education Freedom Tax Credit, and how does it work? The Education Freedom Tax Credit is a new federal nonrefundable credit under Internal Revenue Code Section 25F, worth up to $1,700 for individual cash contributions to state-listed Scholarship Granting Organizations. It begins January 1, 2027 and only applies in states that have elected…

Kwong tax refund: a federal appellate courtroom weighing a COVID-era postponement claim
|

Kwong tax refund: does the COVID postponement apply?

What is the Kwong tax refund case, and does it extend the two-year deadline for COVID-era refund claims? The U.S. Court of Federal Claims held that 26 U.S.C. § 7508A(d) automatically postponed the § 6532(a)(1) refund-suit deadline for the entire COVID-19 disaster period. The government has appealed to the Federal Circuit and argues the postponement…

Business traveler and the 2026–2027 IRS per diem rates ($329 high-cost / $230 other CONUS)
|

What are the new IRS per diem rates for 2026–2027?

What are the new IRS per diem rates for 2026–2027? Notice 2026-60 sets the high-low per diem rates at $329 for high-cost localities and $230 elsewhere in CONUS, effective October 1, 2026. Transportation-industry M&IE is $80 CONUS and $86 OCONUS, and the incidental-only rate stays at $5 per day. Every October, a wave of expense-policy…

IRS Form SS-4 on a foreign founder's desk beside a passport and a laptop showing a US business bank account application.

How do I get an EIN without an SSN? (Foreign founder guide, 2026)

How do I get an EIN without an SSN as a foreign founder? You file IRS Form SS-4 by fax or by calling the International EIN line at +1-267-941-1099. An SSN or ITIN is not required for the responsible party if none exists — write “Foreign” on line 7b instead. Plan on roughly 4–8 weeks…

Livestock drought relief: dry pasture and a small herd, illustrating IRS section 1033 replacement-period extension for drought-sold livestock
|

Livestock drought relief: did IRS extend the 1033 period?

Do I get more time to replace drought-sold livestock under the 2026 IRS notice? If the county where you sold, or any contiguous county, is on the Notice 2026-54 Appendix, yes. The IRS treats the 12-month period ending August 31, 2026 as not a drought-free year, so the section 1033(e) four-year replacement period is extended…

Influencer tax: a creator's ring light and phone beside receipts and a mileage log
|

Are influencer tax rules different from other tax rules?

Are influencer tax rules any different from regular tax rules? No. The Tax Court’s first ruling involving a social-media creator, Sami v. Commissioner, applied the same ordinary-and-necessary business expense standard used for every other business. What actually decides an influencer tax audit is substantiation, business purpose, and whether the activity is a real trade or…

Year-end tax planning: a Q4 calendar and retirement statement on a high earner's desk
|

Year-end tax planning: what should high earners do in Q4?

Which year-end tax planning moves actually shift a high earner’s 2026 tax bill? The ones the Internal Revenue Code closes at midnight on December 31 — retirement contributions coded to a payroll cycle, wash-sale-safe loss harvests, exercised stock options, direct-to-charity IRA distributions, and completed annual-exclusion gifts. Year-end tax planning for high earners is less about…

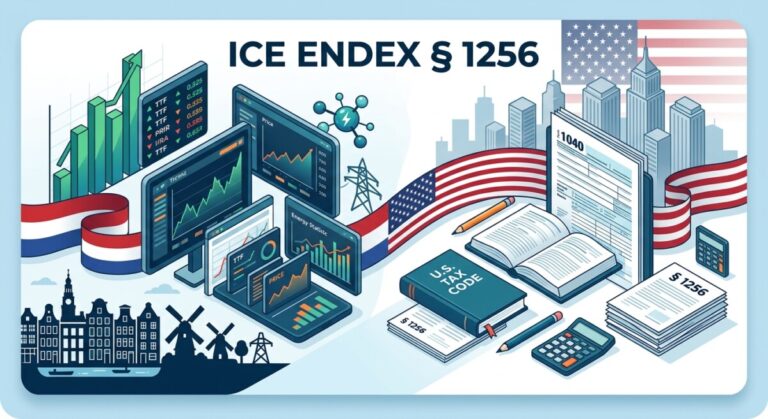
ICE Endex Section 1256: Netherlands futures exchange now qualified for U.S. mark-to-market
|

Are ICE Endex futures Section 1256 contracts? (2026)

Are ICE Endex futures Section 1256 contracts now? Yes — for contracts entered into on or after September 1, 2026. In Rev. Rul. 2026-16, the IRS determined that ICE Endex, a Netherlands regulated exchange, is a qualified board or exchange under § 1256(g)(7)(C), so its futures and futures options get mark-to-market and 60/40 capital-gain treatment…

OBBBA method change: IRS Rev. Proc. 2026-32 covers § 174 R&E and § 460(e) residential construction
|

OBBBA method change under IRS Rev. Proc. 2026-32?

Does the IRS finally have an automatic-consent path for OBBBA R&E and residential construction changes? Yes. IRS Rev. Proc. 2026-32 opens the automatic OBBBA method change for § 174, § 174A, and § 460(e), waives the usual eligibility bars through 2027, and gives one transition window that closes November 15, 2026. On September 4, 2026,…

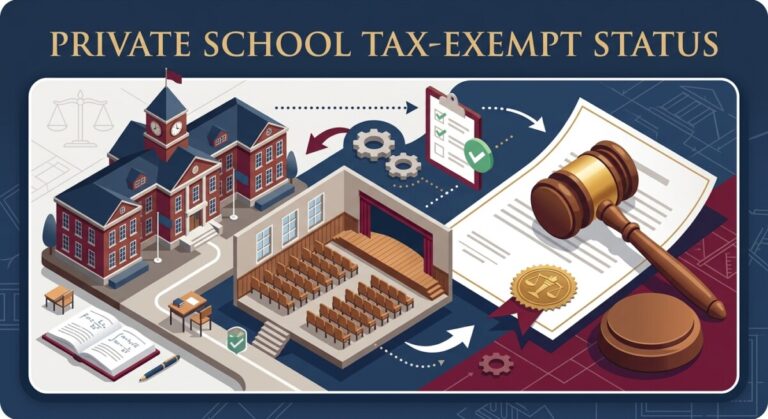
Private school tax exempt status under IRS proposed regulations — a private school campus and regulatory review

Private school tax exempt status: what changes in 2026?

Will private schools lose their tax-exempt status for racial-preference policies? Under Treasury and IRS proposed regulations issued September 3, 2026, a private school that discriminates on the basis of race, color, or national or ethnic origin would not qualify for §501(c)(3) recognition. This post explains what changes to private school tax exempt status, when, and…

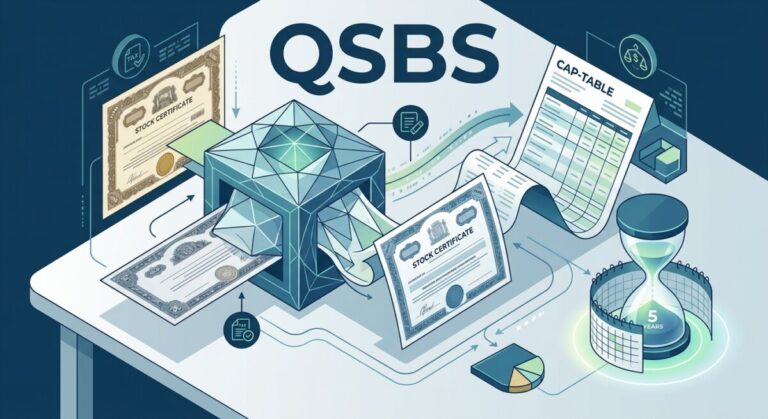
QSBS: founder's C-corporation stock reshaped in a tax-free recap without breaking Section 1202
|

How to keep QSBS treatment through a recap (2026)

How do founders keep QSBS treatment through a recapitalization? A Section 368(a)(1)(E) tax-free recap can preserve QSBS under Section 1202(h)(4)(A), but only if the reorganization requirements are met, the aggregate gross assets threshold is respected, and Section 305 does not turn the recap into a taxable deemed distribution. Many of our founder clients organize as…