Private school tax exempt status under IRS proposed regulations — a private school campus and regulatory review

Private school tax exempt status: what changes in 2026?

Will private schools lose their tax-exempt status for racial-preference policies? Under Treasury and IRS proposed regulations issued September 3, 2026, a private school that discriminates on the basis of race, color, or national or ethnic origin would not qualify for §501(c)(3) recognition. This post explains what changes to private school tax exempt status, when, and…
Illustration of OBBBA nonprofit tax rules — Capitol, donation box, university facade with IRC section tokens
|

OBBBA nonprofit tax: What changed for your 501(c)(3)?

What did the OBBBA actually change for my nonprofit? Quite a lot. The OBBBA nonprofit tax rules created a new charitable deduction for non-itemizers, added floors that shrink deductions for high-income and corporate donors, expanded the §4960 excise on high pay, and set a tiered endowment tax for large private colleges. The One Big Beautiful…

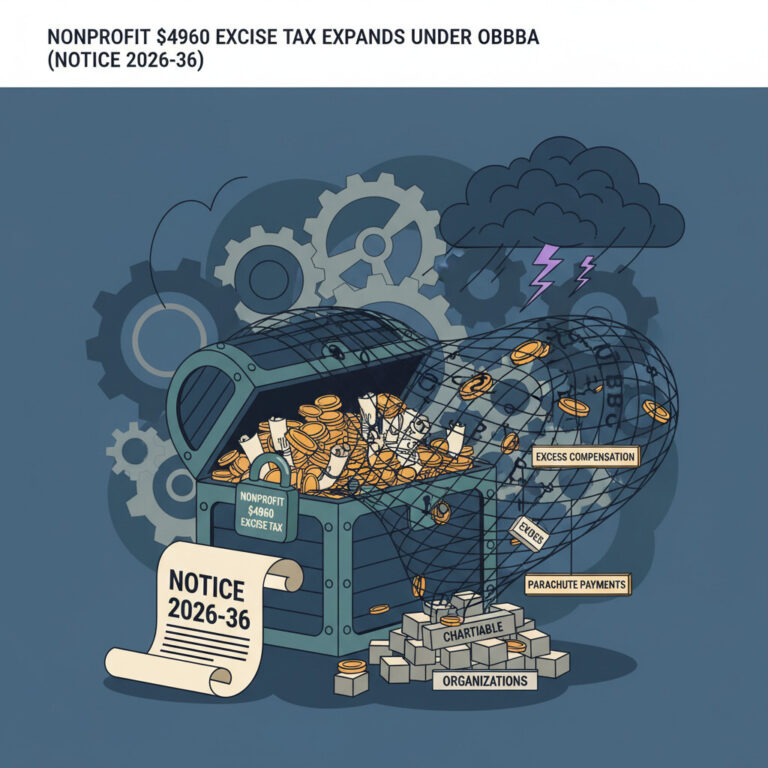
Illustration of the expanded IRC section 4960 21% excise tax on nonprofit executive compensation over $1 million under OBBBA and IRS Notice 2026-36
|

Nonprofit §4960 Excise Tax Expands Under OBBBA (Notice 2026-36)

How did OBBBA expand the §4960 excise tax on nonprofit executive compensation? Internal Revenue Code §4960 imposes a 21% excise tax on a tax-exempt organization’s “excess remuneration” — compensation over $1 million paid to a covered employee — plus certain excess parachute (separation) payments. Under the One, Big, Beautiful Bill Act, beginning with tax years…