How does a US subsidiary prepare a Korean IFRS reporting package for its parent?
What is a Korean IFRS reporting package, and why does your parent need one every month?
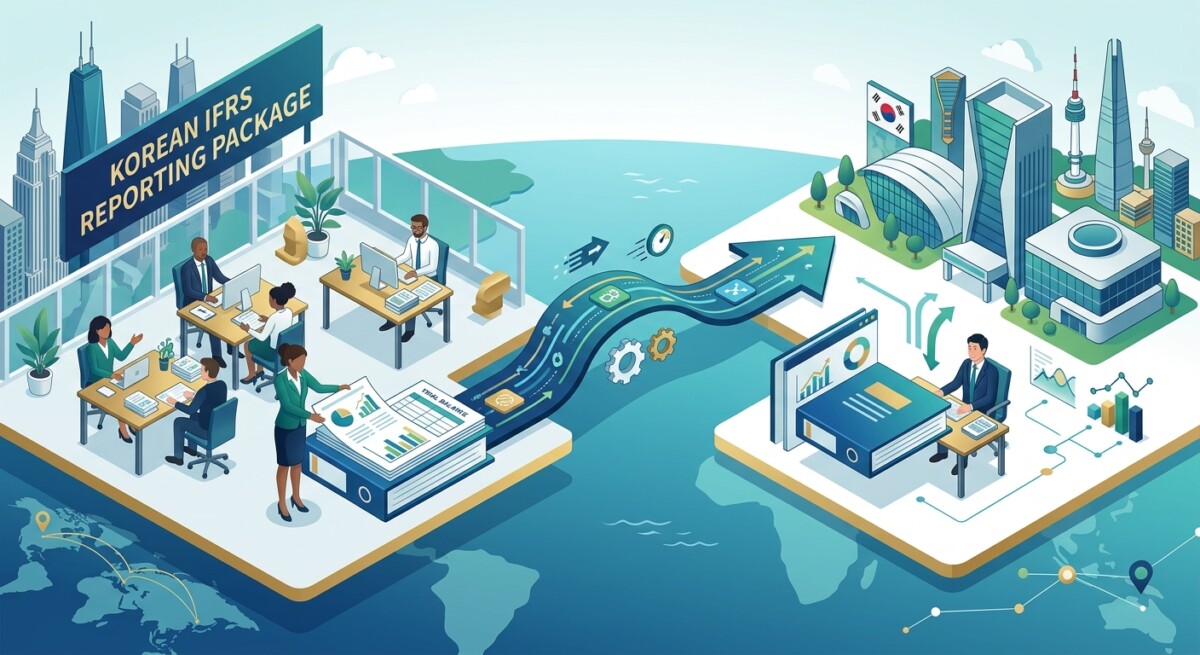
A Korean IFRS reporting package — often written K-IFRS reporting package — is the standardized monthly submission a US subsidiary sends its Korean parent so the parent can consolidate the subsidiary’s results under Korean IFRS (K-IFRS). It contains a mapped trial balance, GAAP-to-IFRS adjustments, intercompany schedules, and a KRW-translated set of statements — built from your US GAAP books, closed on the parent’s calendar, and reconciled to the parent’s ledger.
If you handle finance at a US subsidiary whose parent is a Korean listed company, your close is not really over on the day US GAAP is locked. It is over when the parent’s group controller signs off on your Korean IFRS reporting package. This is the piece most US-based accounting teams underestimate — not because it is technically hard, but because it lives in the gap between two rulebooks, two calendars, and two currencies, and no one owns the mapping until someone gets a Slack from Seoul at 6 a.m. asking why cost of sales moved.
South Korea has adopted IFRS Accounting Standards for all listed companies, and Korean audit reports use the wording “in accordance with K-IFRS” (Korean International Financial Reporting Standards) — the jurisdiction profile the IFRS Foundation publishes for South Korea makes that clear. Your parent’s consolidated statements are K-IFRS, so its subsidiaries’ contribution to those consolidated statements must be K-IFRS too — regardless of what your local books look like. That is why the reporting package exists.
What actually goes into a Korean IFRS reporting package?
At minimum: a mapped trial balance, GAAP-to-IFRS adjustments, intercompany balances and transactions, foreign currency translation, and any schedules your parent’s group controller has standardized (leases, revenue, deferred taxes, share-based payments). Everything sits on top of your US GAAP books — you are not re-keeping the ledger.
In practice the file your parent expects usually has these tabs:
- Trial balance (US GAAP) at the entity level, tied to your US general ledger.
- Account mapping that ties every US GAAP account to a K-IFRS chart-of-accounts line the parent has issued.
- GAAP-to-IFRS bridging journal entries that recur every month (leases, revenue, R&D, inventory, deferred taxes) and any one-off entries the auditor has agreed to.
- Foreign currency translation per IAS 21 — income statement at average rates, balance sheet at closing rates, equity at historical rates, with the currency translation adjustment flowing to OCI.
- Intercompany schedules: receivables, payables, revenue, cost of sales, dividends, loans and interest with the parent and any sister entities — matched to the parent’s counter-side numbers.
- Disclosure schedules: leases (IFRS 16 style — right-of-use and lease liability roll-forwards), revenue (contract balances), share-based payments, related-party transactions, contingencies.
- Roll-forwards and analytics the group controller uses to review variances: month-on-month, budget-to-actual, and prior-year comparatives.
Your parent’s consolidation is governed by IFRS 10 Consolidated Financial Statements. IFRS 10 requires the parent to use uniform accounting policies across the group when preparing consolidated financial statements. That is the technical reason your US GAAP books alone are not enough — the group has to see your numbers on the same policies it applies everywhere else, and the reporting package is the mechanism that produces those numbers.
How do you map US GAAP accounts to K-IFRS line items?
You build the mapping once, put it under change control, and only touch it when the parent updates the group chart of accounts or when you open a new US GAAP account. Most US GAAP accounts map many-to-one into a single K-IFRS line; the accounts to watch are the few whose balance has to be split across two K-IFRS lines.
The typical setup is a single spreadsheet or a mapping table inside your accounting system — every US GAAP account has a K-IFRS target line, a K-IFRS FS caption, and a note whether the mapping requires a bridging entry. Three practical rules save weeks over the year:
- Never map by memory. If a US GAAP account has no mapping row, the package build script should fail loudly, not silently push the balance into “Other.” A missing mapping caught at your desk on Day 3 costs an hour; caught by the group auditor in Q4 costs a week.
- Keep bridging entries separate from mapping. Mapping moves a balance to a different label; bridging entries change the number. Mixing the two makes it impossible to explain movements to your parent, and impossible for your auditor to test either half.
- Version the mapping. When your parent renames or splits a K-IFRS line — and they will, at least once a year — you need to know which package used which version.
Which US GAAP vs K-IFRS differences drive most of the recurring adjustments?
For an operating US subsidiary, the recurring bridging entries usually cluster around inventory costing, research and development, property, plant and equipment, leases, income taxes, and share-based payments. The specific entries depend on your business, so treat the list below as a starting checklist, not a rule set.
| Area | Where the difference typically shows up | Standards to check |
|---|---|---|
| Inventory costing | If you cost inventory on LIFO for US GAAP, the parent’s K-IFRS books cannot use LIFO — a monthly bridging entry restates cost of sales and inventory. | IAS 2 vs ASC 330 |
| R&D / development costs | Development costs meeting IFRS criteria are capitalized; the same costs may be expensed under your US GAAP policy. | IAS 38 vs ASC 730 |
| Property, plant & equipment | Component depreciation and useful-life reviews can produce a different depreciation expense than your US GAAP schedule. | IAS 16 vs ASC 360 |
| Leases | Both frameworks put most leases on the balance sheet, but a lease US GAAP classifies as an operating lease shows one straight-line lease cost, while IFRS 16 splits the same lease into depreciation of the right-of-use asset and interest on the lease liability, which front-loads total expense. | IFRS 16 vs ASC 842 |
| Income taxes | Deferred tax follows the balance-sheet approach in both frameworks, but the recognition threshold and the treatment of uncertain tax positions can differ enough to require a re-computation. | IAS 12 vs ASC 740 |
| Share-based payments | Grant-date fair value is the anchor in both frameworks, but the mechanics for graded vesting, forfeitures, and modifications require line-by-line checking. | IFRS 2 vs ASC 718 |
Whether each of those bridges actually applies to you depends on the transaction and on the accounting policy your parent has issued to the group. Two US subsidiaries with the same parent can have different recurring bridges. Ask your parent’s group controller for the group’s accounting policy manual — it will tell you which K-IFRS options the group has elected (for example, the cost model vs the revaluation model on PPE), and that decision drives your bridging entries.
How do you translate USD numbers into KRW for the package?
Under IAS 21, translate the income statement at the average rate for the period, the balance sheet at the closing rate on the reporting date, and equity at historical rates. The resulting difference is a currency translation adjustment recognized in other comprehensive income, not in P&L, and it is reclassified to profit or loss only when the parent disposes of the foreign operation (IAS 21.48).
Two decisions in IAS 21 The Effects of Changes in Foreign Exchange Rates matter before you even open a rate table:
- Functional currency. IAS 21 requires each entity to determine its functional currency based on the primary economic environment in which it operates. For most US operating subsidiaries this is USD — you sell in USD, pay staff in USD, and hold most cash in USD. Once functional currency is USD, translation to the parent’s KRW presentation currency follows the closing/average pattern above.
- The rate source. Your parent almost certainly wants rates that tie to a specific published source (for example, the daily KRW/USD base rate the group already uses in its own ledger) at consistent times of day. Agree the source in writing; you will use it every month.
Foreign currency transactions inside your US books — a KRW-denominated intercompany loan from the parent, a EUR vendor invoice — are a different exercise. They stay in your functional currency (USD), remeasured under IAS 21’s transaction rules, with any resulting FX gain or loss in P&L. Do not confuse this with the KRW translation of the package, which is a presentation step.
How do you keep intercompany balances reconciled with the parent?
Match on transaction level, not just on balances. Every intercompany line in your ledger should carry a counter-entity code, an invoice or reference number, and a document date, so that a mismatch can be traced to a specific document — not to a rounded aggregate.
The parent will run a group elimination in its consolidation. If your intercompany balance with the parent is USD 1,240,318 and the parent’s counter-side is USD 1,241,022, the group’s consolidation will not eliminate cleanly and someone (usually you) has to find the USD 704. Common causes are cutoff differences (invoice booked on Day 30 by one side, Day 1 by the other), FX rate differences on KRW-denominated intercompany items, and unrecorded intercompany interest.
A short intercompany discipline pays for itself:
- Agree cutoff with the parent in writing — usually the last business day of the month, same time zone rule for both sides.
- Run a monthly IC reconciliation before you submit the package; do not wait for the parent’s mismatch report.
- Keep IC interest accruals on a fixed schedule, not “when someone remembers.”
- For KRW-denominated IC balances, agree which side owns the FX translation for the group elimination.
Expert insight — In our practice
In our work with US subsidiaries of Korean listed groups, the single biggest source of late-cycle rework is not a technical accounting call — it is a mapping row that quietly drifted. Someone opened a new US GAAP account for a new revenue stream in Month 4, no one added a K-IFRS mapping, the balance fell into “Other operating income,” and the group auditor caught it in Month 11. Two weeks of restatement work landed on the US team’s desk right before the parent’s annual close. A boring monthly discipline — no mapping row, no post — prevents that outcome entirely.
Mapping, bridging entries and intercompany matching are where most packages go wrong. If you want a second pair of eyes on your setup, we can review it with you.
Korean Parent Reporting Package ConsultationHow do you meet the parent’s close calendar when the Korean IFRS reporting package is due?
Work back from the parent’s submission deadline, not from your US GAAP close. The parent’s group controller sets that deadline, usually as a fixed business day shortly after month-end, and quarter-end and year-end packages add disclosure schedules on top of the monthly content.
Practical scheduling notes for a US team serving a Korean parent:
- Two calendars, one clock. Korea is 13–17 hours ahead of the continental US depending on the state and daylight saving. If your parent’s group controller is at their desk at 9 a.m. Seoul, that is 4–8 p.m. the previous day for you. A submission “by end of Business Day 4” for the parent is really end of Business Day 3 for you.
- Cutoff discipline. Vendor invoices arriving on the second business day of the following month have to be caught by your accruals process, not by a rework of the submitted package.
- Quarter-end vs month-end. Quarter-end packages require full disclosure schedules (leases, revenue, taxes, share-based payments). Do not staff a quarter-end month the same way you staff a normal month.
- Year-end lead time. If the parent’s group auditor issues its list of requests in Week 1 of January, you cannot start pulling audit support in Week 3. Pre-align on the request list in Q4.
How should you handle the group auditor’s requests?
Treat the group audit as a separate, parallel workstream from your US GAAP audit — same underlying evidence, different framework, different audit team, different timeline. Standardize the evidence file once, then serve both auditors from it.
The group auditor’s job is to satisfy themselves about your subsidiary’s contribution to the parent’s consolidated K-IFRS financial statements. That means they will look at your mapping, your bridging entries, your intercompany matches, and your translation — not necessarily at every US GAAP line. A tidy evidence folder for each recurring bridging entry (policy memo, calculation, journal, tie-out to the ledger) can be sent to both audit teams with almost no rework.
Common trap — the “we’ll do it at year-end” package.
Some US subsidiaries only prepare a K-IFRS package at year-end, and submit a US GAAP file every month. Two things break. First, the parent’s monthly and quarterly consolidation quietly runs on your US GAAP numbers, so its management reporting is subtly off framework all year. Second, at year-end you compress twelve months of bridging entries and intercompany reconciliations into a two-week window, and the group auditor will not accept “we did not compute it monthly” as an answer. Monthly discipline is cheaper than year-end heroics.
Where do K-IFRS and IFRS Accounting Standards themselves diverge?
In audit reports, Korean listed companies state compliance “in accordance with K-IFRS” (Korean IFRS). The IFRS Foundation’s profile states that every IFRS Accounting Standard issued by the IASB has been endorsed as K-IFRS without modification. What Korea adds is a set of extra presentation and disclosure requirements.
The Korea Accounting Standards Board (KASB) facilitates the Korean government’s endorsement of IFRS Accounting Standards as K-IFRS. K-IFRS follows IFRS Accounting Standards issued by the IASB, and the IFRS Foundation’s South Korea jurisdiction profile lists the phrases Korean audit reports use — “in accordance with Korean IFRS”, “in accordance with K-IFRS”, and the full English form. For a US subsidiary building a reporting package, treat the package as K-IFRS unless your parent tells you otherwise, and confirm the effective version of every standard the parent is on for each reporting period. Because the Korean additions cover presentation and disclosure only, they can change the line items and schedules your parent asks for, but not the recognition and measurement behind your bridging entries.
Key takeaways for a US subsidiary building a K-IFRS reporting package
- The Korean IFRS reporting package — the K-IFRS package your parent asks for — is the monthly bridge between your US GAAP books and the parent’s consolidated K-IFRS financial statements, required because IFRS 10 forces uniform group accounting policies.
- Build it in layers: US GAAP trial balance → account mapping → recurring bridging entries → intercompany schedules → IAS 21 translation → disclosure schedules.
- Work the parent’s calendar, not your US GAAP calendar; time-zone math shifts your real deadline earlier than it looks.
- Standardize evidence once; serve both the US GAAP auditor and the group auditor from the same file.
- Do not defer the package to year-end. Monthly discipline is cheaper than a two-week year-end sprint.
How can SW Accounting help with your Korean parent reporting package?
We work with U.S. subsidiaries that have to submit their numbers to a Korean parent for K-IFRS consolidation. We can take on the whole package, or the parts your team does not have time for.
Who this is for
U.S. subsidiaries whose Korean parent consolidates under K-IFRS and asks the U.S. entity for monthly, quarterly or year-end reporting packages.
What we handle
- U.S. bookkeeping and tax — monthly books and federal and state tax filings for the U.S. subsidiary.
- Parent reporting package — account mapping, US GAAP to K-IFRS adjustments, and KRW translation schedules, prepared in the parent’s own format.
- Close adjustments and intercompany reconciliation — monthly and quarterly close entries, matched against the parent’s intercompany balances.
- Headquarters and group auditor support — answering requests from the parent’s finance team and the group auditor.
What you receive
The package in your parent’s own template: the mapped trial balance, the US GAAP to K-IFRS adjustments, the intercompany reconciliation and the KRW translation schedules, with the supporting workpapers the group auditor will ask for.
How we work
- Initial review — we look at your U.S. books, the parent’s template and its close calendar.
- Document check — we confirm the chart of accounts, the mapping and the intercompany balances.
- Scope confirmation — we agree which parts we handle and the reporting schedule.
- Recurring reporting — we prepare the package each period on the agreed schedule.
What to bring to the first consultation
The parent’s reporting template, your latest U.S. trial balance, and the parent’s close calendar. A previous package, if you have one, helps too.
Based in Los Angeles, we work remotely with clients across the United States.
Korean Parent Reporting Package Consultation
Frequently asked questions about the Korean IFRS reporting package
Does every US subsidiary of a Korean company need a Korean IFRS reporting package?
If the Korean parent is listed on the Korea Exchange’s KOSPI or KOSDAQ market (KONEX companies are not required to use K-IFRS) and prepares consolidated financial statements, yes — the subsidiary’s numbers must be available on the parent’s accounting framework (K-IFRS) for consolidation under IFRS 10. If the parent is a private Korean company that reports on K-GAAP (Korean generally accepted accounting principles for non-listed entities) rather than K-IFRS, the framework of the reporting package changes, but the mechanics — trial balance, mapping, bridging entries, translation, intercompany — are essentially the same.
Can we just send our US GAAP financial statements and let the parent adjust them?
In practice this does not work at scale. The parent does not have visibility into your inventory system, your lease population, your R&D contracts, or your compensation grants. Any bridging entry the parent tries to compute from a summary trial balance will be approximate, and any group audit finding lands back on the US team anyway. The reporting package is the mechanism that pushes the bridging work to the entity that actually has the data.
Which US-side software do we need to produce the package?
Most US subsidiaries of Korean groups run the package on their existing US GAAP ERP or GL plus a controlled spreadsheet layer for mapping, bridging entries, translation, and disclosure schedules. Some parents use a consolidation tool that the subsidiary submits into directly; if so, the parent will hand you a template and the software choice is decided at the group level. Do not build a bespoke tool before you have proved the process manually for a full quarter.
Do we use the average rate or the closing rate for revenue in the package?
Under IAS 21, income and expenses of an entity whose functional currency is not the presentation currency are translated at the exchange rates at the dates of the transactions — in practice, an average rate for the period is used as an approximation. Balance-sheet items are at the closing rate. That is why translating a full-year income statement at the December 31 closing rate is not correct — it will produce a different KRW result and a currency translation adjustment that the group auditor will question.
Who owns the FX gain and loss on a KRW-denominated intercompany loan from the parent?
If your functional currency is USD and the intercompany loan is KRW-denominated, you remeasure the loan at each closing rate and the exchange difference runs through your P&L under IAS 21. The parent’s receivable is in its own functional currency (KRW), so nothing on its side offsets your difference, and IAS 21.45 keeps it in consolidated profit or loss even after the intercompany balance itself is eliminated. The exception is a loan whose settlement is neither planned nor likely in the foreseeable future: IAS 21.15 treats it as part of the parent’s net investment in your company, and IAS 21.32 moves the exchange difference to other comprehensive income in the consolidated statements, while it stays in P&L in your own. Agree in writing with the parent’s group controller which case applies to each loan — this is one of the most common sources of late-cycle intercompany mismatch.
How long does it usually take to stand up a new Korean IFRS reporting package?
For a newly acquired US subsidiary with clean US GAAP books and a cooperative parent, three to four months to a stable monthly rhythm is realistic — one month to build the mapping and identify recurring bridges, one to run in parallel with the parent’s expected numbers, and one to have the group auditor look at it. A messier starting position (weak US GAAP close, no group chart of accounts, no functional currency documentation) can double that.