ICE Endex Section 1256: Netherlands futures exchange now qualified for U.S. mark-to-market
|

Are ICE Endex futures Section 1256 contracts? (2026)

Are ICE Endex futures Section 1256 contracts now? Yes — for contracts entered into on or after September 1, 2026. In Rev. Rul. 2026-16, the IRS determined that ICE Endex, a Netherlands regulated exchange, is a qualified board or exchange under § 1256(g)(7)(C), so its futures and futures options get mark-to-market and 60/40 capital-gain treatment…
QSBS: founder's C-corporation stock reshaped in a tax-free recap without breaking Section 1202
|

How to keep QSBS treatment through a recap (2026)

How do founders keep QSBS treatment through a recapitalization? A Section 368(a)(1)(E) tax-free recap can preserve QSBS under Section 1202(h)(4)(A), but only if the reorganization requirements are met, the aggregate gross assets threshold is respected, and Section 305 does not turn the recap into a taxable deemed distribution. Many of our founder clients organize as…

Net unrealized appreciation illustration: employer stock leaving a 401(k) for a taxable brokerage account
|

What is Net Unrealized Appreciation (NUA)? 401(k) Guide

What is Net Unrealized Appreciation (NUA), and could it lower my 401(k) tax bill? Net unrealized appreciation is a federal tax election under IRC §402(e)(4)(B) that lets you move employer stock out of a qualified retirement plan and pay ordinary income tax only on the stock’s original cost basis. The built-in gain is then taxed…

Illustration of a Section 1031 like-kind exchange — two investment buildings with a swap arrow and a deadline calendar showing the 45-day and 180-day rules
|

Section 1031 Exchange: Defer Tax on Investment Real Estate

Can you defer tax when you sell investment property? Often, yes. A Section 1031 exchange lets you defer capital gains tax when you swap real property held for business or investment for like-kind real property. The trade-off: strict deadlines — 45 days to identify a replacement and 180 days to close — and, since 2018,…

Illustration of Qualified Opportunity Zones under IRS Notice 2026-40 — a city skyline on a map pin with a 2026 calendar marking the deferred-gain inclusion deadline
|

QOZ Update: IRS Notice 2026-40 and the Dec 31, 2026 Deadline

Are the Opportunity Zone rules changing? Yes. In IRS Notice 2026-40, the Treasury Department and the IRS announced that they intend to issue proposed regulations on Qualified Opportunity Zones under Internal Revenue Code §§ 1400Z-1 and 1400Z-2, as amended by the One, Big, Beautiful Bill Act (OBBBA). The notice provides transitional guidance for investments made…

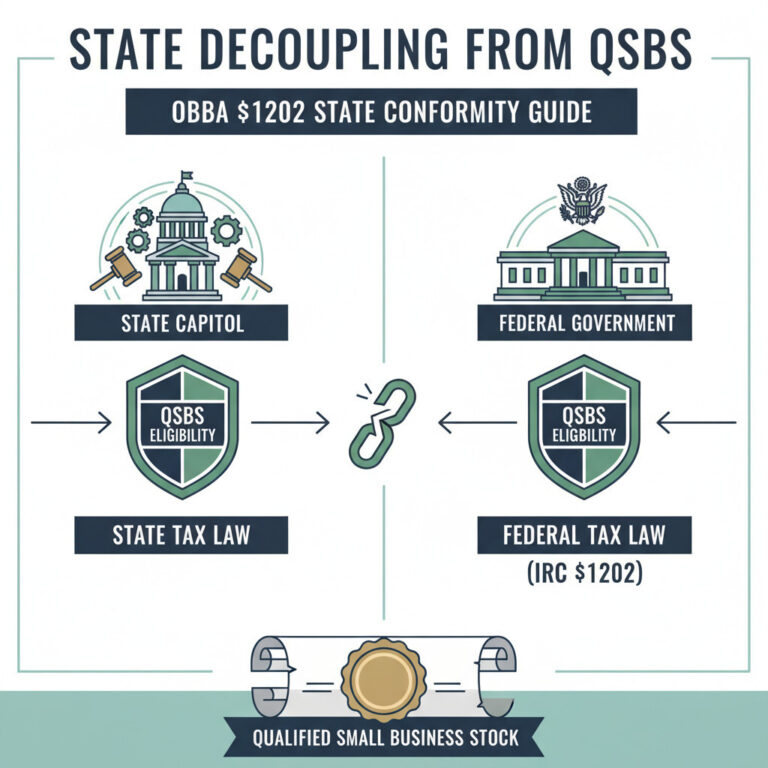
Illustration of state decoupling from federal QSBS section 1202 exclusion under OBBBA — Maine and Oregon decoupled, California taxes QSBS gains, state conformity risk for founders
|

State Decoupling from QSBS: OBBBA §1202 State Conformity Guide

Do states follow the federal QSBS exclusion under OBBBA — and why does state conformity matter? Not automatically. The One Big Beautiful Bill Act (OBBBA, Pub. L. No. 119-21) expanded the federal Qualified Small Business Stock (QSBS) exclusion under IRC §1202 — but states set their own conformity. Maine and Oregon have enacted legislation DECOUPLING…