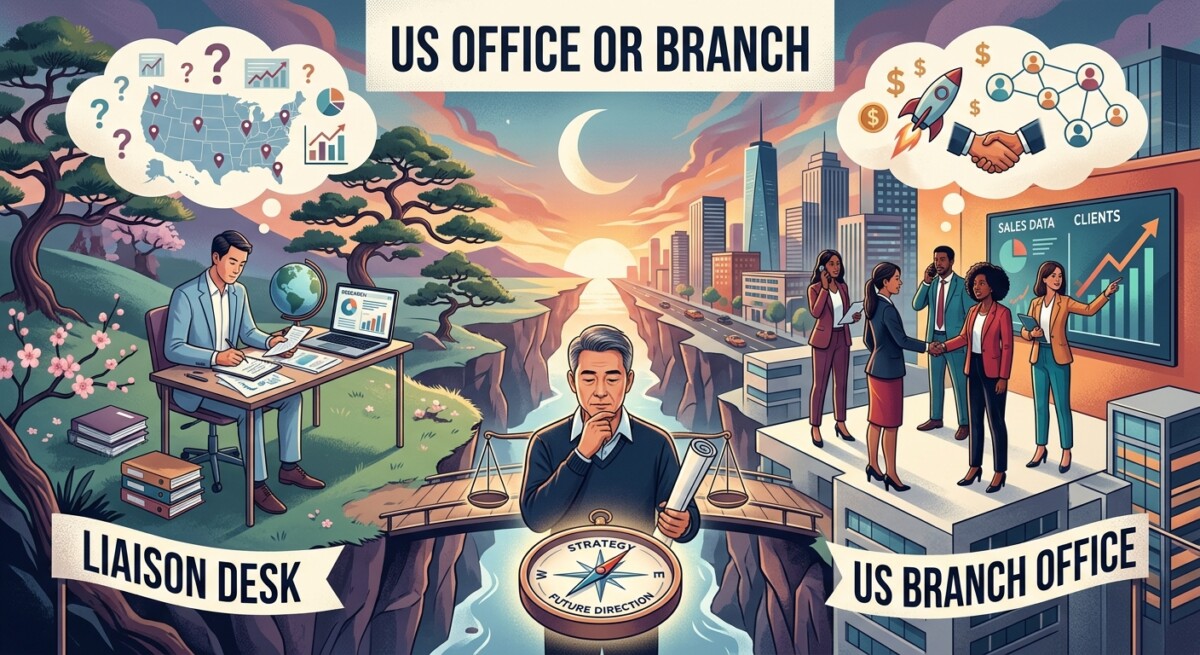
US representative office vs branch: what should a Korean parent set up?
You already run the Korean parent, you cleared the OBBBA headlines, and now a US customer wants a quote. Before you hire the first US person or sign the first US contract, you have to decide what the IRS will see on the other side of your door: a us representative office vs branch is not a cosmetic label — it changes whether the US treats you as a taxpayer, whether you file Form 1120-F, and whether a 30% branch profits tax can apply on top of the 21% corporate rate. This guide walks a Korean parent through the US side of that decision using only primary sources — the Internal Revenue Code, Treasury Regulations, IRS forms, and the US–Korea Income Tax Convention.
In our practice, the Korean parents who get burned are not the ones who deliberately picked the wrong structure — they are the ones who opened a “liaison office” to park two engineers and then quietly let a sales manager close deals from the same desk. The IRS looks at what happens, not at what the sign says. Everything below assumes you want the label and the reality to match.
What is a US representative office, and when does the IRS stop ignoring it? 🧭
A US representative office is a liaison outpost that does only preparatory or auxiliary work for the Korean parent, and the IRS leaves it alone until that work crosses into a US “trade or business” under IRC §864(b).
The pivot in US tax is the phrase “trade or business within the United States.” Under IRC §864(b) and Treas. Reg. §1.864-2, activities that are “considerable, continuous, and regular” in the US generally rise to that level. Pure information gathering, market research, back-office support, or quality monitoring usually does not. Section 864(b)(2) also carves out trading in stocks, securities, and commodities for the foreign corporation’s own account — a Korean parent that only parks a trader in the US to buy US securities for its own portfolio is not, by that activity alone, in a US trade or business.
The treaty tightens the standard further. Under Article 9 of the US–Korea Income Tax Convention (and the Convention’s permanent establishment article), a fixed place of business maintained solely for storage, display, purchasing, information gathering, or other activities of a preparatory or auxiliary character does not constitute a permanent establishment. If a Korean resident company has no US permanent establishment, Article 8 of the Convention generally bars the US from taxing its business profits. A properly scoped representative office is designed to live inside this safe box.
What is a US branch, and how is it taxed? 💼
A US branch is a foreign corporation doing business in the US without using a separate US legal entity — it files Form 1120-F, pays US corporate tax on effectively connected income, and may owe a separate branch profits tax under IRC §884.
Once a Korean parent has a US trade or business, IRC §882(a) taxes the income effectively connected with that trade or business (“ECI”) at the regular US graduated corporate rates — currently a flat 21% federal corporate rate under IRC §11 — the same rate a US-formed C corporation would pay. The branch has to file Form 1120-F annually, and the regulations under Treas. Reg. §1.864-4 drive what gets pulled into ECI versus what stays outside the US net.
The second layer is the branch profits tax. IRC §884 adds a 30% tax on the branch’s “dividend equivalent amount” — essentially the after-tax earnings the branch sends, or is deemed to send, back to the Korean parent. The 30% rate can be modified by an income tax treaty if the foreign corporation is a “qualified resident” under IRC §884(e) and Treas. Reg. §1.884-5. Because the US–Korea Convention was negotiated before §884 existed, how §884 interacts with it is fact-specific; the primary-source text to consult is the Convention itself, published by Treasury and distributed through the IRS treaty page cited above, and the §884(e) regulations. A branch that pays a treaty-based rate under §884 generally has to disclose the position on Form 8833.
How do a US representative office and a US branch compare in practice? 📊
A representative office lives outside US corporate tax but must stay strictly inside preparatory and auxiliary activities; a branch files US tax returns, pays 21% on ECI, may owe branch profits tax, and reaches your Korean parent’s assets directly.
| Item | US representative office | US branch |
|---|---|---|
| US trade or business (IRC §864(b)) | No, if strictly preparatory/auxiliary | Yes |
| Permanent establishment under US–Korea Treaty | Generally no | Generally yes |
| Federal corporate tax (IRC §882 / §11) | Not applied | 21% on ECI |
| Form 1120-F filing | Not required if no ECI and no US trade or business (protective filing may still be advisable) | Required annually |
| Branch profits tax (IRC §884) | Not applied | 30% statutory; treaty analysis required under §884(e) |
| EIN (Form SS-4) | Usually obtained for banking and payroll | Required |
| Liability of the Korean parent | Direct — no separate US entity | Direct — no separate US entity |
| State registration (foreign qualification) | Depends on the state and the activity | Generally required where business is done |
Expert insight — our CPA practice note 💡
In our practice, the Korean parents who stay safely inside the “representative office” box have one thing in common: no US person on their payroll ever quotes a price, signs a US contract, or receives US customer payments. The second any of those three happens, we move the client to a Form 1120-F branch filing or, more often, to a US C-corporation subsidiary — because once you are inside US tax, a subsidiary gives you something a branch does not: a legal firewall between the US business and the Korean parent’s balance sheet. The decision point is almost never “which structure sounds nicer”; it is “where will the signing happen, and who will the US customer invoice?”
What filings and registrations does each structure trigger? 📝
A representative office typically needs an EIN and may need state foreign qualification, but no federal income tax return; a US branch files Form 1120-F, withholds and reports under FDAP rules, and discloses treaty positions on Form 8833.
On the federal side, a true representative office with no ECI and no US trade or business will not file Form 1120-F for income tax, but there are two situations where a protective filing is still worth considering. First, if the characterization is ever close, filing a protective Form 1120-F preserves the branch’s deductions in case the IRS later asserts a US trade or business — the regulations under Treas. Reg. §1.882-4 condition deductions on filing a true and accurate return within the required time. Second, if the Korean parent has any US-source FDAP (interest, dividends, royalties), a withholding agent still has to withhold 30% under IRC §1442 and §1441, unless the treaty reduces the rate — see IRS Publication 515 for the mechanics.
A US branch has heavier compliance. In addition to Form 1120-F for income tax on ECI, the branch generally files Form 5472 for reportable transactions with foreign related parties (think: expense reimbursements and intercompany services with the Korean parent), Form 8833 to disclose any treaty-based position, Form W-8ECI to tell US withholding agents the income is effectively connected, and payroll returns (Forms 941, 940, W-2) once there are US employees. States layer on their own corporate franchise and income tax returns; see the California Franchise Tax Board for one commonly encountered state’s rules. None of these go away because the business is small.
Warning — the “liaison office that quietly sells” trap ⚠️
The most common exam issue we see is a representative office whose name never changed, but whose activities drifted into contract negotiation, pricing authority, or regular invoicing. The IRS does not have to buy the label — the regulations look at the facts. If an exam reclassifies the office as a US branch, every year of unreported ECI can be reopened, deductions can be denied under Treas. Reg. §1.882-4 for failing to file a timely return, and treaty positions can be stripped for failing to disclose on Form 8833. Reviewing the office’s actual activities at least once a year — before a US customer forces the question — is cheap insurance.
Should I set up a US subsidiary instead of a branch? 🏢
Once the US activity is real revenue, most Korean parents move past the us representative office vs branch choice entirely and open a US C-corporation subsidiary — same 21% federal rate, but limited liability and a cleaner treaty profile.
A US subsidiary — typically a Delaware C-corporation — gives three things a branch does not. It legally separates US business risk from the Korean parent’s balance sheet. It replaces the branch profits tax with the ordinary withholding tax on dividends under IRC §881 and the US–Korea Convention (a reduced rate under the Convention’s dividend article), which is easier to model. And it eliminates the Form 1120-F / §884 overlay with a clean Form 1120 return. The trade-off is that intercompany transactions with the Korean parent — management fees, royalties, cost-sharing, loans — have to be at arm’s length under IRC §482 and the regulations, and the subsidiary has to meet the IRC §6038A reporting rules via Form 5472.
A branch still has a legitimate role when the US operation is temporary, when you want US losses to flow directly against Korean parent income (subject to the dual consolidated loss rules of IRC §1503(d)), or when a single-entity presentation matters more than the §884 cost. Our usual flow is: representative office while you learn the market, subsidiary once you intend to sign US contracts for more than a quarter. Branches are the middle path, and they usually last only until the finance team sees two years of §884 and Form 1120-F work on top of the Form 1120 the subsidiary would have filed anyway.
Summary — the three things to carry out of this guide
- A US representative office stays outside US income tax only while its activities are preparatory or auxiliary under IRC §864(b) and the US–Korea Convention — contract signing, pricing, and invoicing break the box.
- A US branch pays 21% US corporate tax on ECI under IRC §882 and may owe a separate 30% branch profits tax under IRC §884, modified by careful §884(e) treaty analysis.
- A Delaware C-corporation subsidiary is usually the right next step once US activity is real revenue — same federal rate, cleaner treaty profile, and a liability firewall for the Korean parent.
Frequently asked questions ❓
Q1. If my US representative office only has two engineers doing R&D for the Korean parent, do I file Form 1120-F?
If the engineers’ activities are strictly preparatory or auxiliary and there is no US-source income effectively connected with a US trade or business, no Form 1120-F is required under IRC §882. A protective Form 1120-F may still be filed to preserve deductions under Treas. Reg. §1.882-4 if the characterization is ever contested.
Q2. Does the US–Korea tax treaty eliminate the branch profits tax for a Korean parent’s US branch?
Not automatically. IRC §884(e) controls when a treaty can reduce or eliminate the branch profits tax, and the Korean parent must be a “qualified resident” under IRC §884(e)(4) and Treas. Reg. §1.884-5. Because the US–Korea Convention predates §884, the position is fact-specific and should be run with a US CPA before it is relied upon; the Convention text on the IRS treaty page is the primary source.
Q3. Can my US representative office sign a non-disclosure agreement with a US customer?
A pure NDA that supports market research or information gathering generally stays inside the preparatory/auxiliary safe harbor. The moment the office negotiates, prices, or signs a commercial contract (even a letter of intent that effectively binds the parent), the activity can be reclassified as a US trade or business under the facts and circumstances test in Treas. Reg. §1.864-2.
Q4. If I convert the representative office into a US branch mid-year, what happens to prior-year activity?
The branch filing starts prospectively, but if the IRS later finds that US trade or business existed in earlier years, prior-year ECI can be assessed with interest. Running an activity review before the conversion lets you file protective Forms 1120-F for any closed exposure years and avoid losing deductions under Treas. Reg. §1.882-4.
Q5. Is a US subsidiary always better than a US branch for a Korean parent?
In most going-concern cases, yes — the subsidiary firewalls the Korean parent from US liabilities and replaces the branch profits tax with a treaty-rate dividend withholding under the US–Korea Convention. A branch can still win for short-lived US projects, or when the Korean parent needs to use US losses against Korean income (subject to the dual consolidated loss rules under IRC §1503(d)).
Q6. Does the Korean parent need an EIN even without US tax filings?
Yes, in practice — US banks, payroll providers, and state registration authorities require an EIN from the IRS before they will open accounts or process foreign qualification. The EIN itself does not create a US tax filing obligation; it is identification.