What are the new Opportunity Zones for 2027?
A client with a seven-figure capital gain from a business sale is already asking which Opportunity Zone to invest in. Six months ago, we did not have a current answer — the second round of designations had not been made yet, and the first round was scheduled to expire. That changed on November 5, 2026, when the IRS and Treasury published IRS news release IR-2026-132 announcing 6,576 newly designated Opportunity Zones effective January 1, 2027. The program is now permanent, the map has been redrawn, and rural communities received a thicker slice than last time. This post walks through what the designation actually does, who was named, and what the tax incentive looks like after the latest round of changes.
What did the IRS and Treasury announce about Opportunity Zones on November 5, 2026? 📰
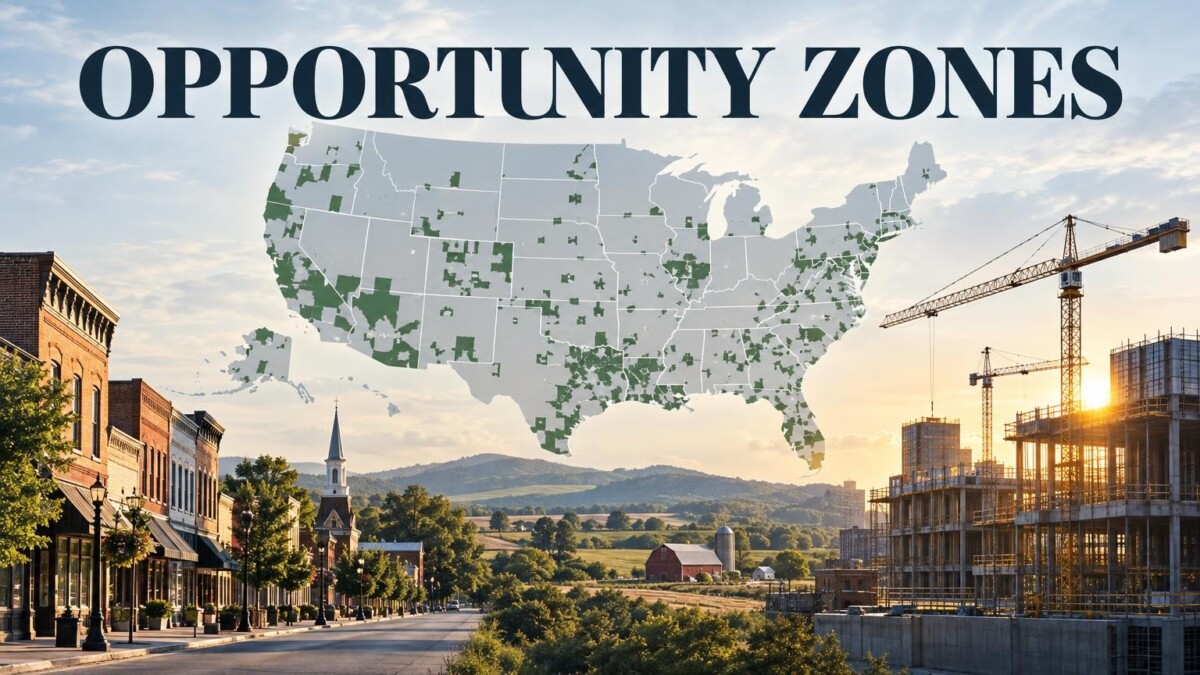
The IRS and Treasury designated 6,576 census tracts across all 50 states, five territories, and the District of Columbia as Qualified Opportunity Zones effective January 1, 2027, under news release IR-2026-132.
The November 5 announcement is the final step in a process set out under IRC §1400Z-1 for the program’s second round of designations. Treasury published the master list of 25,332 eligible census tracts on April 6, 2026, began accepting nominations from governors and the Mayor of the District of Columbia on July 1, and closed the nomination window after 6,576 tracts had been submitted. All 6,576 nominated tracts were approved — the statutory selection process used in this round did not require Treasury to cut the list.
The new designations displace the 2018 cohort rather than running alongside it. Investments already placed with Qualified Opportunity Funds tied to the 2018 zones keep their original tax treatment, but new investments made after the January 1, 2027 effective date should target tracts on the new list. The full map is available on the CDFI Fund Opportunity Zones list and map, with underlying census tract files and poverty-rate data on the Treasury’s Qualified Opportunity Zones data page.
One number in the release is worth sitting with: since the 2017 Tax Cuts and Jobs Act created the program, the IRS and Treasury report more than $110 billion of private-sector capital has been placed through Qualified Opportunity Funds. The 2026 law makes the incentive permanent — the single biggest structural change in the announcement — so sponsors who were waiting to see whether the program would survive the sunset now have an answer.
Who nominated the new Opportunity Zones, and which ones are rural? 🌾
State governors and the Mayor of the District of Columbia nominated tracts within their own jurisdictions from a Treasury-published list of 25,332 eligible census tracts. Of the 6,576 final designations, 2,594 are in rural areas and qualify for enhanced incentives.
The nomination mechanics matter because they decide which neighborhoods, towns, and reservation lands end up on the list. Each state had a cap tied to the number of its eligible low-income census tracts, and governors made their picks based on local economic development priorities. Several states nominated tracts near planned infrastructure projects, Tribal lands, downtown revitalization districts, and rural county seats that had struggled to attract capital under the 2018 round.
The rural emphasis is new. In the first round, rural and urban tracts received the same tax treatment. Under the 2026 Working Families Tax Cuts legislation, tracts located in eligible rural areas qualify for enhanced incentives — the specific statutory adjustments are codified in the latest amendments to IRC §1400Z-2 and will be the subject of forthcoming Treasury regulations. Of the 25,332 eligible tracts published in April, 8,334 sat in rural areas; the final designation list ended up at a 39% rural share, a sharp increase from the first round.
For investors, the practical consequence is that a 2027 QOF strategy will frequently sit in rural markets — small manufacturing towns, agricultural logistics hubs, timber and energy regions — rather than the urban opportunity zones that drew most of the 2018 round’s attention.
When do the new Opportunity Zones take effect — and how long do they last? 🗓️
Effective January 1, 2027. The designations run for ten years under IRC §1400Z-1, and the statute provides for redesignation every ten years on a permanent cycle.
The ten-year term is not a marketing promise — it is in the statute. Under IRC §1400Z-1, a Qualified Opportunity Zone designation remains in effect for ten calendar years from the date it takes effect. Because the new designations become effective January 1, 2027, they expire at the end of 2036, after which Treasury will run the next nomination round under the same statutory framework.
For clients already invested in 2018-round zones, the transition is clean on paper and messy in practice. The deferral and exclusion rules under IRC §1400Z-2 attach to the investment, not to the zone itself, so an investment made in 2019 in a 2018-designated tract keeps its full ten-year holding period even if that same tract is not on the 2027 list. What changes is the geography of new investment: any gain rolled into a QOF after January 1, 2027 must be deployed into property or a business located in a tract on the new designation list.
Verify the census tract before you sign
Opportunity Zone designations run by 11-digit FIPS census tract, not by zip code, city, or street address. A property across the street from a qualifying tract gets nothing. The CDFI Fund map lets you enter an address, but we always cross-check the resulting tract number against the official list on Treasury’s data page before a client wires money into a QOF.
How does the Opportunity Zone tax incentive actually work? 📊
Under IRC §1400Z-2, you can defer tax on a capital gain by reinvesting it in a Qualified Opportunity Fund within 180 days, and you can exclude from tax any appreciation on that fund investment if you hold it for at least ten years.
Stripped to the mechanics, the incentive has two parts. First, any capital gain you realize from the sale of an appreciated asset can be rolled into a Qualified Opportunity Fund — a corporation or partnership that holds at least 90% of its assets in qualifying zone property — within 180 days. The deferred gain is not recognized until the QOF investment is sold or exchanged, or until an outside deadline set by statute, whichever comes first. Second, if the QOF investment is held for at least ten years, any post-rollover appreciation in the QOF investment itself is excluded from tax when sold.
| Step | What has to happen | Tax effect |
|---|---|---|
| 1. Realize a capital gain | Sale of stock, business, real estate, or other capital asset produces a recognized gain. | Gain is normally taxable in the year of sale. |
| 2. Invest in a QOF within 180 days | Reinvest the amount of the gain in a Qualified Opportunity Fund organized as a corporation or partnership. | Gain is deferred; basis in the QOF starts at zero. |
| 3. Hold the QOF investment | QOF must hold ≥90% of assets in qualifying zone property. Investor’s QOF stake is held through the deferral period. | No current tax; QOF appreciation builds. |
| 4. Sell after ten years | Hold the QOF investment for at least ten years, then sell. | Appreciation on the QOF stake is excluded from tax under §1400Z-2(c). |
The 2026 Working Families Tax Cuts legislation kept this structure intact and permanently renewed the program. It also added enhanced benefits for rural-zone investments and set the ten-year redesignation cycle. Several technical features of the original 2017 program — most notably the five- and seven-year basis step-ups that depended on holding periods expiring before specific calendar dates — were restructured to track the new permanent cycle rather than fixed sunset dates.
From our practice: QOFs are a timing tool, not a tax shelter
In our practice, Opportunity Zones work for a specific kind of client — someone who has just realized a large capital gain and wants to reinvest it in productive property or an operating business for at least a decade. For that client, the deferral plus the ten-year exclusion is material. Clients who go in looking for a shelter usually leave the meeting looking for a different strategy. The money has to be at risk, in real zone property or a real zone business, for a real ten years.
What should investors and business owners do before January 1, 2027? ✅
Match the property or business you are considering to the new designation list, decide whether to deploy in 2026 (old zones) or 2027+ (new zones), and get your Qualified Opportunity Fund organized before you have to invest.
- Pull the census tract for every property in your pipeline. Use the CDFI Fund Opportunity Zones list and map to confirm each tract’s status as of January 1, 2027. Properties that were in a 2018 zone but not a 2027 zone need a different plan.
- Decide whether a 2026 or a 2027 fund is the right vehicle. If you have a gain to invest within the 180-day window and you already have a line of sight to property in a 2018 zone, deploying before year-end preserves the old zone. If your gain is still in 2026 but the property you want is on the new list, the new designation effective date is January 1, 2027.
- Confirm the rural status if you are chasing the enhanced incentives. The rural-zone benefits added by the 2026 legislation only apply to tracts in eligible rural areas. The CDFI Fund list tags each tract’s rural or urban classification.
- Get the fund structure right at the outset. A Qualified Opportunity Fund is a corporation or partnership that self-certifies on Form 8996. Testing dates, the 90% asset requirement, and the substantial improvement rules for existing property are easy to miss in the first year.
- Document the gain, the 180-day clock, and the reinvestment. The deferral under §1400Z-2 only applies to the amount of the capital gain, within 180 days of the sale. Keeping the timeline clean is what the IRS is going to look at on audit.
Summary: Opportunity Zones in 2027
- The IRS and Treasury designated 6,576 new Opportunity Zones effective January 1, 2027, in IR-2026-132.
- 2,594 of the newly designated tracts are in rural areas eligible for enhanced incentives.
- The program is now permanent, with redesignation every ten years under IRC §1400Z-1.
- The core tax incentive under IRC §1400Z-2 — gain deferral plus a ten-year exclusion — is unchanged.
- Investments in the 2018 zones keep their original treatment; new 2027+ investments should target the new designation list.
Frequently asked questions about the new Opportunity Zones ❓
Q. What are the new Opportunity Zones for 2027?
They are 6,576 low-income census tracts designated by the IRS and Treasury on November 5, 2026 under IRS news release IR-2026-132. The new designations become effective January 1, 2027 and remain in effect for ten years. 2,594 of the designated tracts are in rural areas eligible for enhanced incentives. The current designations from the 2018 round expire at the end of 2028, so most of 2027 and 2028 is a transition period where both lists matter.
Q. Where can I find the list of designated Opportunity Zones for my state?
The CDFI Fund publishes the official list and interactive map at cdfifund.gov/opportunity-zones. Treasury also maintains a data page with the underlying census tract files at home.treasury.gov. The list is organized by state and by census tract (the 11-digit FIPS code), not by street address, so you match a property by looking up its census tract first.
Q. How does the Opportunity Zone tax incentive actually work?
Under IRC §1400Z-2, if you have a capital gain from a sale, you can reinvest that gain in a Qualified Opportunity Fund within 180 days and defer the tax on the original gain. Any new appreciation on the QOF investment is excluded from tax if the investment is held for at least ten years. The new 2026 law makes the program permanent and adds enhanced benefits for rural-zone investments, but the basic structure — gain deferral plus a ten-year exclusion — is unchanged.
Q. Who nominated these Opportunity Zones?
State governors nominated eligible census tracts within their states, and the Mayor nominated tracts in the District of Columbia. Treasury and the IRS released the master list of 25,332 eligible census tracts on April 6, 2026 and began accepting nominations on July 1, 2026. 2,594 of the final 6,576 designations are in rural areas, which qualify for enhanced incentives under the Working Families Tax Cuts.
Q. When do the new Opportunity Zones take effect?
January 1, 2027. The designations run for a full ten years, so they remain in effect through 2036 under IRC §1400Z-1, with redesignation every ten years built into the statute. The original 2018 designations continue to apply for investments placed in service before the 2027 effective date, which means investors have a planning window in 2026 to decide which cohort of zones to use.
Q. Do the old 2018 Opportunity Zones still work in 2027?
The 2018 zone list is being replaced, not extended. Qualified Opportunity Fund investments already made in the old zones keep their deferral and ten-year exclusion treatment under the original rules. New investments after the 2027 effective date should target tracts on the new designation list; investors should confirm the census tract against the CDFI Fund list before signing a purchase agreement.
This article is general information, not tax or legal advice for your situation. Opportunity Zone investments depend heavily on the specific property, the structure of the fund, and the taxpayer’s capital-gain timeline. Contact SW Accounting & Consulting Corp for a confidential review.