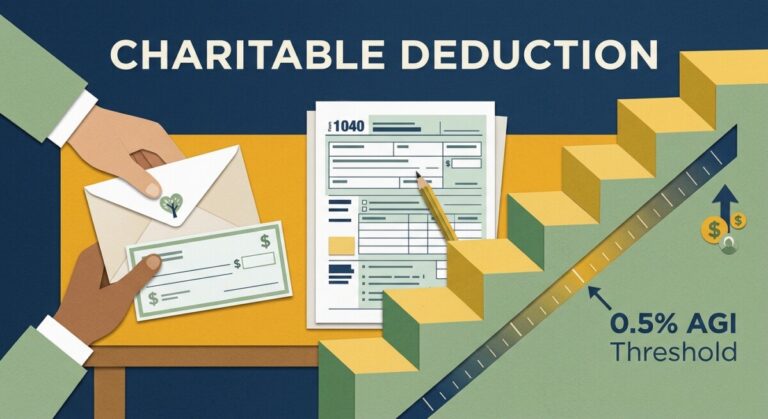
Charitable deduction under OBBBA: a donation envelope beside a tax form and a rising threshold shape
|

How does OBBBA change the charitable deduction in 2026?

Does OBBBA change the charitable deduction in 2026? Yes. Starting with the 2026 tax year, a new 0.5%-of-AGI floor and a 2/37ths cap on itemized deductions reduce the charitable deduction for most itemizers, but a new $2,000 above-the-line deduction and qualified charitable distributions give donors ways around them. Every November, a client calls our Los…
Premium tax credit under OBBBA: a 1095-A form, a calculator, and marketplace enrollment reconciled on a desk
|

What are the new premium tax credit rules under OBBBA?

What are the new premium tax credit rules under OBBBA? The IRS and Treasury have issued proposed regulations (REG-101576-26) implementing H.R. 1 changes to Section 36B — the premium tax credit. The dollar cap on repayment of excess advance credits is gone starting with 2026 returns, new marketplace verification rules kick in after 2027, and…

Employee tax benefits: a US small business reviewing its 2026 benefits package
|

Employee tax benefits 2026: What can my business offer?

What employee tax benefits can my business offer in 2026? The federal tax code pays for a surprising share of a competitive benefits package. The right employee tax benefits can lower a small employer’s net cost of paid leave, education, child care, retirement savings, and even a new Trump Account, through credits and exclusions that…

Clean fuel credit under section 45Z: IRS Notice 2026-53 and the OBBBA amendments
|

Does the clean fuel credit still cover my fuel in 2026?

How does the clean fuel credit work after the OBBBA? The clean fuel credit under § 45Z still rewards low-emissions transportation fuel produced in the United States, but IRS Notice 2026-53 reshapes it for 2026. ILUC emissions are out. Non-North American feedstocks are out. Animal manure gets its own emissions rate. Here is what to…

Editorial illustration of a US Capitol dome silhouette next to a stylized federal tax document

Federal tax update: TAS Act, OZ, and OBBBA

This federal tax update covers three developments that reach small and mid-sized business owners directly. Congress moved a bipartisan taxpayer service package out of committee, Treasury opened a comment window on the renewed opportunity zone rules under the OBBBA, and the Joint Committee on Taxation corrected four points in its own OBBBA technical explanation —…

Car loan interest deduction: OBBBA's new above-the-line write-off for personal auto loans

Car loan interest deduction: what do IRS final regs say?

Can you deduct car loan interest in 2025? Yes, up to $10,000 per return per year, for tax years 2025 through 2028. The car loan interest deduction under OBBBA §70203 covers loans incurred after December 31, 2024 that are secured by a first lien on a U.S.-assembled passenger vehicle you bought for personal use. Final…

OBBBA method change: IRS Rev. Proc. 2026-32 covers § 174 R&E and § 460(e) residential construction
|

OBBBA method change under IRS Rev. Proc. 2026-32?

Does the IRS finally have an automatic-consent path for OBBBA R&E and residential construction changes? Yes. IRS Rev. Proc. 2026-32 opens the automatic OBBBA method change for § 174, § 174A, and § 460(e), waives the usual eligibility bars through 2027, and gives one transition window that closes November 15, 2026. On September 4, 2026,…

QSBS: founder's C-corporation stock reshaped in a tax-free recap without breaking Section 1202
|

How to keep QSBS treatment through a recap (2026)

How do founders keep QSBS treatment through a recapitalization? A Section 368(a)(1)(E) tax-free recap can preserve QSBS under Section 1202(h)(4)(A), but only if the reorganization requirements are met, the aggregate gross assets threshold is respected, and Section 305 does not turn the recap into a taxable deemed distribution. Many of our founder clients organize as…

Federal tax changes for 2026 connecting Washington rulemaking to a small business counter with a card reader and calendar
|

Which 2026 Federal Tax Changes Affect Small Businesses?

Which 2026 federal tax changes affect my small business? The ones with a date attached: an August guidance package implementing the 2025 reconciliation law, backup withholding on payment-app settlements, the employer paid leave credit, and a September 30 federal funding deadline that decides how fast the IRS answers you this fall. Most tax headlines never…

Illustration of OBBBA nonprofit tax rules — Capitol, donation box, university facade with IRC section tokens
|

OBBBA nonprofit tax: What changed for your 501(c)(3)?

What did the OBBBA actually change for my nonprofit? Quite a lot. The OBBBA nonprofit tax rules created a new charitable deduction for non-itemizers, added floors that shrink deductions for high-income and corporate donors, expanded the §4960 excise on high pay, and set a tiered endowment tax for large private colleges. The One Big Beautiful…

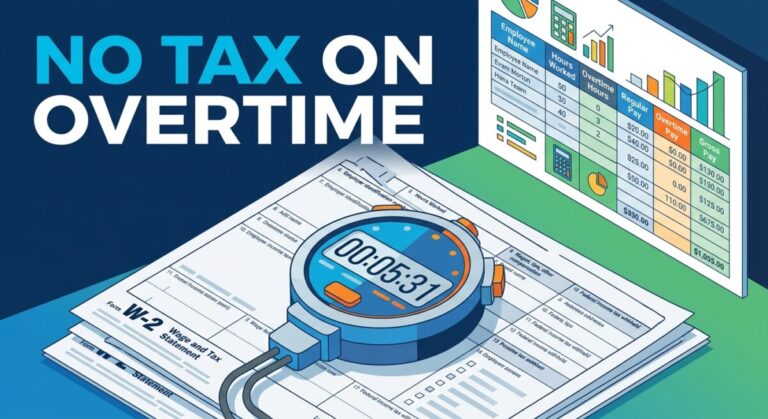
Illustration of the no tax on overtime deduction — a stopwatch on top of a Form W-2 with a payroll spreadsheet
|

No Tax on Overtime Deduction: How Much Can You Claim?

How much of my overtime pay is actually tax-free? Less than most workers think. The new no tax on overtime deduction is capped at $12,500 (single) or $25,000 (joint), phases out above $150,000 MAGI, and applies only to the FLSA overtime premium — not the entire overtime paycheck. On August 6, 2026 the IRS released…

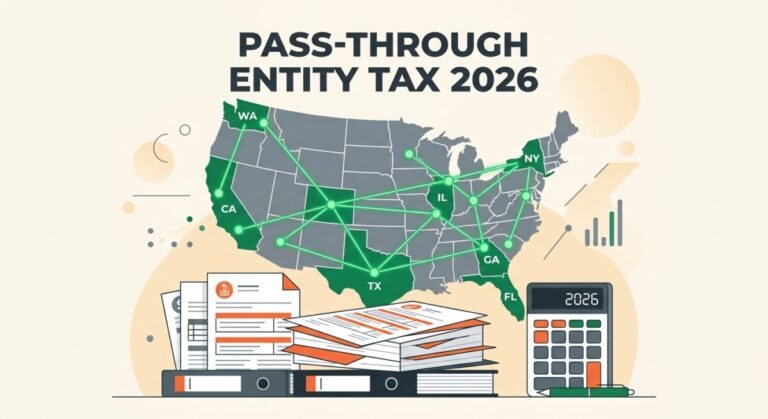
Illustration of pass-through entity tax planning in 2026 — a US map, state connections, and tax filings representing PTET SALT cap workaround analysis
|

Pass-Through Entity Tax 2026: SALT Cap Workaround Guide

Is the pass through entity tax election still worth it after the higher SALT cap? For many owners of profitable pass-throughs in high-tax states, the answer is still yes — but the analysis is now owner-level, state-specific, and no longer automatic. The pass through entity tax (PTET) survived the 2025 SALT cap increase; the decision…

Illustration of charitable donation records — receipts, heart icon, and a laptop with a tax form outline on a wooden desk
|

Charitable Donation Records 2026: IRS Rules to Know

What records do I actually need to deduct my charitable donations? The IRS requires charitable donation records for every gift you claim — a bank record or written communication for cash, a written acknowledgment for anything $250 or more, and Form 8283 for larger noncash gifts. And beginning in 2026, non-itemizers can also deduct up…

Illustration of a Trump Accounts guide — a growing sapling in a piggy bank with a family silhouette
|

Trump Accounts Guide 2026: $1,000 Deposit and Section 530A Rules

What is a Trump Account and how do I open one for my child? A Trump Account is a new federally authorized investment account for children, created by the One Big Beautiful Bill Act as IRC Section 530A. The Trump Accounts guide below walks families through the $1,000 federal seed deposit, $5,000 annual contribution cap,…

Illustration of the new Federal Scholarship Tax Credit — book, graduation cap, coins and scholarship certificate over a US flag ribbon
|

Federal Scholarship Tax Credit 2027: IRC §25F Guide

Who can claim the new Federal Scholarship Tax Credit? Starting January 1, 2027, individual taxpayers can claim the Federal Scholarship Tax Credit — a federal credit of up to $1,700 for cash donations to Scholarship Granting Organizations (SGOs) in a participating state. Twenty-eight states have already opted in. Beginning next year, a new line item…

Illustration of the 2026 tip deduction — a server holding a tip tray with cash and receipts
|

Tip Deduction 2026: Who Qualifies for the $25K Break?

Who qualifies for the new $25,000 federal tip deduction? The tip deduction 2026 is an above-the-line deduction for workers in customarily tipped jobs — waiters, bartenders, stylists, rideshare drivers and roughly 70 other IRS-listed occupations — worth up to $25,000 of qualified tips for tax years 2025 through 2028, subject to income phaseouts. For decades,…

Illustration of Qualified Opportunity Zones under IRS Notice 2026-40 — a city skyline on a map pin with a 2026 calendar marking the deferred-gain inclusion deadline
|

QOZ Update: IRS Notice 2026-40 and the Dec 31, 2026 Deadline

Are the Opportunity Zone rules changing? Yes. In IRS Notice 2026-40, the Treasury Department and the IRS announced that they intend to issue proposed regulations on Qualified Opportunity Zones under Internal Revenue Code §§ 1400Z-1 and 1400Z-2, as amended by the One, Big, Beautiful Bill Act (OBBBA). The notice provides transitional guidance for investments made…

Illustration of an early June 2026 federal tax roundup — proposed Section 892 sovereign investor relief, a $76 estate tax closing letter fee, excepted fertility benefits, and budget reconciliation
|

Federal Tax Roundup Early June 2026: §892, Estate Fee, Regs

What federal tax developments landed in early June 2026? Three Treasury/IRS regulatory proposals and a busy week on Capitol Hill. On the regulatory side: (1) proposed regulations under §892 (CC-00349656-26, IR-2026-69) giving sovereign investors transition relief and new applicability dates tied to the December 2025 proposed rules; (2) proposed regulations (REG-103193-26) raising the estate tax…

Illustration of the expanded IRC section 4960 21% excise tax on nonprofit executive compensation over $1 million under OBBBA and IRS Notice 2026-36
|

Nonprofit §4960 Excise Tax Expands Under OBBBA (Notice 2026-36)

How did OBBBA expand the §4960 excise tax on nonprofit executive compensation? Internal Revenue Code §4960 imposes a 21% excise tax on a tax-exempt organization’s “excess remuneration” — compensation over $1 million paid to a covered employee — plus certain excess parachute (separation) payments. Under the One, Big, Beautiful Bill Act, beginning with tax years…

Illustration of late May 2026 federal tax roundup — JCT OBBBA report, Treasury IRS guidance T.D. 10048 and Notice 2026-33, House tax bills, and Tax Court section 6038(b) rulings
|

Federal Tax Roundup Late May 2026: OBBBA, IRS Guidance, Courts

What are the most important federal tax developments from late May 2026? Four stand out. (1) The Joint Committee on Taxation released a 341-page provision-by-provision report on the One, Big, Beautiful Bill Act (OBBBA, P.L. 119-21) and flagged 10 provisions that may need technical correction. (2) Treasury and the IRS issued new guidance — final…

Illustration of OBBBA federal student loan limits and the Department of Education professional degree rule — $200K professional vs $100K other graduate caps, accounting excluded
|

OBBBA Student Loan Limits: New Caps & Professional Degree Rule

How did OBBBA change federal student loans for graduate and professional students? The One, Big, Beautiful Bill Act (OBBBA, Pub. L. No. 119-21) placed new caps on federal student loans and directed the U.S. Department of Education (DOE) to define which “professional degree” programs qualify for higher borrowing limits. Under the DOE’s final rule, only…

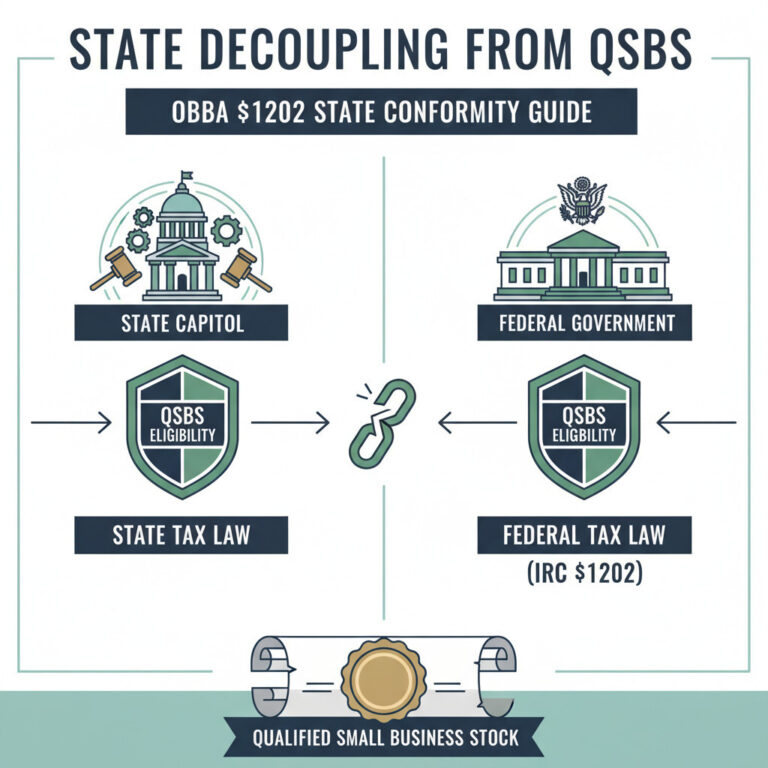
Illustration of state decoupling from federal QSBS section 1202 exclusion under OBBBA — Maine and Oregon decoupled, California taxes QSBS gains, state conformity risk for founders
|

State Decoupling from QSBS: OBBBA §1202 State Conformity Guide

Do states follow the federal QSBS exclusion under OBBBA — and why does state conformity matter? Not automatically. The One Big Beautiful Bill Act (OBBBA, Pub. L. No. 119-21) expanded the federal Qualified Small Business Stock (QSBS) exclusion under IRC §1202 — but states set their own conformity. Maine and Oregon have enacted legislation DECOUPLING…

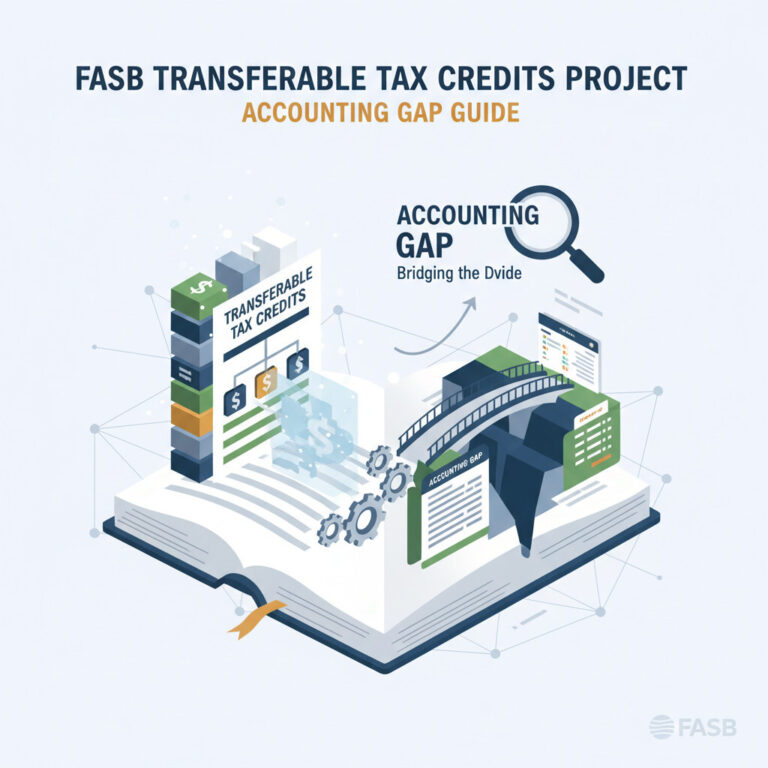
Illustration of FASB transferable tax credits accounting project — IRA, CHIPS, and OBBBA credit accounting gap, ASC 740 vs ASC 832 analogies, recognition triggers
|

FASB Transferable Tax Credits Project: Accounting Gap Guide

How should companies account for transferable tax credits under U.S. GAAP? The Financial Accounting Standards Board (FASB) voted in May 2026 to advance a project on the accounting treatment of nonrefundable transferable tax credits — including the Inflation Reduction Act (IRA) clean energy credits under IRC §6418, CHIPS and Science Act semiconductor credits, and One…

Illustration of IRS No Tax on Tips final regulations under the One Big Beautiful Bill — Treasury Tipped Occupation Code list and qualified tips definition
|

No Tax on Tips Final Regulations: 70+ Occupations, Qualified Tips Guide

Who qualifies for the No Tax on Tips deduction under the final regulations? The Treasury and IRS issued final regulations on April 10, 2026 (IR-2026-49) implementing the “No Tax on Tips” deduction under the One, Big, Beautiful Bill Act (OBBBA). Workers in 70+ occupations on the Treasury Tipped Occupation Code (TTOC) list can deduct qualified…

Irs 2026 filing season recap fy2027 budget featured
|

IRS 2026 Filing Season Recap: Bisignano Testimony and Budget Cuts

How did the IRS 2026 filing season perform and what’s next for the agency? IRS CEO Frank Bisignano reported 134 million returns filed, a $3,400 average refund up 11%, and $2 billion collected from the agency’s five largest enforcement cases — even as House appropriators propose a 9% FY2027 budget cut. The IRS 2026 filing…

Obbba tax scams 2026 featured
|

OBBBA Tax Scams: How to Protect Yourself in 2026

Are scammers exploiting the One Big Beautiful Bill? Yes — OBBBA tax scams are already active in 2026, with fraudsters targeting seniors, workers, and small business owners. This guide covers every major scam type so you can protect yourself and your finances. Tax season is stressful enough on its own. But whenever Congress passes major…

Overtime tax deduction obbba
|

No Tax on Overtime: OBBBA Overtime and Tips Tax Deduction Guide 2025-2028

Can I deduct overtime pay from my federal taxes under the new law? Yes — the One, Big, Beautiful Bill Act (OBBBA) created an overtime tax deduction worth up to $12,500 for individuals ($25,000 joint filers) for qualifying FLSA overtime earned from 2025 through 2028. A separate tips deduction of up to $25,000 is also…