ASU 2026-03: investment company fair value guide
For years, two investment companies holding identical restricted shares could report very different fair values — one that treated the lock-up as the fund’s problem and ignored it, and one that treated the restriction as part of the security and discounted. The Financial Accounting Standards Board has now closed that gap for one set of filers. Investment company fair value measurement is the subject of a new Accounting Standards Update that requires a discount when a contractual sale restriction prevents a sale on the measurement date. This post walks through what changed, who is in scope, how to size the discount, and what the new disclosures look like in a Form N-CSR or audited financial statement.
How did the FASB measure a contractual sale restriction before? 📘
Under existing Topic 820 guidance, a contractual sale restriction was generally viewed as a characteristic of the reporting entity rather than a characteristic of the security, so the fair value measurement did not include a separate discount for the restriction.
The current rule in ASC Topic 820, Fair Value Measurement treats a restriction that applies to the holder, rather than to the instrument itself, as entity-specific. The practical result is familiar to any fund administrator who has priced a legend-stock position: the measurement defaulted to the market price of an otherwise identical unrestricted equity security, and the lock-up was disclosed in the narrative but not reflected in the number on the schedule of investments.
That approach has been debated for a long time, especially after the 2022 clarification that the same principle applies even where the restriction has a stated term. Preparers and auditors generally agreed that the rule produced a defensible answer for most corporate holders, but it sat awkwardly with the way investment companies are supposed to measure net asset value — at the price at which an orderly transaction could actually take place today. For a fund that is contractually prohibited from selling, that price and the undiscounted market quote are not the same number.
What does ASU 2026-03 actually require for investment company fair value? ⚖️
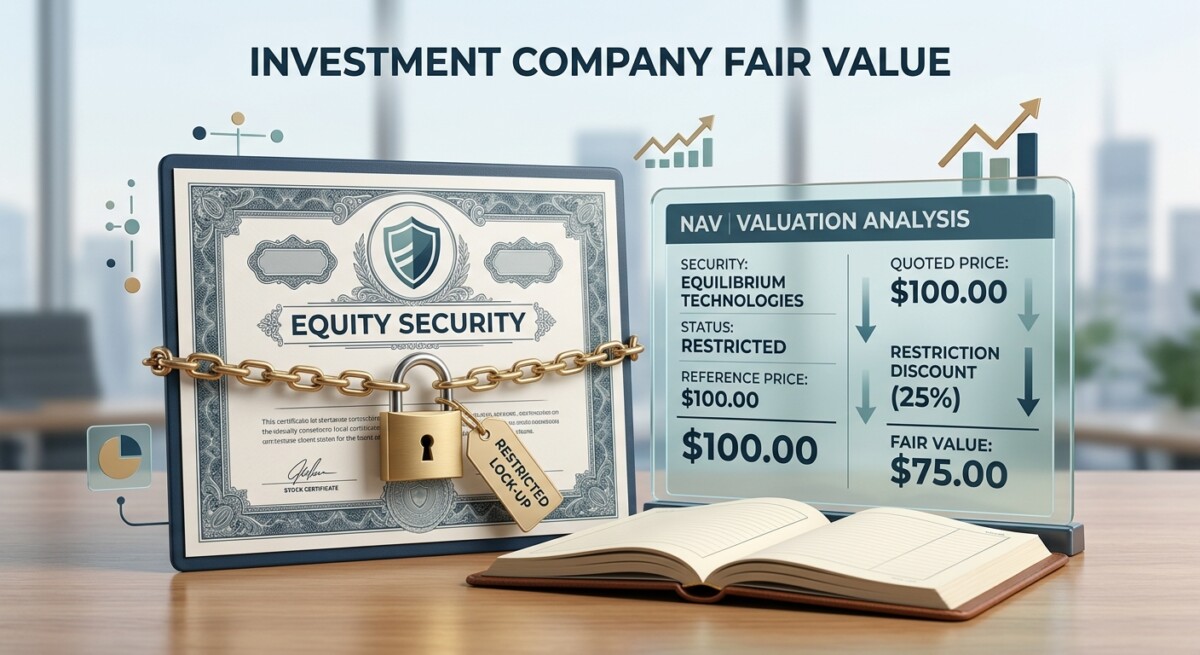
For an investment company within the scope of ASC Topic 946, when a contractual sale restriction prevents the fund from selling an equity security on the measurement date, the fund must incorporate the effect of the restriction in fair value by applying a discount, regardless of whether the restriction is considered a characteristic of the entity or the security.
The amendments reach into ASC Topic 820, Fair Value Measurement and specifically carve out the Topic 946 population from the earlier rule. For investment companies, the entity-vs-instrument distinction no longer governs. The question becomes narrower: on the measurement date, can the fund sell the security, and if not, what discount would a market participant demand to accept the restriction? That discount is now part of the fair value measurement, not a separate footnote.
| Area | Before the ASU | After the ASU (investment companies) |
|---|---|---|
| Scope | Topic 820 applied uniformly; no separate investment-company carve-out. | Investment companies in Topic 946 follow a dedicated rule for equity securities with contractual sale restrictions. |
| Measurement | Fair value equaled the market price of an identical unrestricted equity security; the restriction, if viewed as entity-specific, was not separately reflected. | The fund must apply a discount for the restriction when it prevents a sale on the measurement date; the discount reflects what a market participant would demand. |
| Instrument types | Covered equity, debt, and other instruments subject to the general Topic 820 principles. | Scope limited to equity securities. Debt, derivatives, and crypto assets in ASC 350-60 are excluded. |
| Interaction with other transactions | No explicit carve-out when the restriction is already reflected in another transaction’s economics. | No separate discount is required when the restriction is already reflected in the economics of another transaction (for example, a borrowing in which the securities are pledged). |
The carve-out matters: do not double-count the restriction
If an investment company has already priced the contractual sale restriction into a separate transaction — most commonly a borrowing in which the restricted shares are pledged as collateral — the ASU does not require a second discount at the security level. Applying both would understate net asset value and could distort incentive and management-fee calculations. The documentation should make the one-time inclusion explicit, especially where the collateral agreement and the valuation policy are maintained by different teams.
Which funds are inside the scope of the new investment company fair value rule? 🔎
The amendments apply to entities that meet the definition of an investment company in ASC Topic 946 — Financial Services, Investment Companies. The restriction is also tightly scoped: equity securities only, and only where a contractual restriction prevents a sale on the measurement date.
Topic 946 investment companies include most registered investment companies, business development companies, and many private funds whose activities and governance meet the Topic 946 criteria at ASC Topic 946, Financial Services — Investment Companies. A corporate holding company, an insurance general-account portfolio, or a non-investment-company family office is outside the scope and continues to apply the pre-existing Topic 820 principle for restricted equities.
- Entity scope. The reporting entity must be an investment company under Topic 946. The Topic 946 scoping tests should be revisited whenever a sponsor launches a new vehicle, because strategy drift can push a fund in or out of the definition.
- Instrument scope. Only equity securities subject to a contractual sale restriction. Statutory or regulatory restrictions, trading halts, and market-based illiquidity are not contractual restrictions for this purpose, although they may still affect fair value under the general Topic 820 framework.
- Trigger. The restriction must actually prevent a sale on the measurement date. A restriction that has expired, a right of first refusal that can be worked around, or a contractual provision that permits a sale with notice does not, by itself, trigger a discount.
- Excluded instruments. Debt securities, derivative contracts, and crypto assets measured under ASC Subtopic 350-60, Crypto Assets are outside the scope. A convertible note or a staked token with a lock-up continues under its existing measurement framework.
How should an investment company size the sale-restriction discount? 📐
The discount should reflect the amount market participants would demand because of the restriction. In practice, that generally pulls from the volatility of the underlying security, the remaining duration of the restriction, and observable restricted-stock transaction data; option-based models and empirical studies are both commonly used.
The ASU does not prescribe a specific technique, which is consistent with the broader Topic 820 approach of allowing valuation methodologies to be chosen based on the facts and the available inputs. In our practice we see three recurring patterns:
- Protective-put style option models. Treat the restriction as the equivalent of forgoing the right to sell for a defined period, and price that forgone optionality using the Black-Scholes framework or a Finnerty-type model. The main inputs are volatility, restriction duration, and the risk-free rate.
- Empirical restricted-stock study data. Draw on observed discounts in transactions where restricted and unrestricted shares traded contemporaneously. The data is sector-sensitive and dated, so most funds blend it with a market-based model rather than relying on it alone.
- Direct observable inputs. Where a side letter, private-market quote, or recent transfer at a documented discount exists, that transaction can anchor the measurement, with other techniques used as a cross-check.
From our practice: build the discount into Level 2 or Level 3 governance now
Early adopters we have advised were surprised at how much of the implementation burden fell on governance rather than on quantitative modeling. The discount is a fair-value input, which means it belongs in the fund’s valuation committee documentation, in the auditor’s review of pricing inputs, and often in the Form N-CSR’s discussion of significant accounting estimates. Standing up the review memo, the model-approval history, and the back-testing against subsequent transactions is the piece most funds underestimate. Running the model is the easy half of the project.
What disclosures does ASU 2026-03 add for investment companies? 📝
Investment companies must disclose the amount of any discounts attributable to contractual sale restrictions that are included in the fair value measurement of equity securities, in both interim and annual reporting periods. Existing Topic 820 disclosures about the fair value, nature, remaining duration, and lapsing conditions of the restriction continue to apply.
The practical effect is that readers of a fund’s financial statements will see, for the first time, a line in the fair value disclosures that quantifies the restriction itself. The existing qualitative description (what the restriction is, when it lapses, and what circumstances could release it) is unchanged. The new piece is the number — expressed either as an absolute dollar amount or as the discount applied to the otherwise-identical unrestricted price.
- Disclose the amount of any discounts for contractual sale restrictions included in fair value, at interim and annual reporting dates.
- Continue to disclose the fair value of restricted equity securities, the nature and remaining duration of the restrictions, and the conditions under which the restrictions could lapse.
- Disclose the transition adjustment in the period of adoption, including the fact that the amendments were applied prospectively.
- Review the fund’s N-CSR, N-2, or audited GAAP financial statements for cross-references to valuation policies that may need to be updated for the new line item.
How should investment companies plan the transition before 2027? 🗓️
Investment companies should assess the operational, financial-reporting, and governance impact of the ASU well before the mandatory effective date and decide whether early adoption fits the fund’s reporting calendar. The amendments are applied prospectively, with the cumulative adjustment recognized in current-period earnings and disclosed in the period of adoption.
A 2027 mandatory effective date gives most funds two full annual cycles to prepare, but the effect of adoption on net asset value, incentive calculations, and shareholder transactions is not something to leave to the final quarter. Early adoption is permitted on or after September 9, 2026, which can be useful for a fund that wants to align the change with a repricing event or a strategy pivot.
- Scope the portfolio. Identify every equity security that carries a contractual sale restriction on the measurement date. Working with the custodian or the transfer agent to flag legend stock and lock-ups in the position file is often the first step.
- Draft the valuation methodology. Pick one or more techniques (model, empirical study, observable transactions) and document why each fits the restriction type. Present it to the valuation committee before any live measurement.
- Decide on timing. Model the impact on net asset value, management fees, incentive allocations, and existing investor transactions under early adoption versus the December 15, 2027 effective date. Document the choice and the rationale.
- Update controls and disclosures. Revise valuation policies, pricing-source SOPs, and the standard disclosure templates for interim and annual filings. Communicate the change to the auditor and, where applicable, to the fund’s board.
- Run the transition entry. Compute the one-time adjustment, book it to current-period earnings, and include the required transition disclosure in the period of adoption.
Summary: investment company fair value under ASU 2026-03
- Investment companies in ASC Topic 946 must apply a discount when a contractual sale restriction prevents a sale of an equity security on the measurement date.
- The amendments do not apply to debt securities, derivatives, or crypto assets within ASC Subtopic 350-60, and do not require a double discount when the restriction is already priced into another transaction such as a secured borrowing.
- Required disclosure: the amount of any contractual sale-restriction discount included in fair value, at interim and annual reporting dates, plus the existing qualitative disclosures.
- Effective for annual periods beginning after December 15, 2027, with interim periods inside; early adoption permitted on or after September 9, 2026; prospective application with a current-period adjustment.
- Operational lift sits mostly in valuation governance, model documentation, and disclosure controls — not in the measurement model itself.
Frequently asked questions about investment company fair value ❓
Q. What is a contractual sale restriction?
A contractual sale restriction is a legally binding agreement that prevents the holder of an equity security from selling it on the measurement date — for example, an initial-public-offering lock-up, a shareholder agreement, or a stand-alone transfer restriction. Under Topic 820, the holder has to consider whether that restriction is a characteristic of the security itself (which is reflected in fair value) or a characteristic of the reporting entity (which, under current guidance, is not).
Q. Does ASU 2026-03 apply to companies that are not investment companies?
No. The amendments are scoped only to investment companies within ASC Topic 946. A corporate holder outside the investment-company scope continues to apply the existing guidance under ASC 820-10-35-6B, which does not permit a separate discount when the restriction is viewed as entity-specific. If you are unsure whether your fund structure meets the Topic 946 criteria, the scoping tests at ASC 946-10-15 should be reviewed before concluding.
Q. When does ASU 2026-03 take effect, and can an investment company early adopt?
The amendments are effective for annual reporting periods beginning after December 15, 2027, and interim periods within those annual periods. Early adoption is permitted on any date on or after September 9, 2026, which gives funds with calendar year-ends the option to apply the discount for the 2026 or 2027 financial statements. Any adjustment from adoption is recognized in current-period earnings and must be disclosed.
Q. Does the discount requirement apply to debt securities or crypto assets?
No. The scope is limited to equity securities. Debt securities, derivatives, and crypto assets within the scope of ASC Subtopic 350-60 are excluded. In practice, that means the ASU does not change how a fund measures a restricted convertible note, a privately placed debt instrument, or a staked token — those continue under their existing measurement frameworks.
Q. How should an investment company measure the discount?
The discount should reflect the amount a market participant would demand because of the restriction. In our practice, that calculation typically draws on three inputs — the volatility of the underlying security, the remaining duration of the restriction, and the depth of comparable restricted-stock transactions. Protective-put and option-based models are common; whatever technique is chosen, the governance and support should sit alongside the fund’s other Level 2 and Level 3 valuation documentation.
Q. Does the discount still apply when a restricted security is pledged in a borrowing?
No. The amendments carve out situations where the sale restriction is already reflected in the economics of another transaction, such as a borrowing in which the securities are pledged as collateral. If the fund is already pricing the restriction into the related transaction, applying a second discount at the security level would double-count the same economic effect.
This article is general information, not accounting or audit advice for a specific fund. Scoping and valuation decisions turn on the fund’s governing documents and investment program. If your fund is working through adoption of ASU 2026-03, contact SW Accounting & Consulting Corp for a confidential review. Primary sources used: FASB, FASB Accounting Standards Updates, FASB Accounting Standards Codification.