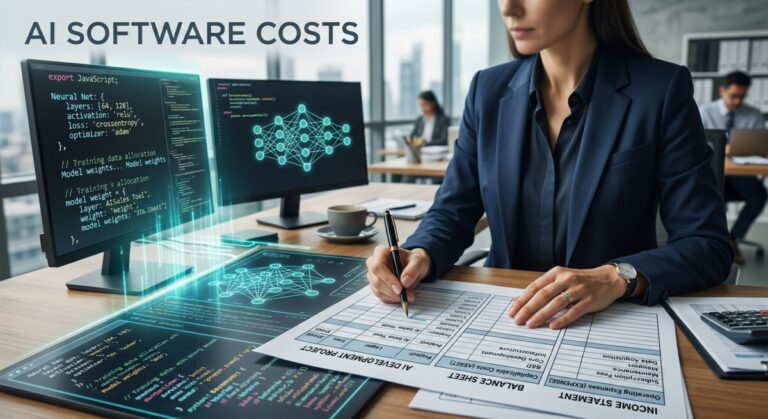
AI software costs: capitalizing versus expensing under US GAAP (ASC 350-40)
|

Can you capitalize AI software costs under US GAAP?

Can you capitalize AI software costs under US GAAP? Sometimes. US GAAP has no AI-specific rule — the existing internal-use software guidance in ASC 350-40 still controls. If AI software costs are project-specific, measurable, and incurred after the application development stage begins, they may be capitalized. General-purpose AI subscriptions are expensed. Every quarter our Los…
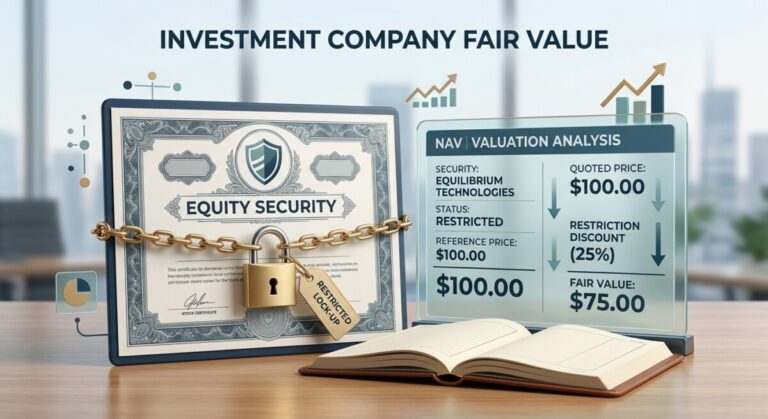
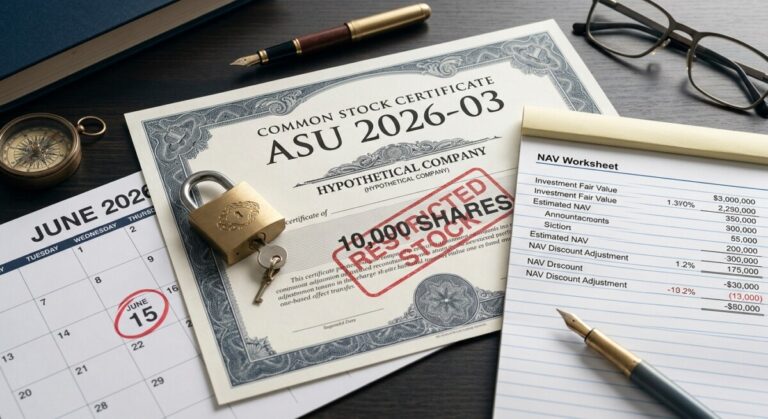
Investment company fair value: a locked equity security discounted on a fund's NAV ledger
|

ASU 2026-03: investment company fair value guide

How does ASU 2026-03 change investment company fair value? It requires an investment company to apply a discount when a contractual sale restriction prevents it from selling an equity security on the measurement date. The amendment is scoped to investment companies and to equity securities only, is effective for annual periods beginning after December 15,…

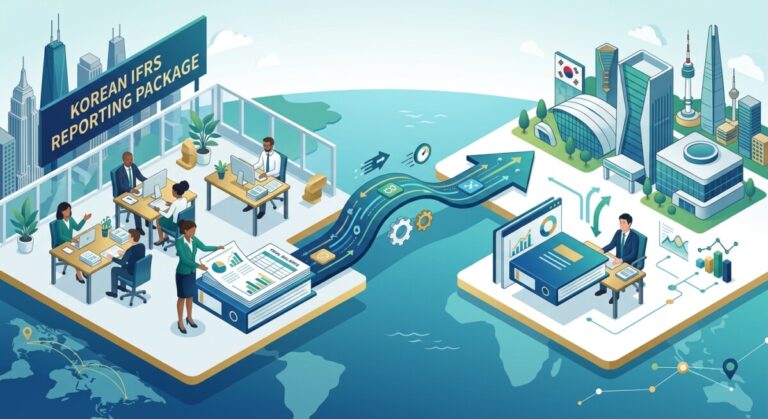
US subsidiary finance staff building a monthly Korean IFRS reporting package for its parent company.
|

How does a US subsidiary prepare a Korean IFRS reporting package for its parent?

What is a Korean IFRS reporting package, and why does your parent need one every month? A Korean IFRS reporting package — often written K-IFRS reporting package — is the standardized monthly submission a US subsidiary sends its Korean parent so the parent can consolidate the subsidiary’s results under Korean IFRS (K-IFRS). It contains a…

IFRS 15 vs ASC 606 — where revenue recognition still diverges between IFRS and US GAAP
|

IFRS 15 vs ASC 606: Where does revenue still diverge?

Are IFRS 15 and ASC 606 still converged? Substantially, yes — but the details still shift the timing and amount of revenue. This IFRS 15 vs ASC 606 guide walks through ten differences that change what dual reporters book and disclose, grounded in the standards themselves rather than firm commentary. The joint issuance of IFRS…

FASB ASU 2026-03: contractual sale restrictions and fund NAV
|

Does ASU 2026-03 change fair value sale restrictions?

Does ASU 2026-03 change fair value sale restrictions for investment funds? Yes — but only for investment companies within the scope of Topic 946. From adoption, those funds must incorporate a discount for contractual sale restrictions when measuring the fair value of an equity security, and disclose the size of that discount. Effective for annual…

FASB effective dates 2026: the ASUs first effective for calendar-year entities
|

FASB effective dates 2026: which ASUs kick in this year?

Which FASB standards take effect in 2026? The largest calendar-year first-effective ASUs are 2023-09 (income tax disclosures, private companies), 2024-04 (induced conversions of convertible debt, all entities), 2025-05 (AR credit losses practical expedient, PCC), and 2024-01 (profits interest awards, private companies). This post is a plain-English guide to the FASB effective dates 2026 that will…

Illustration of FASB ASU 2025-06 modernizing internal-use software capitalization under Subtopic 350-40 — replacing project stages with a probable-to-complete threshold for agile development
|

FASB ASU 2025-06: Internal-Use Software Cost Rules Modernized

How does FASB ASU 2025-06 change accounting for internal-use software? The FASB issued ASU 2025-06, Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40): Targeted Improvements, to modernize software cost guidance written in 1998 for today’s agile development. The biggest change: it ELIMINATES the old project-stage (waterfall) model for deciding when to start capitalizing costs. Instead, capitalization begins…

Illustration of FASB ASU 2026-02 and new ASC 818 — accounting for environmental credits like carbon offsets, RECs, and allowances and environmental credit obligations
|

FASB ASU 2026-02: Environmental Credits Accounting (ASC 818)

How do you account for carbon credits and emission allowances under U.S. GAAP now? On May 19, 2026, the FASB issued Accounting Standards Update (ASU) 2026-02, creating a brand-new Codification Topic — ASC 818, Environmental Credits and Environmental Credit Obligations. Until now, U.S. GAAP had no specific guidance for carbon offsets, renewable energy certificates (RECs),…

Illustration of the FASB Investor Advisory Committee May 2026 recap — disclosure themes on data center financing, private credit, stablecoins, hedge accounting, DISE, and debt restructurings
|

FASB Investor Advisory Committee May 2026: 5 Key Themes

What is the FASB hearing from investors right now? At its May 28, 2026 meeting, the FASB’s Investor Advisory Committee (IAC) flagged where today’s financial statements fall short for investors — and where new disclosure may be coming. Top themes: (1) data center financing and private credit are growing complex and opaque; (2) whether certain…

Illustration of FASB ASU 2026-01 — initial measurement of paid-in-kind PIK dividends on equity-classified preferred stock at the stated rate under Topic 505
|

FASB ASU 2026-01: PIK Dividends on Preferred Stock Explained

How does FASB ASU 2026-01 change the accounting for PIK dividends on preferred stock? In April 2026, the FASB issued Accounting Standards Update No. 2026-01, Equity (Topic 505): Initial Measurement of Paid-in-Kind Dividends on Equity-Classified Preferred Stock. It fills a gap in U.S. GAAP that had produced diversity in practice. The new rule: an issuer…

A professional and clean illustration showing a bridge connecting two different sets of building blocks, one labeled 'J-GAAP' and the other 'US GAAP'. A business person is carefully walking across the bridge, symbolizing the challenge of navigating the two accounting systems. The style should be modern, using a corporate color palette of green, orange, and blue.

The GAAP Gap: Why US Accounting Rules Are a Challenge for Japanese Companies

  Facing the GAAP Gap? Many Japanese companies with U.S. subsidiaries are struggling with complex American accounting rules. Discover the key challenges and how to navigate them to avoid costly penalties! Have you ever felt like you’re speaking a different language at work? That’s exactly what many Japanese companies are experiencing with their U.S. operations,…

US GAAP vs IFRS image

<US GAAP vs IFRS> Ch 1. Principles, Practices, and Distinctions

  US GAAP vs. IFRS: What’s the Real Difference? This guide breaks down the key similarities and differences between the two major accounting standards in simple terms, helping you understand how they impact global business and investment. Have you ever looked at a financial report from a company in Europe and felt like something was…