IFRS 18 2027: what changes for financial reporting?
The income statement that readers of IFRS financial statements have known for a generation is being rebuilt. Starting with annual periods beginning on or after January 1, 2027, IFRS 18 Presentation and Disclosure in Financial Statements replaces IAS 1 and restructures how profit or loss is presented. For most calendar-year groups, that means the 2028 annual report, containing 2027 results and a restated 2026 comparative, is the first set of financial statements under the new standard. IFRS 18 2027 is not a cosmetic change. It introduces defined categories, mandatory subtotals, and a disclosure framework for the non-GAAP measures management has long used in investor presentations. This post walks through what actually changes, where the implementation work sits, and what controllers and CFOs should be doing now.
What is IFRS 18 and when does it take effect? 📅
IFRS 18 is the IASB standard on presentation and disclosure in financial statements, replacing IAS 1. It is effective for annual reporting periods beginning on or after January 1, 2027, applied retrospectively, with earlier application permitted.
The IASB issued IFRS 18 in April 2024 after a multi-year project on primary financial statements. The IASB press release at the time described the objective as giving investors more comparable and transparent information about a company’s financial performance. Compared with the standard it replaces, IAS 1, three changes drive almost all of the implementation effort.
- Structured categories and mandatory subtotals in the statement of profit or loss.
- A required note on management-defined performance measures (MPMs), with a reconciliation to the most comparable IFRS subtotal.
- Enhanced aggregation and disaggregation principles that apply across all primary statements and the notes.
Secondary changes include limited amendments to the statement of cash flows — notably removing the accounting-policy options for the classification of interest and dividends — and consequential amendments to a number of other IFRS Accounting Standards. The statement of financial position itself sees only minor changes. The full scope is set out in the IFRS 18 Project Summary (April 2024).
How does IFRS 18 change the structure of the income statement? 📊
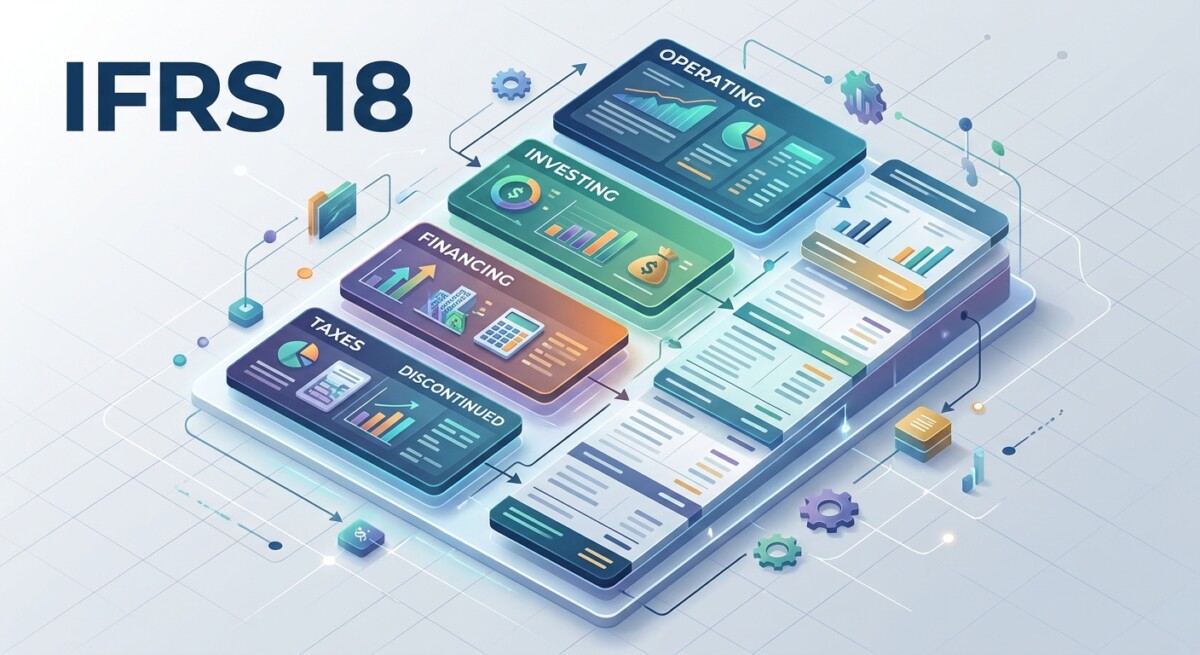
Every item of income and expense is classified in one of five categories — operating, investing, financing, income taxes, and discontinued operations — and two new mandatory subtotals must appear above net profit: operating profit or loss, and profit or loss before financing and income taxes.
The last two categories, income taxes and discontinued operations, are familiar. The first three are new and are the main point of IFRS 18. Classification is not optional: each line item must sit in one category, and the standard provides definitions and application guidance that drive where items go.
| Category | What goes here | Typical examples |
|---|---|---|
| Operating | The residual category — everything not classified in another category. For most entities, this is the day-to-day business. | Revenue, cost of sales, employee benefits, general and administrative expense |
| Investing | Income and expenses from assets that generate a return largely independent of the entity’s other resources, and from investments in associates and joint ventures. | Dividend income from equity investments, income from investment property, share of profit of equity-method investees |
| Financing | Income and expenses from liabilities arising from financing activities, and from transactions involving only cash or cash equivalents. | Interest expense on borrowings, interest income on cash deposits, foreign exchange on financing liabilities |
| Income taxes | Tax expense and the effect of taxes on items classified elsewhere, as currently reported. | Current and deferred income tax |
| Discontinued operations | Carried forward from IFRS 5. | Post-tax results of discontinued operations |
The two new subtotals follow directly from the categories. Operating profit or loss is the subtotal of everything in the operating category. Profit or loss before financing and income taxes is operating profit or loss plus the investing category. The familiar bottom line, profit or loss for the period, is unchanged in name but now reconciles to these required subtotals rather than being arrived at through a presentation chosen by management.
From our practice: specialized entities need a second look
Entities whose main business is investing in assets, providing financing to customers, or both, classify some items differently from the general rules. A bank’s interest income and expense, or an investment entity’s dividend income, is operating rather than investing or financing. Mislabelling these at the chart-of-accounts stage is the single most common early mistake we see when groups start mapping their income statements.
What is a management-defined performance measure, and what has to be disclosed? 📝
An MPM is a subtotal of income and expenses used in public communications outside the financial statements to convey management’s view of performance. IFRS 18 requires it to be disclosed in a single note, with a reconciliation to the most comparable IFRS subtotal and the tax and NCI effect of each reconciling item.
Non-IFRS measures — adjusted operating profit, adjusted EBITDA, underlying earnings, cash earnings — have long sat in investor presentations and earnings releases without being audited. IFRS 18 does not ban them. It brings them inside the financial statements. If management uses a subtotal to communicate its view of performance in filings outside the financial statements, the standard treats it as an MPM and requires:
- A statement describing the aspect of performance the MPM is intended to communicate, and why management believes it provides useful information.
- A reconciliation between the MPM and the most directly comparable subtotal defined by IFRS 18 or another IFRS Accounting Standard.
- The income tax effect and the effect on non-controlling interests for each reconciling item, with an explanation of how the tax effect was determined.
- A description of any change in how the MPM is calculated, including the reason for the change and restated comparatives.
Subtotals that are already required by other IFRSs — gross profit, operating profit or loss, profit before tax — are not MPMs. Measures communicated only within the financial statements are not MPMs. Everything else that management uses to tell the performance story in the annual report, in earnings releases, or in investor decks is in scope.
MPMs are now audit scope
Because the MPM note sits inside the financial statements, external auditors will audit the reconciliation, the tax effect, and the description. In practice, that means the quiet spreadsheets your investor-relations team maintains for adjusted earnings will be looked at the same way as any other number in the primary statements. Build the audit trail now, not during the first-year audit.
What do groups need to do before the IFRS 18 effective date? 🛠️
The work splits into four streams: map the chart of accounts into the five categories, design the restated 2026 comparatives, inventory and formalize MPMs, and update consolidation and disclosure tooling. None of this is a last-quarter exercise.
For a single entity, remapping the chart of accounts to the IFRS 18 categories is manageable. For a group with dozens or hundreds of reporting entities, each with its own general ledger structure, the exercise is substantially larger. The common blocker is that today’s charts of accounts rarely capture enough detail to classify items by the nature of the underlying asset or liability — which is what the new rules on aggregation require.
- Map every line to a category. Begin with the general ledger of your largest reporting entity and classify each account into operating, investing, financing, income taxes, or discontinued operations. Resolve the edge cases centrally — foreign exchange, lease interest, pension finance cost — before pushing the mapping to subsidiaries.
- Design the restated 2026 comparatives. Retrospective application means you need an IFRS 18 version of the 2026 income statement when you publish 2027 results. Decide now whether you will run the comparative in parallel through 2026 or recreate it from the general ledger at year-end.
- Inventory your MPMs. List every performance measure used in earnings releases, investor decks, and management commentary. For each, draft the description, the reconciliation to the comparable IFRS subtotal, and the tax-effect calculation methodology. Many groups will find they have more MPMs than they thought once the definition is applied strictly.
- Update consolidation and disclosure tools. Report templates, consolidation mappings, and XBRL taxonomies all change. The IFRS Foundation has indicated that the IFRS Accounting Taxonomy will be updated for IFRS 18 — plan the XBRL review as a separate workstream.
- Brief the audit committee and investor relations. The first-year disclosures will look different. A clear narrative to the audit committee about why operating profit under IFRS 18 differs from what used to be reported, and a parallel narrative to investors, prevents later surprises.
How do interest and dividends classifications change under IFRS 18? 💵
IFRS 18 removes the accounting-policy choices that IAS 7 allowed for the classification of interest paid, interest received, and dividends received in the statement of cash flows, and ties the cash-flow classifications to the new income-statement categories.
Under IAS 7, entities could choose how to classify these items between operating, investing, and financing cash flows. The flexibility helped comparability within a company’s own filings but hurt comparability across companies. IFRS 18 narrows the choice. For most entities, interest paid and dividends paid are classified in financing activities, interest received and dividends received in investing activities, and the classification in the cash flow statement follows the classification in profit or loss. Entities whose main business is investing or providing financing apply different rules that align with how their income statement is categorized.
The practical consequence is modest for most groups but matters for financial-services and real-estate entities, where interest and dividend flows are economically operating. Expect the free cash flow metric many groups use in their management reporting to shift, and plan the investor-communications side of that shift at the same time as the accounting change.
Summary: IFRS 18 in one card
- Effective for annual reporting periods beginning on or after January 1, 2027; retrospective application means 2026 comparatives are restated.
- Replaces IAS 1 and reshapes the statement of profit or loss into five categories — operating, investing, financing, income taxes, discontinued operations — with two new mandatory subtotals above net profit.
- Introduces a required note on management-defined performance measures, with reconciliation and tax effect, bringing adjusted EBITDA and similar measures inside audit scope for the first time.
- Removes IAS 7 accounting-policy choices for interest and dividend classifications in the cash flow statement.
- The implementation work is on the data side: chart-of-accounts mapping, restated comparatives, MPM governance, and consolidation-tool updates. None of this is a last-quarter exercise.
Frequently asked questions about IFRS 18 ❓
Q. When does IFRS 18 take effect, and does it apply retrospectively?
IFRS 18 is effective for annual reporting periods beginning on or after January 1, 2027, with earlier application permitted. Entities must apply it retrospectively, meaning the 2026 comparative figures presented alongside 2027 results have to be restated under the new structure. The 2028 annual report containing 2027 results is the first set of financial statements where IFRS 18 is mandatory for most issuers.
Q. Does IFRS 18 replace IAS 1?
Yes. IFRS 18 replaces IAS 1 Presentation of Financial Statements. Much of what IAS 1 covered carries forward with limited changes, but the statement of profit or loss is substantially restructured and new disclosure requirements are added, including a note on management-defined performance measures.
Q. Does IFRS 18 apply to U.S. GAAP filers?
No. IFRS 18 is an IASB standard, so it applies to entities reporting under IFRS Accounting Standards, which includes most listed companies outside the United States and many U.S. subsidiaries of foreign parents. U.S. domestic SEC registrants continue to follow U.S. GAAP, although foreign private issuers filing on Form 20-F using IFRS will apply IFRS 18.
Q. What are the five new categories of income and expense under IFRS 18?
Every item of income and expense in the statement of profit or loss must be classified in one of five categories: operating, investing, financing, income taxes, and discontinued operations. Operating is the default residual category. Investing captures returns from assets that generate a return largely independent of the entity’s other resources. Financing captures income and expenses from liabilities arising from financing activities and from transactions involving only cash or cash equivalents.
Q. What is a management-defined performance measure (MPM)?
An MPM is a subtotal of income and expenses, communicated in filings outside the financial statements, that an entity uses to convey management’s view of financial performance. Common examples include adjusted operating profit and adjusted EBITDA. IFRS 18 requires each MPM to be disclosed in a single note with a description, a reconciliation to the most comparable IFRS subtotal, and the income tax and non-controlling interest effect for each reconciling item.
Q. Will EBITDA still be shown on the face of the income statement?
Not as a required subtotal. IFRS 18 defines two new mandatory subtotals — operating profit or loss and profit or loss before financing and income taxes — but EBITDA is not one of them. Entities that disclose EBITDA will almost always do so as an MPM, which triggers the note disclosure, reconciliation, and audit scrutiny that comes with it.
Q. Does IFRS 18 change the balance sheet or the cash flow statement?
It makes targeted changes. The statement of financial position is largely unchanged. The statement of cash flows has limited changes, including the removal of accounting-policy choices for the classification of interest and dividends under IAS 7 — these will now have a single required classification linked to the operating, investing, or financing categories in profit or loss.
This article is general information, not accounting or legal advice for your situation. Implementation of IFRS 18 depends on the specific facts of each group. For a tailored transition assessment, contact SW Accounting & Consulting Corp.