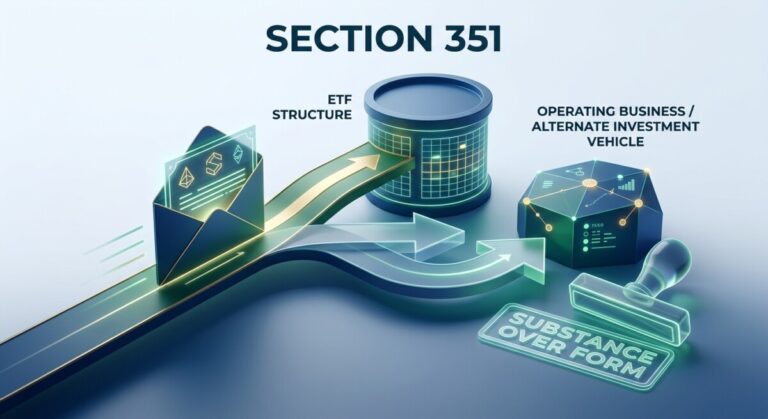
Section 351 ETF conversion: Rev. Rul. 2026-20
Does the Section 351 ETF conversion still work after Rev. Rul. 2026-20? Not the way it has been sold. The IRS now treats a planned transfer of securities to a new ETF followed by an authorized-participant redemption of those same securities as a single taxable exchange, not a tax-free diversification. The Section 351 ETF conversion…