Employee tax benefits: a US small business reviewing its 2026 benefits package
|

Employee tax benefits 2026: What can my business offer?

What employee tax benefits can my business offer in 2026? The federal tax code pays for a surprising share of a competitive benefits package. The right employee tax benefits can lower a small employer’s net cost of paid leave, education, child care, retirement savings, and even a new Trump Account, through credits and exclusions that…
Influencer tax: a creator's ring light and phone beside receipts and a mileage log
|

Are influencer tax rules different from other tax rules?

Are influencer tax rules any different from regular tax rules? No. The Tax Court’s first ruling involving a social-media creator, Sami v. Commissioner, applied the same ordinary-and-necessary business expense standard used for every other business. What actually decides an influencer tax audit is substantiation, business purpose, and whether the activity is a real trade or…

Year-end tax planning: a Q4 calendar and retirement statement on a high earner's desk
|

Year-end tax planning: what should high earners do in Q4?

Which year-end tax planning moves actually shift a high earner’s 2026 tax bill? The ones the Internal Revenue Code closes at midnight on December 31 — retirement contributions coded to a payroll cycle, wash-sale-safe loss harvests, exercised stock options, direct-to-charity IRA distributions, and completed annual-exclusion gifts. Year-end tax planning for high earners is less about…

FTB overcollection versus overpayment under California FTB Legal Ruling 2026-02
|

FTB overcollection vs. overpayment: SOL changes

Can FTB return money it collected years ago? Sometimes, yes. FTB Legal Ruling 2026-02 (issued August 21, 2026) draws a sharp line between an overpayment (subject to the four-year refund statute) and an FTB overcollection (excess taken by mechanical or clerical error during involuntary collection). Overcollections can be returned even after the SOL — but…

IRA fraud: a retirement account drained by a phone scam and the tax bill that follows
|

Is IRA fraud still taxable? What does the IRS waive in 2026?

Is IRA fraud still taxable if the money was stolen? Usually, yes. A withdrawal you were tricked into making is still a distribution to you, so the amount is taxable and a Form 1099-R follows. The IRS has waived the 60-day rollover deadline for IRA fraud victims in several private letter rulings, but the waiver…

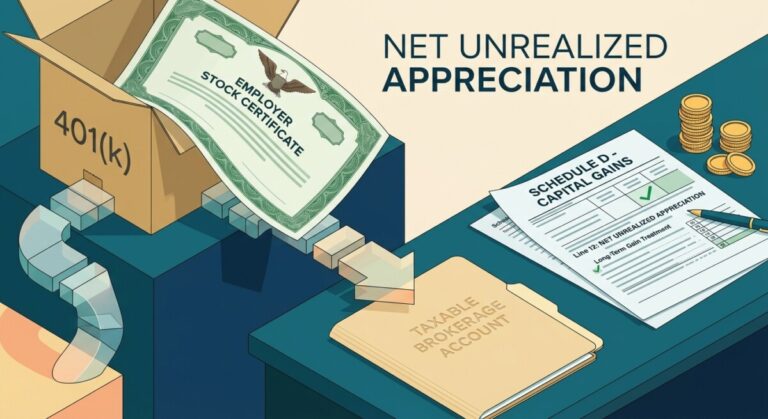
Net unrealized appreciation illustration: employer stock leaving a 401(k) for a taxable brokerage account
|

What is Net Unrealized Appreciation (NUA)? 401(k) Guide

What is Net Unrealized Appreciation (NUA), and could it lower my 401(k) tax bill? Net unrealized appreciation is a federal tax election under IRC §402(e)(4)(B) that lets you move employer stock out of a qualified retirement plan and pay ordinary income tax only on the stock’s original cost basis. The built-in gain is then taxed…

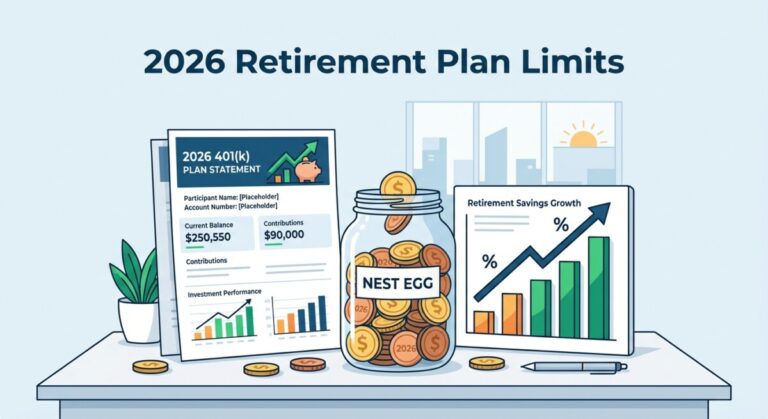
Illustration of 2026 retirement plan limits — a coin-filled nest egg jar, a rising chart, and a 401(k) statement
|

2026 Retirement Plan Limits: 401(k), Catch-Up & Roth

What are the 2026 retirement plan limits? The 401(k) elective deferral limit rises to $24,500, the age-50 catch-up to $8,000, and a new “super catch-up” lets employees aged 60–63 add $11,250. The 2026 retirement plan limits also bring a major SECURE 2.0 change: high earners must now make catch-up contributions as Roth. If you sponsor…

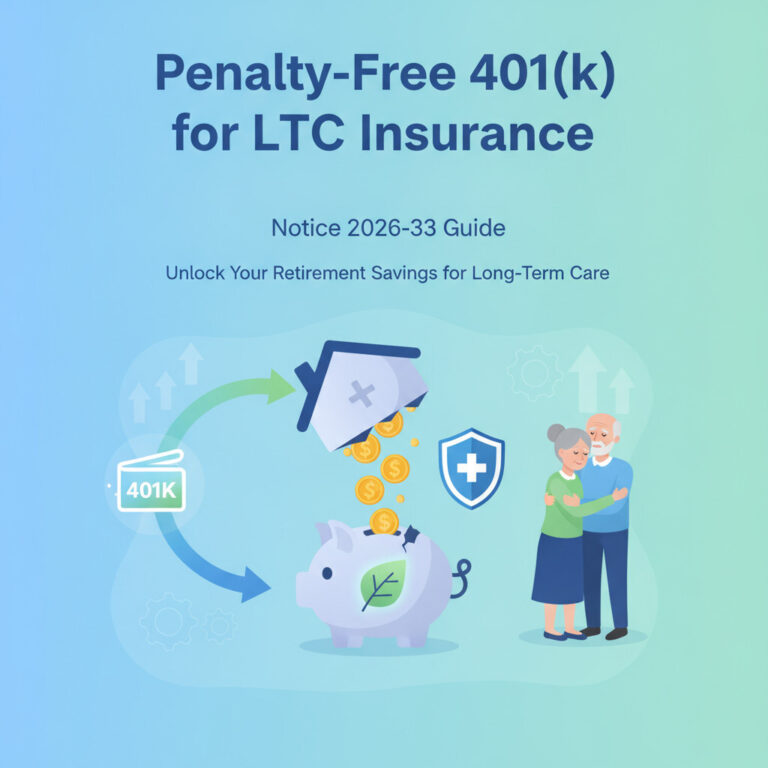
Illustration of qualified long-term care distributions under SECURE 2.0 section 334 and IRS Notice 2026-33 — penalty-free 401(k) money for LTC insurance premiums up to $2,600
|

Penalty-Free 401(k) for LTC Insurance: Notice 2026-33 Guide

Can you use 401(k) money to pay long-term care insurance premiums without the 10% penalty? Yes — within limits. Under SECURE 2.0 Act §334 (effective for distributions after December 29, 2025), a defined contribution plan may permit “qualified long-term care distributions” under new IRC §401(a)(39). The annual cap is the LEAST of: (1) the amount…

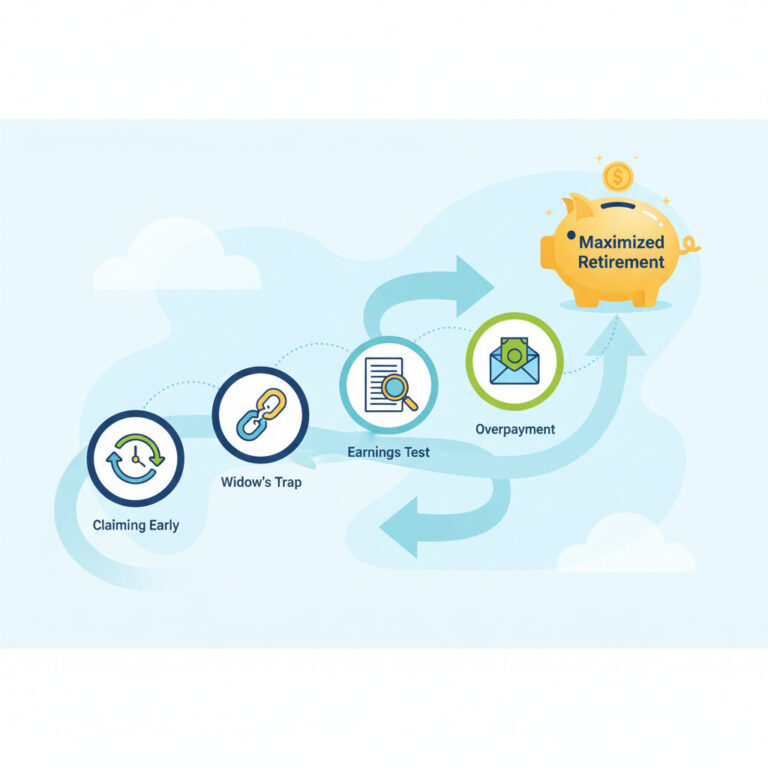
A clean, modern infographic showing four common pitfalls to avoid on the path to a secure retirement. Use icons for each point: 1) A clock with an arrow moving backward for 'Claiming Early'. 2) A broken chain link for 'Widow's Trap'. 3) A document with a magnifying glass for 'Earnings Test'. 4) An envelope with a bill sticking out for 'Overpayment'. The path should lead to a glowing piggy bank labeled 'Maximized Retirement'. Use a friendly and reassuring color palette.

4 Critical Social Security Mistakes That Can Cost You Tens of Thousands

  The Most Common Social Security Mistakes and How to Avoid Them. Are you at risk of losing over $182,000 in lifetime benefits? This guide breaks down the four biggest traps, from claiming early to the confusing earnings test, so you can maximize your retirement income. Deciding when and how to claim Social Security is…

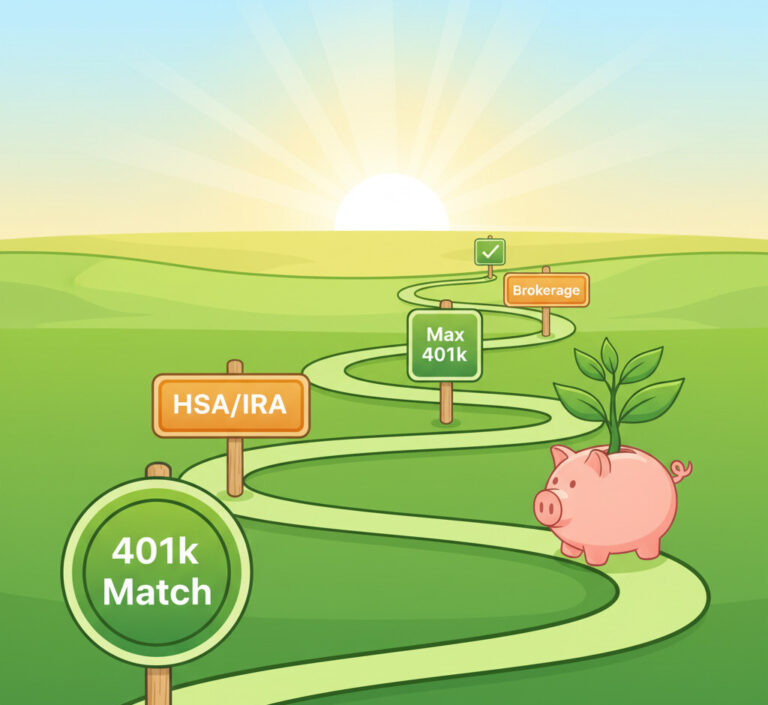
A vibrant and optimistic illustration of a path or roadmap leading towards a sunny horizon with a piggy bank and a growing green plant at the end. The path has clear, friendly signs labeled '401k Match,' 'HSA/IRA,' 'Max 401k,' and 'Brokerage.' The style should be modern, clean, and encouraging, using a green and orange color palette.

The Ultimate Retirement Savings Priority List for 2025 (feat. Backdoor Roth IRA)

  Want to Maximize Your Retirement Savings in 2025? This guide provides a clear, step-by-step priority list for your investments and explains the powerful Backdoor Roth IRA strategy for high earners. Stop guessing and start building wealth effectively! Feeling a bit overwhelmed by all the different retirement accounts? 401(k), IRA, Roth, HSA… it’s a lot…

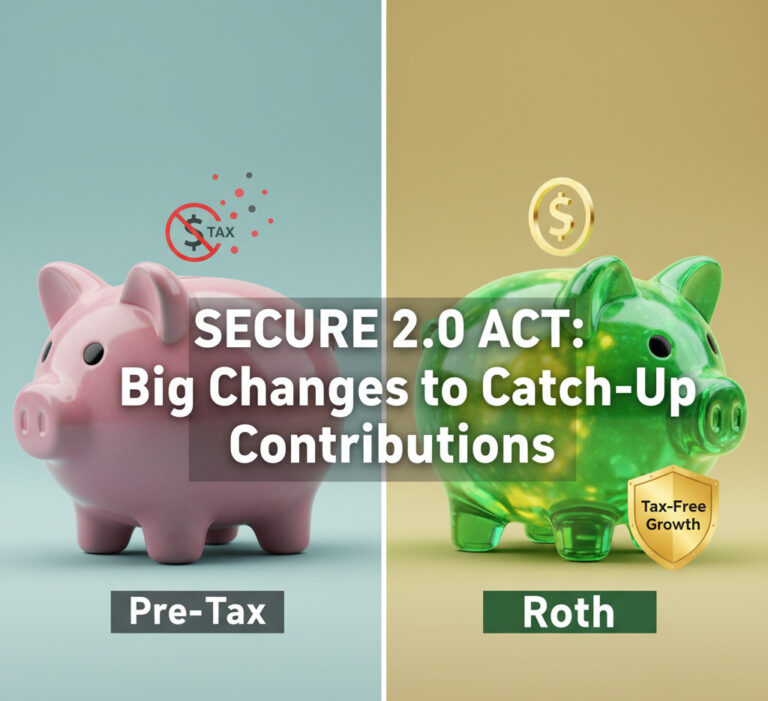
Roth catch-up contributions, SECURE 2.0 Act, retirement savings, 401k rules, high-income earners, catch-up contributions 2026, retirement planning, Section 603 SECURE Act, post-tax contributions, retirement tax rules

SECURE 2.0 Roth Catch-Up Contributions: Final Rule from IRS

  Must High-Earners Make Roth Catch-Up Contributions? A key change from the SECURE 2.0 Act is coming. If you earn over $145,000, find out how your retirement catch-up contributions will be affected and what you need to do to prepare. Are you diligently saving for retirement and looking forward to making those extra “catch-up” contributions…

A vibrant and optimistic flat design illustration showing a split path. On the left, a family is protected under a large umbrella labeled 'Life Insurance.' On the right, an elderly couple is relaxing on a beach with a steady stream of gold coins flowing towards them from a document labeled 'Annuity.' The style should be friendly, clear, and use a green and orange color palette.

Annuity and Life Insurance Plan A to Z: Your Ultimate Guide

  Annuity vs. Life Insurance: Which is the right financial tool for you? This guide breaks down these complex products into simple, understandable terms, helping you choose the best path for protecting your family and securing your retirement. Have you ever felt like you’re trying to solve a puzzle with half the pieces missing when…