International tax developments: Pillar Two, CRS, AI
What changed this week
| Development | Who it affects |
|---|---|
| EU Pillar Two compliance tightens as member states transpose DAC 9 | US-headquartered multinational enterprise groups with EU-member-state operations and consolidated revenue of EUR 750 million or more in at least two of the four preceding fiscal years — the Pillar Two scoping threshold. |
| CRS XML schema v3.0 takes effect January 1, 2027 | US business owners who hold or signed on foreign financial accounts in Common Reporting Standard participating jurisdictions, family offices with offshore structures, and single-member funds that use non-US custodians. |
| AI tools are already reshaping tax administration | US business owners whose group files tax returns in multiple jurisdictions, and owners whose returns touch areas that administrations are scoring aggressively with artificial intelligence — cross-border services, transfer pricing on royalties and management fees, and high-value value-added tax or goods and services tax refund claims. |
EU Pillar Two compliance tightens as member states transpose DAC 9
European Union member states are enacting legislation to transpose Council Directive (EU) 2025/872, commonly referred to as DAC 9. The directive installs the automatic exchange of global anti-base-erosion information returns across member states, clarifies filing responsibilities under the income inclusion rule and the undertaxed profits rule, aligns the filing deadline for the qualified domestic minimum top-up tax return with the global anti-base-erosion information return deadline, and formalizes a tiered penalty framework for Pillar Two non-compliance. Belgium is the most recent member state to adopt transposing legislation, joining a widening group of jurisdictions whose rules now interoperate through DAC 9 exchange.
Who it affects: US-headquartered multinational enterprise groups with EU-member-state operations and consolidated revenue of EUR 750 million or more in at least two of the four preceding fiscal years — the Pillar Two scoping threshold.
What to do
Lock down which group entity files the global anti-base-erosion information return in each EU jurisdiction where you have presence, and confirm whether a central filing or a jurisdiction-by-jurisdiction filing applies to your group. Push the aligned domestic top-up tax return deadlines into your close calendar, and share the schema, timeline, and penalty framework across your tax provision, compliance, controllership, and legal teams so no deadline sits with one person who is on vacation.
Primary source: EUR-Lex — Pillar Two Directive (EU) 2022/2523
CRS XML schema v3.0 takes effect January 1, 2027
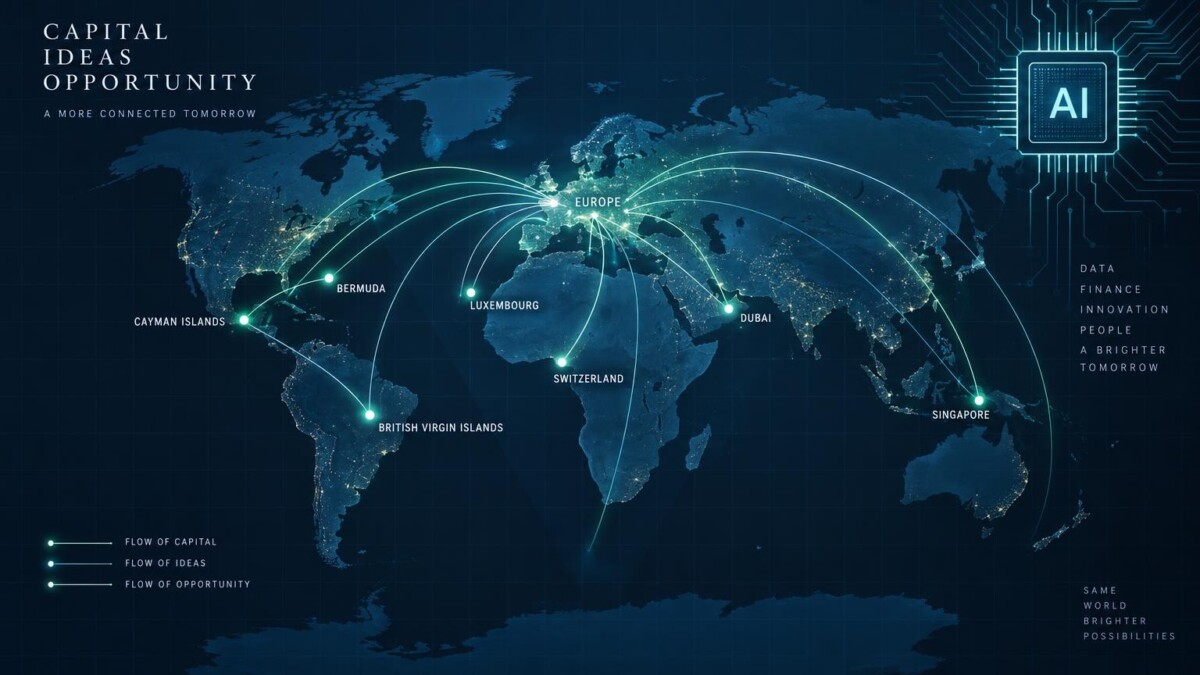
Tax authorities in offshore reporting jurisdictions, including the British Virgin Islands International Tax Authority, have issued industry notices advising of the mandatory adoption of the Organisation for Economic Co-operation and Development’s Common Reporting Standard XML schema version 3.0 beginning January 1, 2027. The updated schema introduces additional data points on controlling persons, account holder identification, and the distinction between pre-existing and new accounts under the amended Common Reporting Standard. The schema change aligns reporting across the roughly 120 jurisdictions committed to the Common Reporting Standard.
Who it affects: US business owners who hold or signed on foreign financial accounts in Common Reporting Standard participating jurisdictions, family offices with offshore structures, and single-member funds that use non-US custodians.
What to do
Ask each foreign financial institution that handles your accounts to confirm its Common Reporting Standard XML v3.0 upgrade timeline and whether a new self-certification form will be required. Refresh self-certifications before January 1, 2027 so that controlling-person identification, tax residences, and taxpayer identification numbers match the data you want transmitted. For accounts owned through US entities, reconfirm that the entity’s US tax residence is correctly recorded so that CRS reporting does not duplicate IRS information returns.
Primary source: OECD — Common Reporting Standard
AI tools are already reshaping tax administration
The Organisation for Economic Co-operation and Development’s Forum on Tax Administration has published material on how transformative artificial intelligence is changing tax policy design and the day-to-day administration of tax across member countries. Authorities are integrating artificial intelligence into risk scoring models, pre-audit case selection, automated compliance correspondence, and inconsistency detection between filings across jurisdictions. Several administrations have signaled that returns flagged by artificial intelligence models will be routed into enhanced review in filing season 2027, with the areas most often cited as artificial-intelligence targets being transfer pricing of intercompany services, royalty flows, and high-value value-added tax or goods and services tax refund claims.
Who it affects: US business owners whose group files tax returns in multiple jurisdictions, and owners whose returns touch areas that administrations are scoring aggressively with artificial intelligence — cross-border services, transfer pricing on royalties and management fees, and high-value value-added tax or goods and services tax refund claims.
What to do
Tighten the documentation on items most likely to trip artificial intelligence risk scoring: intercompany service agreements with recent price changes, value-added tax refund claims above the ordinary monthly threshold, and new or recently updated transfer pricing policies. Where an administration is known to use artificial intelligence to flag inconsistencies between filings across jurisdictions, pre-reconcile your returns before filing rather than relying on post-filing corrections.
Primary source: OECD — Forum on Tax Administration
What this means for your business
- European Union Pillar Two mechanics are now interconnected across member states — a missed global anti-base-erosion filing in one country creates exposure across your group through DAC 9 information exchange, not only in the country where you missed the deadline.
- The Common Reporting Standard XML schema v3.0 effective January 1, 2027 means your 2027 offshore account reporting will carry more identifying data on controlling persons and account classification; refreshing self-certifications now avoids correction cycles later.
- Artificial-intelligence-driven case selection narrows the window for thin documentation — the returns most exposed are the ones with the weakest paper trail on intercompany services, transfer pricing, and refund claims.
- A written global compliance calendar through the second quarter of 2027 is no longer optional for groups with Pillar Two exposure, offshore accounts, or filings in jurisdictions already using artificial intelligence in administration.
This week in international tax, one paragraph
Three cross-border moves to track: European Union member states are tightening Pillar Two compliance under DAC 9, offshore jurisdictions are moving to Common Reporting Standard XML schema version 3.0 effective January 1, 2027, and artificial-intelligence-driven case selection is live in enough member countries to change how US owners should document intercompany positions, refund claims, and cross-border consistency.
Frequently asked questions
Q. Our group is under the EUR 750 million Pillar Two threshold. Does DAC 9 affect us?
Not directly. Pillar Two mechanics apply only to multinational enterprise groups with consolidated revenue of EUR 750 million or more in at least two of the four preceding fiscal years. Below that threshold, you do not file a global anti-base-erosion information return and are not subject to the DAC 9 exchange. However, if an acquired entity or organic growth pushes the group above the threshold in a later year, DAC 9 filing obligations activate starting that year, and you will not have historical data in the form the directive requires. Groups approaching the threshold should begin building the data pipeline a full year in advance.
Q. Do I need to do anything personally for the Common Reporting Standard XML v3.0 change?
Your foreign financial institution files the Common Reporting Standard XML report itself. Your job is to make sure the self-certification form on file with each foreign institution accurately identifies controlling persons, tax residences, and taxpayer identification numbers — those are the inputs that feed the Common Reporting Standard XML report. Refresh self-certifications with every foreign financial institution before January 1, 2027 if any facts have changed since the certification you signed when the account was opened, and confirm that the institution has flagged the account as either pre-existing or new, since v3.0 adds reporting fields tied to that distinction.
Q. How do I know whether a tax authority is using artificial intelligence on my return?
Most tax administrations do not publicly flag which returns are scored by artificial intelligence. Treat the question operationally rather than forensically: strengthen documentation on the items most frequently discussed in administrations’ own artificial intelligence publications — transfer pricing of services and royalties, value-added tax refund claims, and cross-border consistency between filings — on every return in every jurisdiction. If a specific jurisdiction has publicly announced artificial-intelligence-based case selection in a filing season, prioritize pre-filing reconciliation across jurisdictions so the artificial-intelligence model does not flag false inconsistencies between returns.