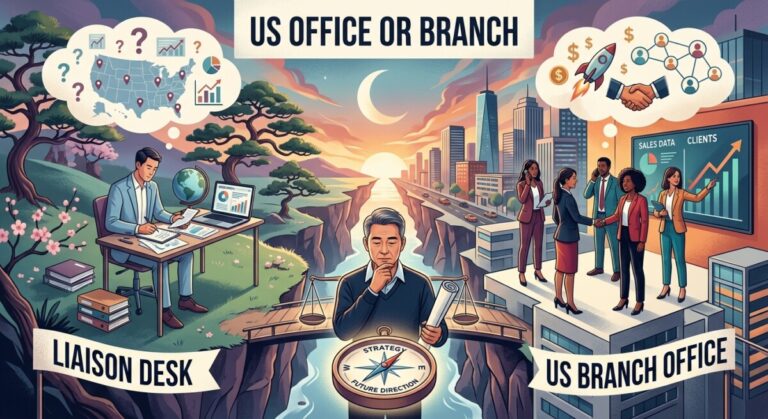
Side-by-side depiction of a US representative office and a US branch, contrasting the two US presence options a Korean parent company must choose between.
|

US representative office vs branch: what should a Korean parent set up?

If my Korean parent only wants to watch the US market, is a representative office enough — or do I already need a branch? A US representative office that limits itself to market research, information gathering, and liaison work typically falls outside the US “trade or business” definition under IRC §864(b), so it files no…
Business traveler and the 2026–2027 IRS per diem rates ($329 high-cost / $230 other CONUS)
|

What are the new IRS per diem rates for 2026–2027?

What are the new IRS per diem rates for 2026–2027? Notice 2026-60 sets the high-low per diem rates at $329 for high-cost localities and $230 elsewhere in CONUS, effective October 1, 2026. Transportation-industry M&IE is $80 CONUS and $86 OCONUS, and the incidental-only rate stays at $5 per day. Every October, a wave of expense-policy…

IRS Form SS-4 on a foreign founder's desk beside a passport and a laptop showing a US business bank account application.

How do I get an EIN without an SSN? (Foreign founder guide, 2026)

How do I get an EIN without an SSN as a foreign founder? You file IRS Form SS-4 by fax or by calling the International EIN line at +1-267-941-1099. An SSN or ITIN is not required for the responsible party if none exists — write “Foreign” on line 7b instead. Plan on roughly 4–8 weeks…

California digital products sales tax: SaaS and prewritten software become taxable January 1, 2027
|

Does California’s digital products sales tax apply to SaaS?

Does California’s digital products sales tax apply to my software business? Starting January 1, 2027, prewritten software — including Software-as-a-Service and remote-access licenses — is a taxable digital product under California’s new digital products sales tax rule enacted by Senate Bill 122. Custom software and several digital-media categories stay outside the rule. A short email…

ICE Endex Section 1256: Netherlands futures exchange now qualified for U.S. mark-to-market
|

Are ICE Endex futures Section 1256 contracts? (2026)

Are ICE Endex futures Section 1256 contracts now? Yes — for contracts entered into on or after September 1, 2026. In Rev. Rul. 2026-16, the IRS determined that ICE Endex, a Netherlands regulated exchange, is a qualified board or exchange under § 1256(g)(7)(C), so its futures and futures options get mark-to-market and 60/40 capital-gain treatment…

OBBBA method change: IRS Rev. Proc. 2026-32 covers § 174 R&E and § 460(e) residential construction
|

OBBBA method change under IRS Rev. Proc. 2026-32?

Does the IRS finally have an automatic-consent path for OBBBA R&E and residential construction changes? Yes. IRS Rev. Proc. 2026-32 opens the automatic OBBBA method change for § 174, § 174A, and § 460(e), waives the usual eligibility bars through 2027, and gives one transition window that closes November 15, 2026. On September 4, 2026,…

Small business owner using the IRS Business Tax Account on a laptop to view notices, download CP575, and manage payments
|

Who can use the IRS Business Tax Account (2026)?

Who can now use the IRS Business Tax Account? As of 2026, the IRS Business Tax Account covers partnerships, tax-exempt organizations, Indian tribal governments, and federal, state, and local governments, alongside the sole proprietors and corporations who had access before. Inside the account, entities can view digital notices, download CP575 EIN verification, and pay against…

Partnership merger tax rules under Sec. 708 showing two partnerships combining under the more-than-50% continuation test
|

How Partnership Merger Tax Rules Work Under Sec. 708

How do partnership merger tax rules work under Sec. 708(b)(2)(A)? A resulting partnership is a continuation of any merging partnership whose partners own more than 50% of the capital and profits of the resulting partnership; other merging partnerships terminate. Consideration mixing cash and interests triggers disguised-sale analysis, and the merger cash-out rule at Regs. Sec….

Concept image of a carbon capture facility and underground storage layers with an IRS notice overlay — 45Q safe harbor
|

45Q Safe Harbor: What Notice 2026-50 Changes for CCUS

Can I still claim the §45Q credit if EPA drops subpart RR reporting? Yes — the IRS just answered that question. Under the new 45Q safe harbor in Notice 2026-50, taxpayers who cannot rely on subpart RR of the Greenhouse Gas Reporting Program can still document secure geological storage for the §45Q credit, and the…

Federal tax changes for 2026 connecting Washington rulemaking to a small business counter with a card reader and calendar
|

Which 2026 Federal Tax Changes Affect Small Businesses?

Which 2026 federal tax changes affect my small business? The ones with a date attached: an August guidance package implementing the 2025 reconciliation law, backup withholding on payment-app settlements, the employer paid leave credit, and a September 30 federal funding deadline that decides how fast the IRS answers you this fall. Most tax headlines never…

Editorial illustration of the NYC junk fees rule — all-in pricing and one-click subscription cancellation for New York City consumers
|

NYC Junk Fees Rule: Does It Apply to My Business? (2026)

Does the new NYC junk fees rule apply to my business? If you sell goods or services in New York City — whether food delivery, tickets, hotels, gyms, or SaaS subscriptions — likely yes. The city’s new NYC junk fees rule and its final Click-to-Cancel rule change how you must price and how easily customers…

Foreign importer of record — cargo containers at a US port under tighter customs enforcement
|

Foreign Importer of Record: What Changes in Dec 2026?

Can a nonresident company still act as a US importer of record after December 2026? Only in a narrower form. A June 3, 2026 presidential executive order tightens eligibility, bonding, and disclosures for the foreign importer of record model, and pairs those customs changes with new federal-income-tax and state-nexus exposure. If your business imports into…

Illustration of OBBBA nonprofit tax rules — Capitol, donation box, university facade with IRC section tokens
|

OBBBA nonprofit tax: What changed for your 501(c)(3)?

What did the OBBBA actually change for my nonprofit? Quite a lot. The OBBBA nonprofit tax rules created a new charitable deduction for non-itemizers, added floors that shrink deductions for high-income and corporate donors, expanded the §4960 excise on high pay, and set a tiered endowment tax for large private colleges. The One Big Beautiful…

California outline over tax documents and a calendar highlighting the August 10, 2026 CCTC deadline
|

California Business Tax 2026: SB 122, SB 180 & CCTC

What changed for California business owners in 2026? The California business tax 2026 package brings SB 122 and SB 180 — extending the business credit limitation, cutting the first-year annual tax to $400 for many new entities, and stretching the California Competes Tax Credit through 2035. And the next CCTC application window closes on August…

Illustration of FinCEN BOI reporting in 2026 — a Treasury building with a BOI document, a green check on a U.S. flag and an orange warning on a foreign flag
|

FinCEN BOI Reporting 2026: Interim Final Rule Update

Do U.S. small businesses still have to file BOI with FinCEN in 2026? Not right now. Under Treasury’s March 2025 interim final rule, FinCEN BOI reporting applies only to foreign reporting companies. Domestic entities and U.S. citizens are exempt while FinCEN works to finalize the rule. The Corporate Transparency Act was supposed to be one…

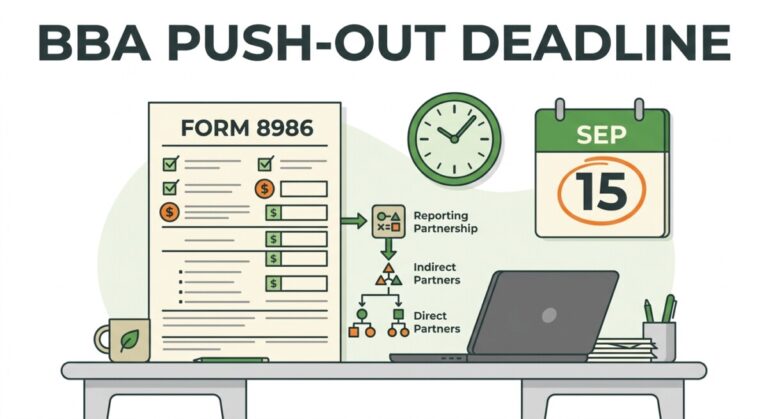
Illustration of an IRS Form 8986 with a September 15 deadline calendar and a partnership tier flow chart
|

BBA Partnership Audit 2026: Form 8986 Push-Out Deadline

When is the BBA partnership push-out deadline for a pass-through partner? If you received a Form 8986 tied to a partnership that filed an Administrative Adjustment Request (AAR) or was audited under the BBA partnership audit regime, the deadline to pay or push out further is generally September 15, 2026 — the exact date is…

Illustration of pass-through entity tax planning in 2026 — a US map, state connections, and tax filings representing PTET SALT cap workaround analysis
|

Pass-Through Entity Tax 2026: SALT Cap Workaround Guide

Is the pass through entity tax election still worth it after the higher SALT cap? For many owners of profitable pass-throughs in high-tax states, the answer is still yes — but the analysis is now owner-level, state-specific, and no longer automatic. The pass through entity tax (PTET) survived the 2025 SALT cap increase; the decision…

Illustration of an EIN verification letter being downloaded from the IRS Business Tax Account on a laptop
|

EIN Verification Letter: Download from IRS Business Tax Account

How do I get an EIN verification letter without calling the IRS? Designated officials on your IRS Business Tax Account can now log in and download an EIN verification letter instantly — no more calling and waiting weeks for Letter 147c in the mail. If you have ever tried to open a business bank account,…

Illustration of the IRS Opportunity Zone transition — an urban skyline with a December 31 clock over a development blueprint
|

IRS Opportunity Zone Transition Rules 2026: Notice 2026-40

Does the new Opportunity Zone regime just extend the old rules? No. The IRS Opportunity Zone transition rules in Notice 2026-40 keep the December 31, 2026 deferred-gain date, but reinvested QOF gains restart the 10-year clock and ongoing projects now need a written working-capital plan in place by year-end. The IRS has finally drawn a…

Illustration of a small business owner paying a summer seasonal employee alongside a Form 941 and a summer calendar
|

Hiring Seasonal Employees: 2026 Payroll Tax Guide

Do seasonal and part-time workers change my payroll tax obligations? No — hiring seasonal employees does not create a lighter set of federal payroll rules. Wages paid to summer, holiday, and part-time help are subject to the same federal income tax withholding, Social Security, and Medicare taxes as wages paid to your full-time staff. The…

Illustration of the California SaaS sales tax under SB/AB 122 — a state outline with a cloud icon over a stack of receipts, green and orange accents
|

California SaaS Sales Tax 2027: SB/AB 122 Guide

Update — September 26, 2026: SB 122 was signed on June 29, 2026 (Stats. 2026, ch. 23), and the California Department of Tax and Fee Administration (CDTFA) confirmed in Special Notice L-1036 (September 2026) that sales and use tax applies to digital products, including SaaS, beginning January 1, 2027. The original article below, published July…

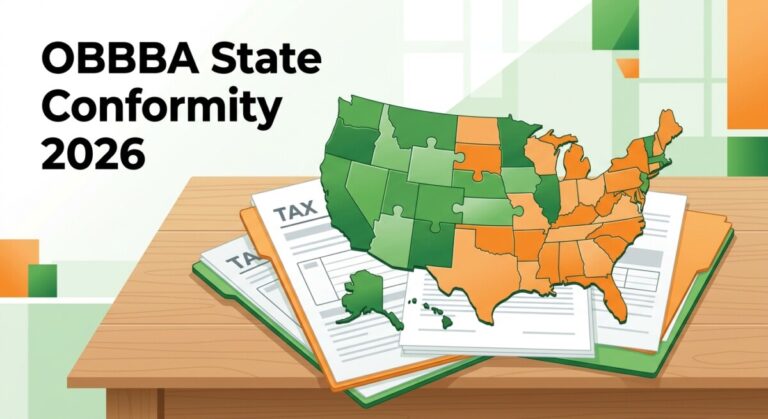
Illustration of OBBBA state conformity — a US map split into green and orange puzzle pieces over tax documents
|

OBBBA State Conformity 2026: Does Your State Follow?

Does my state follow the new federal OBBBA tax breaks? Not automatically. OBBBA state conformity varies widely — some states adopt the new federal rules on R&D expensing, bonus depreciation, and Section 179, while others decouple. A deduction you claim on your federal return may be added right back on your state return. The One…