Section 127 educational assistance employer tuition benefit featured
|

Section 127 Educational Assistance Programs: $5,250 Employer Tuition Benefit

What is a Section 127 educational assistance program and how much can employers provide tax-free? Section 127 of the Internal Revenue Code allows employers to exclude up to $5,250 per calendar year per employee from gross income for educational assistance — covering tuition, fees, books, supplies, and (through December 31, 2025, unless extended) qualified student…
Irs tax withholding estimator obbba mid year 2026 featured
|

IRS Withholding Estimator OBBBA: Mid-Year Tax Check Guide 2026

Why use the IRS Withholding Estimator OBBBA update for mid-year tax planning? The IRS Tax Withholding Estimator now reflects all the new OBBBA deductions and credits — tipped income, overtime pay, car loan interest, enhanced senior deduction, plus updated family, homeownership, and charitable giving items — making mid-year withholding adjustments essential to avoid surprise balance-due…

Wagering losses 90 percent limitation obbba slot machine featured
|

Wagering Losses 90% Limitation: OBBBA Section 165(d) and Slot Threshold

What is the new wagering losses 90% limitation under OBBBA? Section 70114(a) of the One Big Beautiful Bill Act amended IRC Section 165(d) to limit the deduction of wagering losses to 90% of the amount lost during the year — and only to the extent of wagering gains. Treasury’s proposed regulations (REG-113229-25) implement this change…

Capitol hill tax briefing may 2026 obbba budget featured
|

Capitol Hill Tax Briefing May 2026: OBBBA Healthcare, FY2026 Reconciliation, Form 990 Reform

What were the major Capitol Hill tax developments the week of May 1, 2026? The House Ways and Means Committee held a hospital-CEO hearing on healthcare costs and OBBBA impact, the House passed the FY2026 budget resolution 215-211 to launch border-security reconciliation, the chamber approved tax administration and relief bills with strong bipartisan margins, and…

State tax updates may 2026 deloitte multistate featured
|

State Tax Updates May 2026: California, Idaho, Illinois, Kansas, Kentucky

What are the most important state tax updates for May 2026? Deloitte’s State Tax Matters (Issue 2026-17) highlights five income/franchise developments — California’s agribusiness three-factor apportionment ruling, Idaho’s Supreme Court fiscal-year tax rate decision, Illinois’s intercompany interest addback, Kansas’s GILTI deletion, and Kentucky’s IRC §174A modifications — plus key sales/use updates. For multistate tax teams…

Erc disallowance form 907 irs extension 2026 featured
|

ERC Disallowance Form 907 Extension: New IRS Streamlined Process 2026

What is the new ERC disallowance Form 907 extension process? The IRS announced on April 27, 2026 (IR-2026-58) a streamlined way for taxpayers facing the 2-year refund-suit deadline after an Employee Retention Credit disallowance (Letter 105-C or 106-C) to submit Form 907 via the IRS Document Upload Tool — extending administrative review time and preserving…

California pte elective tax 2026 june 15 sb 132 featured
|

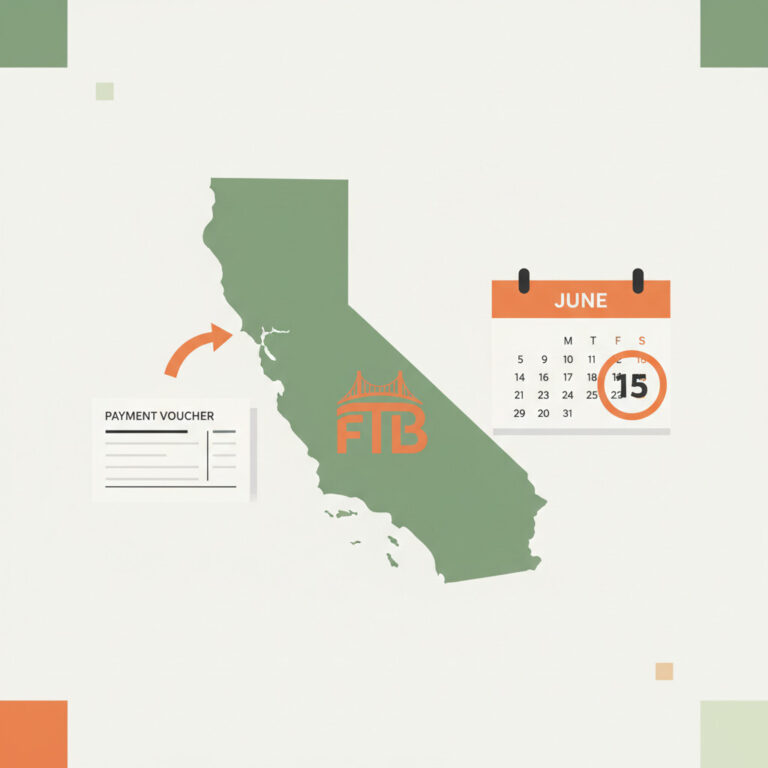
California PTE Elective Tax 2026: June 15 Payment Rules and SB 132 Changes

What are the California PTE elective tax 2026 deadlines and SB 132 changes? Qualified entities must make the PTE elective tax initial payment by June 15, 2026 — the greater of 50% of last year’s elective tax or $1,000 — or face a 12.5% reduction in PTE credit allocated to consenting partners under Senate Bill…

International tax updates may 2026 world tax advisor featured
|

International Tax Updates May 2026: Australia, Kuwait, OECD, UK and More

What are the most important international tax updates for May 2026? Deloitte’s World Tax Advisor (1 May 2026) highlights nine cross-border developments — including Australia’s revised transfer pricing for inbound distributors, Kuwait’s exemption from the 5% retention rule for Pillar Two MNEs, a UK Court of Appeal ruling on a treaty main purpose test, and…

Qualified opportunity zone designation 2027 obbba featured
|

Qualified Opportunity Zone Designation 2027: OBBBA Changes Explained

What is the qualified opportunity zone designation process for 2027? Rev. Proc. 2026-14 sets the procedure for State CEOs to nominate census tracts as QOZs effective January 1, 2027 — implementing the OBBBA’s overhaul of Sections 1400Z-1 and 1400Z-2, which now includes a new Qualified Rural Opportunity Fund (QROF) category and a flexible “applicable start…

Asu 2023 09 income tax disclosures fortune 500 first year featured
|

ASU 2023-09 Income Tax Disclosures: Fortune 500 First-Year Adoption

What is ASU 2023-09 and how are companies handling the new income tax disclosures in their first year? ASU 2023-09 requires public business entities to disclose an eight-category income tax rate reconciliation in both percentages and dollar amounts, plus jurisdictional disaggregation by state and country — and Fortune 500 first-year adoption shows California and Canada…

Tariff disclosures ieepa supreme court ruling 2026 featured
|

Tariff Disclosures After IEEPA Supreme Court Ruling 2026

How should companies handle tariff disclosures after the IEEPA Supreme Court ruling? The Supreme Court’s February 20, 2026 6-3 ruling that the IEEPA does not authorize presidential tariff impositions has shifted the disclosure landscape — and SEC guidance now expects MD&A coverage of magnitude, mitigation, recovery, and known trends, with quantification preferred and non-GAAP adjustments…

Ai disclosures 10k fortune 500 2025 sec focus featured
|

AI Disclosures 10-K: Fortune 500 2025 Trends and SEC Focus

What are the latest AI disclosures 10-K trends among Fortune 500 companies? 95% of Fortune 500 registrants now disclose AI-related matters in their 10-Ks (up from 84%), with Risk Factors leading at 95% — and the SEC is signaling a shift in focus toward AI governance, explainability, and emerging fraud risks. If you’re drafting your…

Government grants accounting us gaap featured
|

Government Grants Accounting: US GAAP Treatment and Disclosures

How should businesses account for government grants under US GAAP? US GAAP has no comprehensive standard for business government grants, so entities apply an accounting policy by analogy — typically IAS 20 (deferred income or net asset reduction), ASC 958-605 contribution model, or revenue recognition — and now must comply with ASU 2024-04’s enhanced disclosure…

Pik dividends measurement asu 2026 01 featured
|

PIK Dividends Measurement: ASU 2026-01 New FASB Guidance

What is the new PIK dividends measurement rule under ASU 2026-01? Issuers must measure paid-in-kind dividends on equity-classified preferred stock by multiplying the stated PIK dividend rate by the liquidation preference of the shares — eliminating the prior diversity in practice between discretionary and nondiscretionary approaches. On April 23, 2026 the FASB issued ASU 2026-01,…

Obbba tax deductions fy2027 irs budget update featured
|

OBBBA Tax Deductions: 60M Filers Claim, FY2027 IRS Budget Update

How are the new OBBBA tax deductions performing in the 2026 filing season? More than 60 million taxpayers have claimed at least one OBBBA deduction — 34M for the senior deduction, 28M for overtime, and 7M for tipped income — even as the House Appropriations Committee advances a $10.2B FY2027 IRS budget that would cut…

State tax updates april 2026 obbba conformity featured
|

State Tax Updates April 2026: OBBBA Conformity, PTET, R&D Credits

What are the most important state tax updates April 2026? Multiple states moved on OBBBA conformity (Oregon, Maine, Kentucky, New Mexico), Maine created a new PTET and 2% high-income surcharge, Wisconsin extended R&D credit carryforwards to 50 years, Kentucky added a 14.25% prediction-market excise, and Washington’s new 9.9% personal income tax on income over $1M…

Irs tax debt resolution options 2026 featured
|

IRS Tax Debt Resolution: Installment Agreements, OIC, and Penalty Abatement

What are the IRS tax debt resolution options if I can’t pay what I owe? The IRS offers four main paths: short-term and long-term Installment Agreements, Offer in Compromise (OIC) for those who can prove inability to pay, Currently Not Collectible (CNC) status to pause collections, and Penalty Abatement to reduce or eliminate associated penalties….

Ferc gaap accounting differences 2026 featured
|

FERC GAAP Accounting Differences: 2026 Update for Utilities

What are the key FERC GAAP accounting differences for power and utility companies? FERC uses equity-method accounting for all subsidiaries regardless of ownership, classifies certain non-utility activities “below the line,” includes accumulated cost of removal in accumulated depreciation, and lacks the current/long-term distinction common in US GAAP — creating systematic reconciliation work for every regulated…

Irs 2026 filing season recap fy2027 budget featured
|

IRS 2026 Filing Season Recap: Bisignano Testimony and Budget Cuts

How did the IRS 2026 filing season perform and what’s next for the agency? IRS CEO Frank Bisignano reported 134 million returns filed, a $3,400 average refund up 11%, and $2 billion collected from the agency’s five largest enforcement cases — even as House appropriators propose a 9% FY2027 budget cut. The IRS 2026 filing…

Foreign earned income exclusion relief 2026 featured
|

Foreign Earned Income Exclusion Relief: Rev. Proc. 2026-16 Countries

What is the foreign earned income exclusion relief under Rev. Proc. 2026-16? The IRS waives the section 911 residency and presence tests for 2025 for qualified individuals who had to leave seven specified countries due to war, civil unrest, or similar adverse conditions. If you’re a US citizen or resident who was living abroad and…

Internal use software capitalization asu 2025 06 featured
|

Internal Use Software Capitalization: ASU 2025-06 Explained

What changed for internal use software capitalization under ASU 2025-06? The FASB eliminated the old project-stage gating and replaced it with a single “probable-to-complete” threshold — finally aligning US GAAP with how agile software development actually works in 2026. If you’ve ever tried to apply the 1998 internal-use software rules to a modern agile sprint,…

Global tax updates april 2026 featured
|

Global Tax Updates April 2026: APA, Stock Buyback, Belgium CGT

What are the biggest global tax developments in April 2026? Key global tax updates april 2026 from Deloitte’s World Tax Advisor cover the U.S. 2025 APA Report, final stock buyback excise tax rules, Belgium’s new capital gains regime, UAE’s R&D credit, Norway’s Supreme Court transfer pricing ruling, and retroactive Australian CGT changes for foreign residents….

Qualified tips deduction final rule occupations featured
|

Qualified Tips Deduction: IRS Final Rule & Occupations List 2026

Which jobs qualify for the new qualified tips deduction under OBBBA? The IRS final rule under Section 224 lists 68 tipped occupations across 8 categories — from servers and bartenders to barbers, delivery drivers, golf caddies, and digital content creators — capped at $25,000 per year through 2028. The long-awaited IRS final regulations on the…

Foreign housing exclusion 2026 irs limits featured
|

Foreign Housing Exclusion 2026: IRS Notice 2026-25 Limits

How much can U.S. expats deduct for housing costs abroad in 2026? Under the foreign housing exclusion 2026 limits just released in IRS Notice 2026-25, the cap ranges from $39,870 in standard locations to $114,300 in Hong Kong, with more than 400 high-cost cities receiving upward adjustments. If you’re a U.S. citizen or resident earning…

Advance pricing agreement 2026 featured
| |

Advance Pricing Agreement 2026: IRS APA Guide for CFOs

Is an APA the right tool for your multinational’s transfer pricing strategy? An advance pricing agreement 2026 locks in an IRS-approved transfer pricing method for up to five prospective years, eliminating audit risk and double taxation for multinationals operating between the US and foreign jurisdictions. For multinational companies with intercompany transactions crossing US borders, transfer…

Efin application 2026 guide featured
|

EFIN Application 2026: Guide for Tax Preparers & CPAs

Planning to e-file tax returns in 2026? Everything tax professionals and CPA firms need to know about obtaining, protecting, and managing an Electronic Filing Identification Number — the EFIN application 2026 process from e-Services application to suitability checks, fingerprinting, and fraud prevention. If you are planning to e-file federal tax returns as a paid preparer…

Remittance transfer tax 2026 featured
|

Remittance Transfer Tax 2026: OBBBA 1% Excise Guide

How does the new 1% remittance tax affect LA families? The new remittance transfer tax 2026 imposes a 1% excise on cash-based international money transfers under OBBBA Section 4475. Learn exemptions, compliance tips, and how to legally reduce exposure. The remittance transfer tax 2026 is officially here. With the enactment of the One, Big, Beautiful…

Bba partnership audit 2026 featured
|

BBA Partnership Audit 2026: Form 8979 & AAR Update

Is your partnership ready for the 2026 BBA changes? Form 8979 was revised September 2025 and AAR procedures updated for 2026. Learn what LA partnerships and CPAs must know about the latest BBA partnership audit 2026 rules. If you manage a partnership, LLC, or real estate syndicate with complex K-1 filings, the IRS just handed…