Illustration of 2026 homeowner tax deductions — the new $40,000 SALT cap on real estate taxes, mortgage interest limits, and non-deductible home costs on IRS Schedule A
|

Homeowner Tax Deductions 2026: New $40,000 SALT Cap Guide

What home expenses can you actually deduct in 2026 — and what’s the new SALT cap? To deduct homeownership expenses you must ITEMIZE. The two main deductible items are (1) state and local real estate taxes — now subject to a $40,000 limit ($20,000 if married filing separately) under the increased SALT deduction cap —…

Illustration of Form 990 filing requirements and the IRC section 6033(j) three-year automatic revocation trap for tax-exempt nonprofit organizations
|

Form 990 Filing & the 3-Year Automatic Revocation Trap

Which Form 990 must your nonprofit file, and what happens if you miss it? Most tax-exempt organizations must file an annual return in the Form 990 series, due by the 15th day of the 5th month after the organization’s accounting period ends (May 15 for calendar-year filers). Which form you file — 990-N, 990-EZ, 990,…

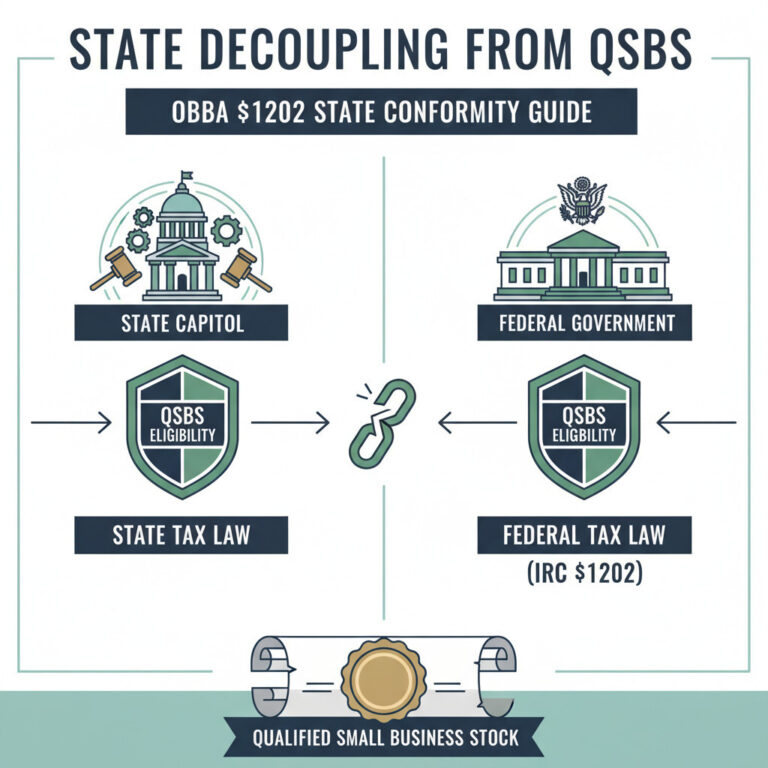
Illustration of state decoupling from federal QSBS section 1202 exclusion under OBBBA — Maine and Oregon decoupled, California taxes QSBS gains, state conformity risk for founders
|

State Decoupling from QSBS: OBBBA §1202 State Conformity Guide

Do states follow the federal QSBS exclusion under OBBBA — and why does state conformity matter? Not automatically. The One Big Beautiful Bill Act (OBBBA, Pub. L. No. 119-21) expanded the federal Qualified Small Business Stock (QSBS) exclusion under IRC §1202 — but states set their own conformity. Maine and Oregon have enacted legislation DECOUPLING…

Illustration of the ISSB global baseline for sustainability disclosure — IFRS S1 and IFRS S2 four-pillar framework converging across China CSDS, EU CSRD, and US California SB 253/261
|

ISSB Global Baseline: IFRS S1/S2 Sustainability Disclosure Guide

What is the ISSB global baseline for sustainability disclosure, and why does it matter in 2026? The International Sustainability Standards Board (ISSB) — established by the IFRS Foundation — issued IFRS S1 (general sustainability-related financial disclosures) and IFRS S2 (climate-related disclosures) as a global baseline for how companies report sustainability information to investors. By 2026,…

Illustration of FASB transferable tax credits accounting project — IRA, CHIPS, and OBBBA credit accounting gap, ASC 740 vs ASC 832 analogies, recognition triggers
|

FASB Transferable Tax Credits Project: Accounting Gap Guide

How should companies account for transferable tax credits under U.S. GAAP? The Financial Accounting Standards Board (FASB) voted in May 2026 to advance a project on the accounting treatment of nonrefundable transferable tax credits — including the Inflation Reduction Act (IRA) clean energy credits under IRC §6418, CHIPS and Science Act semiconductor credits, and One…

Illustration of California SB 253 Scope 1 and Scope 2 emissions measurement — GHG Protocol methodology, location-based vs market-based dual reporting, June 30 2026 filing
|

SB 253 Scope 1+2 Guide: June 2026 Filing + Limited Assurance

How do California SB 253 reporting entities measure Scope 1 and Scope 2 emissions for the June 30, 2026 first filing? SB 253 (Health & Safety Code §38532) requires U.S. companies with revenues over $1 billion doing business in California to publicly disclose Scope 1 (direct) and Scope 2 (purchased energy) greenhouse gas emissions starting…

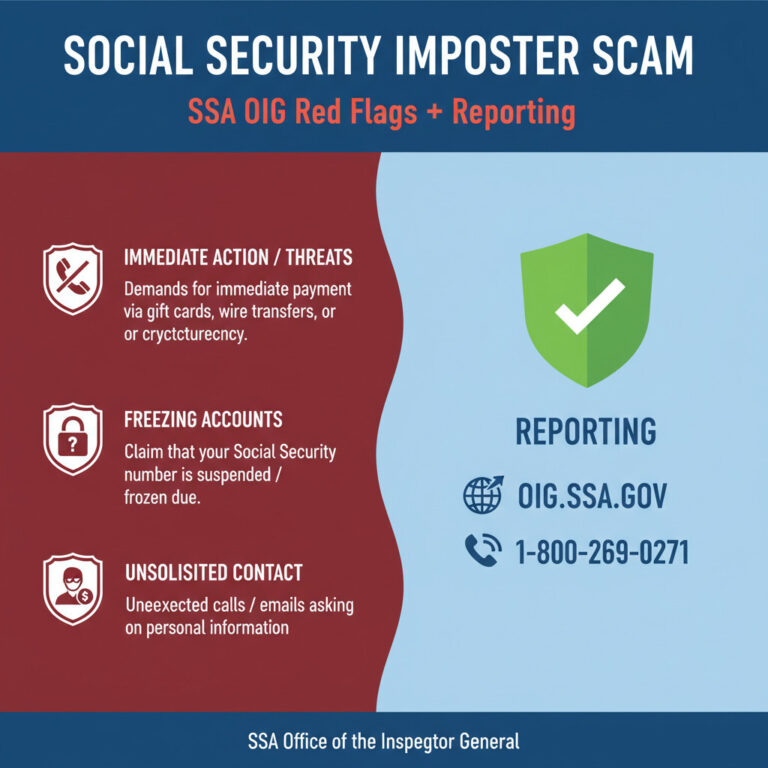
Illustration of Social Security imposter scam red flags — SSA OIG warning about doctored badge photos, gift card demands, and federal fraud reporting channels
|

Social Security Imposter Scam: SSA OIG Red Flags + Reporting

How can you tell a Social Security imposter scam from a real government contact? The Social Security Administration Office of the Inspector General (SSA OIG) issued a fresh warning in 2026 about a rising imposter scam: criminals impersonate real federal employees by harvesting names from social media and sending doctored badge photos to “verify” their…

Illustration of IRS Offer in Compromise process — Form 656-B application, Reasonable Collection Potential calculation, and 2026 Dirty Dozen OIC mills warning
|

IRS Offer in Compromise: Form 656-B + 2026 OIC Mills Warning

How does the IRS Offer in Compromise work, and how do you avoid OIC mills? An IRS Offer in Compromise (OIC) is a legally-binding agreement between a taxpayer and the IRS to settle outstanding tax debt for less than the full amount owed. You apply with Form 656-B (Offer in Compromise Booklet) plus a $205…

Illustration of California SB 261 climate-related financial risk reporting — TCFD four-pillar framework and January 1, 2026 first-cycle deadline
|

SB 261 Climate Financial Risk Reporting: TCFD Guide Jan 2026

What does California SB 261 require for climate-related financial risk reporting? California’s SB 261 (Public Resources Code §38533, the Climate-Related Financial Risk Act, as amended by SB 219) requires U.S. companies with annual revenues over $500 million doing business in California to publish a biennial climate-related financial risk report. The first report is due January…

Illustration of IRS No Tax on Tips final regulations under the One Big Beautiful Bill — Treasury Tipped Occupation Code list and qualified tips definition
|

No Tax on Tips Final Regulations: 70+ Occupations, Qualified Tips Guide

Who qualifies for the No Tax on Tips deduction under the final regulations? The Treasury and IRS issued final regulations on April 10, 2026 (IR-2026-49) implementing the “No Tax on Tips” deduction under the One, Big, Beautiful Bill Act (OBBBA). Workers in 70+ occupations on the Treasury Tipped Occupation Code (TTOC) list can deduct qualified…

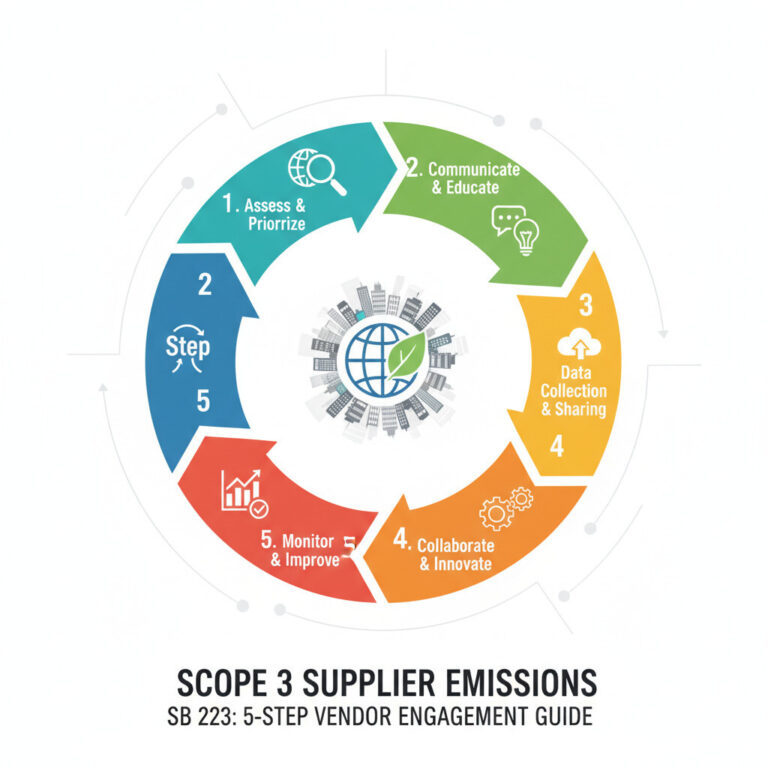
Illustration of Scope 3 supplier emissions reporting for California SB 253 — GHG Protocol value chain methodology and 5-step vendor engagement program
|

Scope 3 Supplier Emissions for SB 253: 5-Step Vendor Engagement Guide

How do California companies collect Scope 3 supplier emissions data for SB 253? California’s SB 253 requires companies with over $1 billion in U.S. revenue doing business in California to disclose Scope 1, 2, AND 3 greenhouse gas emissions — with Scope 3 disclosure due January 1, 2027 (based on 2026 fiscal year data). Because…

Illustration of CARB SB 253 August 2026 reporting deadline and SB 261 court injunction — California climate disclosure enforcement update
|

CARB SB 253 August 2026 Deadline: California Climate Disclosure Enforcement Update

What’s the latest status on California’s CARB SB 253 enforcement timeline and SB 261 court injunction? The California Air Resources Board (CARB) approved its SB 253 / SB 261 implementing regulation on February 26, 2026, setting an initial Scope 1 and Scope 2 GHG reporting deadline of August 10, 2026 for SB 253. A November…

Illustration of ASU 2023-05 joint venture formations accounting — fair value measurement at formation date under Subtopic 805-60
|

ASU 2023-05 Joint Venture Formations: Fair Value Accounting Guide

What does ASU 2023-05 require for joint venture formation accounting? Under FASB Accounting Standards Update 2023-05, joint ventures must record assets received and liabilities assumed at fair value at the formation date — adopting a new basis of accounting on day one. The guidance is in new Subtopic 805-60 and is effective prospectively for any…

Illustration of California climate disclosure laws SB 253 and SB 261 — Scope 1-3 emissions and climate financial risk reporting compliance
|

California Climate Disclosure SB 253 and SB 261: 2026 Compliance Guide

What are California climate disclosure laws SB 253 and SB 261 — and who must comply in 2026? California’s Climate Corporate Data Accountability Act (SB 253) requires companies with annual revenue above $1 billion that do business in California to disclose Scope 1, 2, and 3 greenhouse gas emissions. SB 261 (Climate-Related Financial Risk Act)…

Illustration of pooled employer plan PEP 401k vs state auto-IRA mandate — small employer retirement compliance and fiduciary delegation
|

Pooled Employer Plan vs State Auto-IRA: PEP 401(k) Guide for Small Employers

How does a Pooled Employer Plan (PEP) compare to a state-mandated auto-IRA? A Pooled Employer Plan is a multi-employer 401(k) structure that satisfies state retirement mandates while offering meaningful advantages over state-sponsored auto-IRAs: $24,500 contribution limit (vs. $7,500 IRA), employer matching, institutional-quality investments, and fiduciary shift to the Pooled Plan Provider. For most small employers,…

Illustration of FASB equity method targeted improvements 2026 — significant influence threshold and GP partnership investment treatment
|

FASB Equity Method Targeted Improvements: 2026 Tentative Board Decisions

What did the FASB decide on equity method targeted improvements at the May 13, 2026 Board meeting? The FASB tentatively decided to apply a single “significant influence” threshold for the equity method regardless of entity type, remove the 20% presumption, broaden the board-of-directors indicator to functionally-equivalent governing bodies, and require general-partner significant-influence treatment for noncontrolling…

Illustration of construction revenue recognition methods — percentage of completion vs completed contract for contractors
|

Construction Revenue Recognition: PCM vs CCM Methods Explained

What are the construction revenue recognition methods and when does each apply? Construction contractors choose between the percentage of completion method (PCM) — recognizing revenue proportionally as work progresses — and the completed contract method (CCM) — deferring all revenue until substantial completion. PCM is mandatory for long-term contracts held by companies with average annual…

Illustration of IRS Notice 2026-34 defined benefit pre-approved plan Cycle 4 cumulative list — provider and sponsor compliance
|

IRS Notice 2026-34: Defined Benefit Pre-approved Plan Cycle 4 Cumulative List

What does IRS Notice 2026-34 require for defined benefit pre-approved plan Cycle 4 submissions? Notice 2026-34 publishes the 2026 Cumulative List of plan qualification changes that providers must reflect in defined benefit qualified pre-approved plan documents submitted for the fourth remedial amendment cycle (Cycle 4) — submission window August 1, 2026 to July 31, 2027…

Illustration of federal student loan caps 2026 — Graduate PLUS phase-out and accounting profession recognition gap
|

Federal Student Loan Caps 2026: Graduate PLUS Phase-Out and Accounting Impact

What are the federal student loan caps 2026 effective July 1? The Department of Education’s final rule eliminates unlimited borrowing under the Graduate PLUS Program effective July 1, 2026. Eleven designated “professional” degrees (law, medicine, dentistry, etc.) face $50K annual / $200K aggregate caps. All other graduate fields — including accounting, engineering, and nursing —…

Illustration of cannabis 280E rescheduling — Schedule III medical cannabis tax change and MSO allocation impact
|

Cannabis 280E Rescheduling: Schedule III Medical Cannabis Tax Impact

What does cannabis Schedule III rescheduling mean for IRC Section 280E? The DOJ and DEA’s April 23, 2026 order rescheduling medical cannabis from Schedule I to Schedule III removes it from § 280E’s deduction prohibition — potentially cutting cannabis operators’ effective tax burden from 50-60% of operating income to closer to normal corporate rates, and…

Illustration of US state wealth tax 2026 proposals — California billionaire ballot, NYC pied-à-terre, multistate HNW planning
|

State Wealth Tax 2026: Billionaire and Millionaire Proposals Spreading

Which states are pushing state wealth tax 2026 proposals on millionaires and billionaires? At least a dozen states — including California, Illinois, Minnesota, New York, Rhode Island, and Virginia — have advanced new tax proposals targeting the wealthiest taxpayers in 2026. Mechanisms range from one-time billionaire net-worth levies (California ballot) to pied-à-terre property taxes (NYC),…

Illustration of IRS conservation easement settlement opportunity 2026 — partnership tax controversy guidance
|

IRS Conservation Easement Settlement Opportunity 2026 — IR-2026-63

What is the IRS conservation easement settlement opportunity announced in 2026? Per IR-2026-63 (May 6, 2026), the IRS updated its Conservation Easement site with expanded warnings on abusive transactions and recent court decisions, and announced a forthcoming time-limited settlement program — letting eligible partnerships resolve disputed federal tax consequences with certainty before pursuing litigation. If…

Ipa tariff refund cape system importers guide featured
|

IPA Tariff Refund CAPE System: Step-by-Step Guide for Importers

What is the IPA tariff refund CAPE system and how do importers claim refunds? Following the Supreme Court’s invalidation of IEEPA-based tariffs, CBP launched the CAPE refund mechanism on April 20, 2026 — a new submission system within the ACE environment for recovering an estimated $166 billion collected between April 2025 and February 2026 across…

Sec semiannual reporting form 10 s proposed rules featured
|

SEC Semiannual Reporting Framework: Form 10-S Proposed Rules

What is the SEC’s proposed semiannual reporting framework? On May 5, 2026 the SEC proposed rules allowing public companies to opt into semiannual reporting via a new Form 10-S — replacing three Form 10-Q filings per year with one mid-year report. Quarterly remains the default; semiannual is an annual opt-in election made on the cover…

Rev proc 2026 21 irs corporate letter ruling program featured
|

Rev. Proc. 2026-21: New IRS Corporate Letter Ruling Program

What does Rev. Proc. 2026-21 change about IRS letter rulings on corporate transactions? Rev. Proc. 2026-21 establishes a new letter ruling program under the Associate Chief Counsel (Corporate) — modifying Rev. Proc. 2026-1 and 2026-3 to expand the scope of significant-issue and transactional rulings available for §§ 332, 351, 355, 368, and 1036 reorganizations, while…

State tax updates may 8 2026 multistate developments featured
|

State Tax Updates May 8 2026: California, Maryland, NY, MA, Nevada

What are the most important state tax updates from May 8, 2026? A California appellate court rejected the FTB’s “unitary business” theory against a Texas-based remote contractor, Maryland enacted OBBBA decoupling and PTET changes via the BRFA of 2026, New York’s appellate court affirmed Article 9-A’s P.L. 86-272 internet activity rule, Massachusetts addressed penny-shortage rounding…

International tax updates may 8 2026 pillar two oecd featured
|

International Tax Updates May 8, 2026: Pillar Two, OECD Toolkit, Korea Filing

What are the most important international tax updates from May 8, 2026? Deloitte World Tax Advisor highlights ten cross-border developments — most notably the OECD’s Global Minimum Tax Implementation Toolkit, Korea’s Pillar Two filing notices to over 10,000 entities for the May–June 2026 first filing season, and New Zealand’s compliance simplification act — alongside Australia,…